Credit Score Improver: Can an App Really Raise Your Score?
An honest answer from a company that makes one of these apps: what they can do, what they can't, and what you can do without any app.

A credit score improver app can't raise your score by itself. Only your lenders' reports change it, and they reflect what you do: paying on time, using less of your card limit, applying less often. What a good app can do is show your full report, spot errors, rank the fixes and remind you. That's useful. It isn't magic.
Key TakeawaysYour score changes only when lenders report new data to a bureau. Since 1 July 2026 they report every week (RBI).Every bureau must give you one free full credit report a year, so you can start without any app (RBI).No app or agency can delete accurate late payments or defaults. Only genuine errors can be corrected.GroScore is our own app. It shows your Equifax score, not a CIBIL score, and it is not a lender (groscore.in).
What Is a Credit Score Improver App?
A credit score improver is an app that reads your credit report and helps you act on it. People search for it under different names: a credit score increase app, a credit improvement app, a credit builder app. Most of them do some mix of five things.
- Fetch your score and full report from a credit bureau, with your consent.
- Explain what's in it in plain language.
- Flag what's hurting you, such as high card use, a late payment or an account you don't recognise.
- Rank which fix to do first.
- Track the report each month and alert you to changes.
Some also suggest products for people with thin files, such as a secured card against a fixed deposit. Others go further and show which lenders' criteria your profile might meet.
Before we go further, a disclosure. GroScore, which publishes this blog, is one of these apps. We've tried to write this so it's useful even if you never install ours, and the last section covers everything you can do with no app at all.
Can an App Increase Your Credit Score?
Not directly. Your score is calculated by a credit bureau from data your banks and NBFCs report. Apps sit outside that loop. They can read the data. They can't change it.
What an app changes is your behaviour, and that's where the score moves. If an app reminds you to pay before the statement date, or shows that one card is nearly maxed, the action is yours. The next lender report carries it to the bureau.
| What an app can do | What an app can't do |
|---|---|
| Show your score and full report | Change what lenders report |
| Explain each entry in plain words | Delete accurate late payments |
| Rank fixes for your profile | Promise a number of points |
| Alert you to new enquiries and errors | Speed up the bureau's update |
| Help you raise a dispute | Decide a dispute for the bureau |
| Show offers you may qualify for | Approve a loan or card |
So when an app is called a "CIBIL score increase app", read that as shorthand. The best it can do is help you improve the inputs.
An app can show and rank fixes. Changing the data is up to you and your lenders.
If you want the full list of fixes in order, read how to improve your credit score.
Credit Coach App vs Credit Repair Agency: What's the Difference?
Both promise to help. They work very differently.
A coach app reads your report and tells you what to do. It's usually free to check your score, and the work stays in your hands.
A credit repair agency says it will fix your report for you, usually for a fee. Some agencies do genuine work, such as helping you file a dispute for a real error. Many overpromise. If an agency claims it can remove a default, a settled status or an accurate late payment, it's selling something nobody can deliver. Accurate entries stay on your report.
Here's the part agencies rarely mention. Disputing a genuine error is free, and you can do it yourself with the bureau. Under the RBI's credit information rules (2025), a complaint about wrong credit data should be resolved within 30 calendar days. If it isn't, you're owed Rs 100 for every day of delay (RBI). Our review of CIBIL score improvement agencies covers what they can and can't legally do.
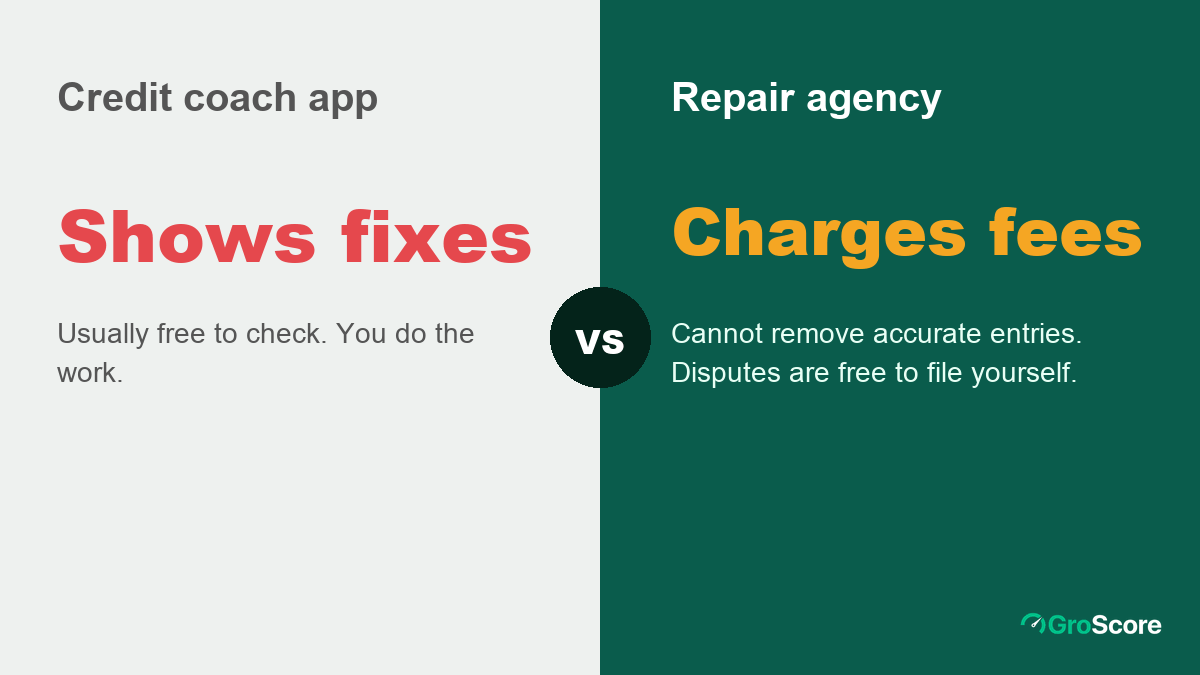
Same goal, very different promises.
Red flags for any app or agency: an upfront fee to "boost" your score, a promise of a set number of points, a promise to boost credit score overnight, or a request for your bank password or UPI PIN. Walk away from all of them.
Is It Safe to Share Your PAN With a Credit Score App?
Usually, yes, if the app is genuine. To find your report and confirm it's you, a bureau needs your PAN, name, date of birth and mobile number. Checking your own score is a soft enquiry, so it never lowers it.
Before you enter anything, check five things:
- The bureau is named. A genuine app says where your score comes from (Equifax, TransUnion CIBIL, Experian or CRIF High Mark).
- Consent is clear. You should see what you're agreeing to before the app fetches your report.
- A privacy policy exists and says how your data is used and stored.
- No sensitive banking details. No genuine credit score app needs your net-banking password, card PIN or UPI PIN.
- No guaranteed results. An app that promises points is telling you something false.
If you've already shared details with an app that later asked for money to "unlock" a better score, stop. Report the app on the Play Store. If money was taken, tell your bank straight away and file a complaint on the national cybercrime helpline.
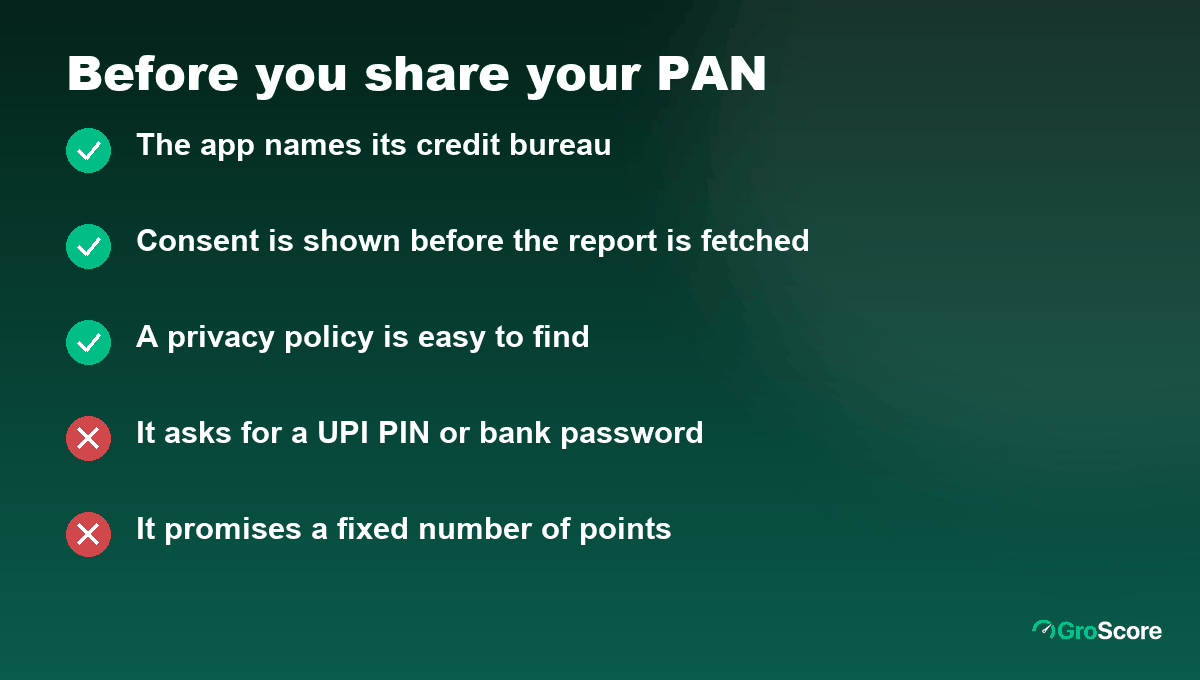
Five checks before you type your PAN anywhere.
What Does GroScore's Coach Arjun Actually Do?
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender, and the score it shows is your Equifax score, not a CIBIL score.
The Equifax point matters if you searched for a CIBIL score app. TransUnion CIBIL is one of four RBI-registered credit bureaus. Each calculates its own score from what lenders report, so your CIBIL and Equifax scores are usually close but rarely identical. The fixes are the same for both.
Arjun, GroScore's credit coach, reads your report and ranks what to fix. Here's an illustrative example, not a real customer. Say Sneha, 26, sees an Equifax score of 694 and thinks her card use is fine.
- Card A has a Rs 30,000 limit and a Rs 25,000 balance, which is 83% used.
- Card B has a Rs 70,000 limit and a Rs 5,000 balance, about 7% used.
- Together, that works out to Rs 30,000 of Rs 1,00,000, or exactly 30%.
Overall, she looks fine. Card A, though, is nearly maxed, and a lender reading the report sees that too. Arjun flags it first and suggests moving spending to Card B and paying Card A down before its statement date. Paying Card A down to Rs 9,000 works out to 30% of its limit, and because lenders report every week under RBI rules, the lower balance can show within weeks. He also flags an enquiry from a lender she's never applied to, which could be a mistake or fraud, so she checks it with the lender and the bureau.
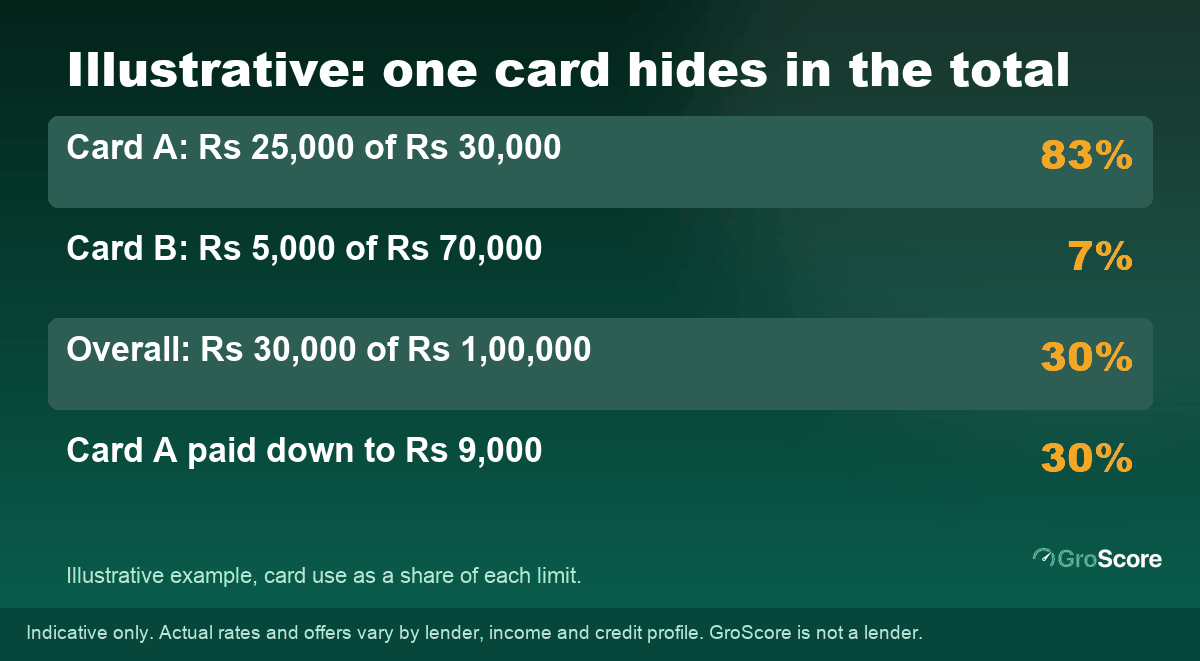
Illustrative example: the overall figure can hide a maxed card.
GroScore's guidance is to keep total card use under 30% (groscore.in, retrieved 2026-10-05), on each card as well as overall.
Arjun's ranking draws on patterns from 1 lakh+ analysed credit reports, and GroScore says it has helped 50,000+ users (groscore.in, retrieved 2026-10-05). Those are GroScore's own figures. None of it guarantees a result for you.
What Arjun can't do: change your report, remove accurate entries, or give you a loan. GroScore can show which lenders' criteria your profile clears, but every loan and card decision is the lender's.
How to Pick a Credit Score Improver That's Honest
If you compare a few apps, look for the same basics in each. Here are the credit score apps compared side by side, if you want a wider view.
- It names its bureau and shows the full report, not just a number.
- Checking is free and a soft enquiry.
- It explains why each fix matters and in what order.
- It says plainly what it can't do.
- It never charges you to file a dispute you could file free.
What Can You Do Without Any App?
Everything an app does, you can do by hand. You'll just spend more time on it.
Get your free reports. Under the RBI's credit information rules (2025), each of the four bureaus must give you one free full report, with your score, every calendar year. Request them from each bureau's website.
Read them line by line. Check your personal details, every account, the payment grid (look for anything other than "000" or "STD") and the list of enquiries.
Dispute genuine errors directly with the bureau, with proof.
Do the habits. Autopay every EMI, keep card use low, apply only when you need credit, keep old cards open.
Diarise a check. Pull a fresh report every few months to catch errors and fraud early.
Five steps, and that's the whole job. Apps save time and catch things you might miss, but the work that raises a score is the same either way.
Frequently Asked Questions
Can an app increase my credit score?
Not by itself. A credit score improver app can show your report, rank fixes and remind you to pay. Your score changes when lenders report your new behaviour to the bureau, so the improvement comes from what you do.
How is a credit coach app different from a repair agency?
Coach apps show you what to fix and leave the work with you, usually free. Repair agencies offer to fix things for a fee. Neither can remove accurate entries, and you can dispute genuine errors yourself at no cost.
Is it safe to share my PAN with a credit score app?
Usually, if the app names its bureau, asks for clear consent and has a privacy policy. Checking your own score is a soft enquiry and doesn't lower it. Never share a net-banking password, card PIN or UPI PIN with any credit score app.
What does GroScore's coach Arjun actually do?
Arjun reads your Equifax report, explains it in Hindi or English, ranks the fixes for your profile and tracks your report monthly with alerts. He can't change bureau data, remove accurate entries or approve a loan.
Can a credit score app show my CIBIL score?
Only if it fetches your report from TransUnion CIBIL. GroScore fetches from Equifax, so it shows your Equifax score. Scores from different bureaus are usually close but not identical.
The Bottom Line
A credit score improver is a tool, not a shortcut. Good ones show you the whole report, tell you what to do first and keep you honest month after month. Bad ones charge a fee and promise points. Whichever you use, the score moves only when your habits and your lenders' reports do. For what can realistically show in the first few weeks, see how to improve your credit score fast.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
