Best CIBIL Score App in India: Free Credit Score Apps Compared
Which bureau, what it costs, how deep the report goes and what happens to your data: the five questions that pick the right app.

The best CIBIL score app is the one that shows the bureau you need, for free, with a soft check and a full report. For the CIBIL score itself, go to TransUnion CIBIL. For a free score you can track every month, a credit score app works well, as long as it names its bureau and treats your data carefully.
Key TakeawaysIndia has four RBI-registered credit bureaus: TransUnion CIBIL, Equifax, Experian and CRIF. Each produces its own 300 to 900 score (RBI).Every bureau must give you one free full credit report a year under RBI rules (RBI).A good credit score app names its bureau, uses a soft check, shows the full report and explains what it does with your data.GroScore is our own app. It shows your Equifax score, not your CIBIL score, and it isn't a lender.
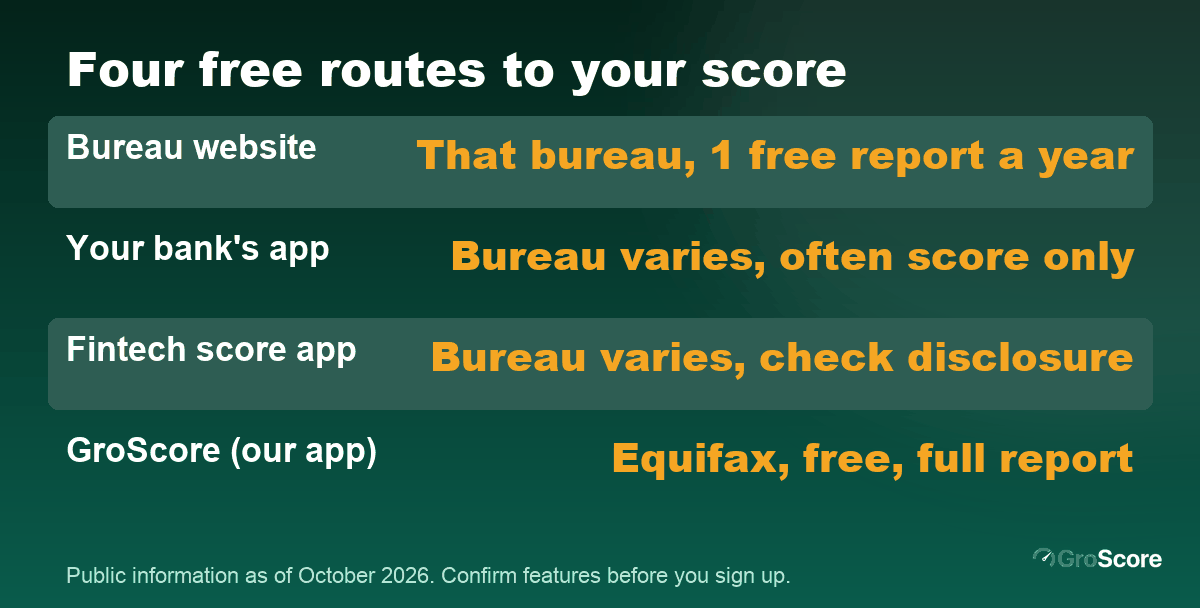
Four routes to a free score, compared on the same criteria.
How We Compared Credit Score Apps
A note on fairness. GroScore publishes this page, and GroScore is one of the options below. We've compared the routes on criteria you can check yourself, and we've said where GroScore doesn't win. You don't need to install GroScore to use this guide.
We didn't rank brands. Apps change their features and partners too often for a brand ranking to stay true. Instead, we compared the four routes most people use, on five criteria:
- Data source. It tells you which bureau the score comes from. This decides whether you're looking at a CIBIL score or another bureau's.
- Cost. The check may be free once, free every month, or paid.
- Soft check. Whether checking leaves your score untouched. Checking your own score should always be a soft enquiry.
- Report depth. A number alone, or the full report with every account, payment and enquiry.
- Privacy. What data the app asks for, why, and whether it explains its use.
Information here is from each route's public material as of October 2026. Features change, so confirm on the app or site before you sign up. For step-by-step instructions on each route, see our free credit score check guide.
CIBIL Score App or Bureau Website? The Four Routes Compared
| Official bureau website | Your bank's app | Fintech credit score app | GroScore | |
|---|---|---|---|---|
| Data source | That bureau | Varies by bank | Varies by app; check its disclosure | Equifax |
| Cost | One free full report a year; some sell paid plans | Usually free to customers | Usually free | Free |
| Soft check | Yes | Yes for your own check | Should be; confirm | Yes |
| Report depth | Full report | Often score only | Varies | Full report, tracked monthly |
| Who it suits | Anyone who needs a specific bureau's score | Existing customers wanting a quick look | People comparing offers | People who want to fix their score step by step |
A few notes on each route.
Official bureau websites. This is the only route that guarantees you're seeing a specific bureau's score. Under the RBI's credit information rules (2025), each bureau must give you one free full credit report, with your score, every calendar year. Some bureaus also sell paid plans with more frequent updates. If a lender has asked for your CIBIL score specifically, go to CIBIL.
Your bank's app. Some banks show a credit score inside their app or net banking. It's convenient if you already bank there. Check which bureau it comes from, and whether you can see the full report or only the number.
Fintech credit score apps. Several free apps show your score and recommend loans or cards. Many are free because they earn when you take a product through them. That isn't a problem in itself, but you should know it. Look for the bureau name on the score screen.
GroScore. Free, with a soft check, and it shows the full Equifax report. It doesn't show a CIBIL score, which is its clearest limit. If you need the CIBIL number, use CIBIL's site alongside it.
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender, and the score it shows is your Equifax score, not a CIBIL score.
Do Credit Score Apps Show the Real CIBIL Score?
Only if they get it from TransUnion CIBIL. Many people call every credit score a "CIBIL score", and some apps lean on that habit. The score on your screen is real, but it may come from Equifax, Experian or CRIF.
The bureau matters for two reasons. Your four scores are usually close but rarely identical, because each bureau holds its own data and uses its own model. Also, a lender may pull any of the four. Timing adds to the gap, since each bureau refreshes on its own credit score update time.
Report depth matters as much as the bureau. GroScore says about 1 in 5 credit reports carries an error, roughly 20% (groscore.in, retrieved 2026-10-05), and a score-only screen won't show you which entry is wrong.
So before you trust a number, find the bureau name. A good app shows it on the score screen and in its FAQ. GroScore states plainly that its score comes from Equifax. You'll find all four bureaus on the RBI's list of credit information companies.
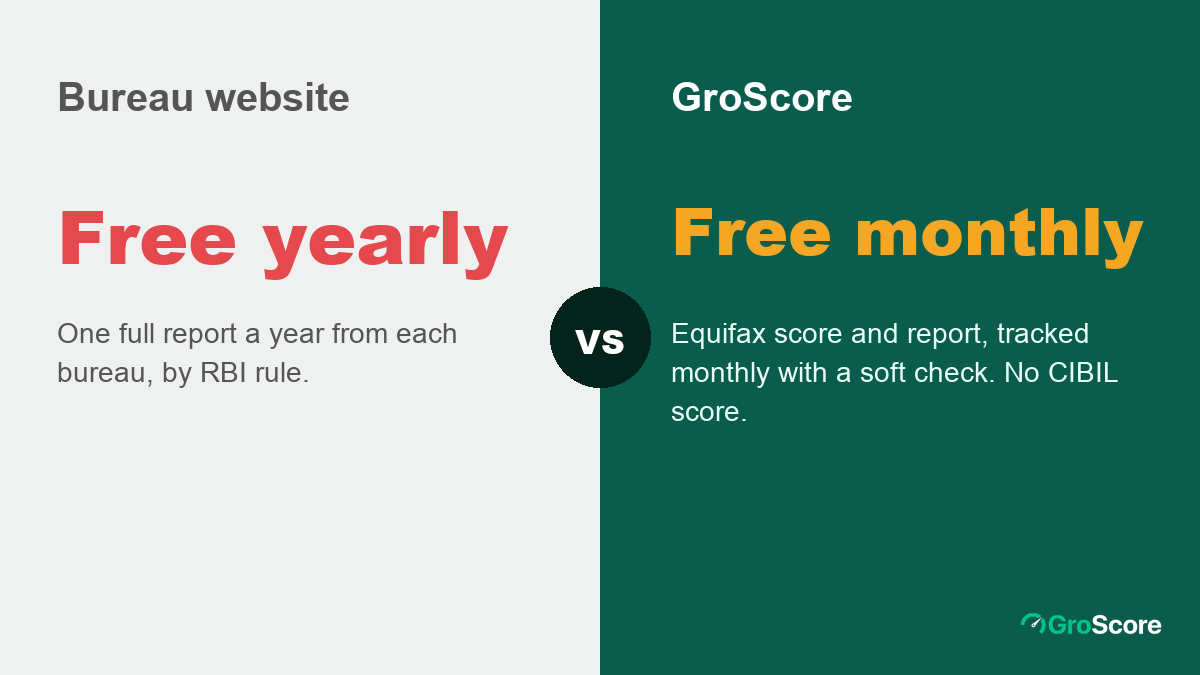
Different jobs: the bureau's yearly report, or a free monthly tracker.
Are Credit Score Apps Safe?
Most are, if you pick carefully. To show your score, any app needs your consent to fetch your report, plus details like your name, PAN and mobile number. That's normal. If you'd rather skip the app, our guide to a free CIBIL score check online by PAN number walks through the bureau route. What isn't normal is an app that asks for far more than it needs.
Run through these before you sign up:
- It names its bureau. If you can't tell where the score comes from, move on.
- It says the check is soft. Your own check should never lower your score.
- It explains why it needs your PAN and mobile number, and links a privacy policy you can read.
- It doesn't demand permissions it has no use for, like your contacts or photo gallery.
- It never charges to "fix" or "remove" entries. Accurate late payments can't be removed early by anyone. Only genuine errors can be disputed with the bureau.
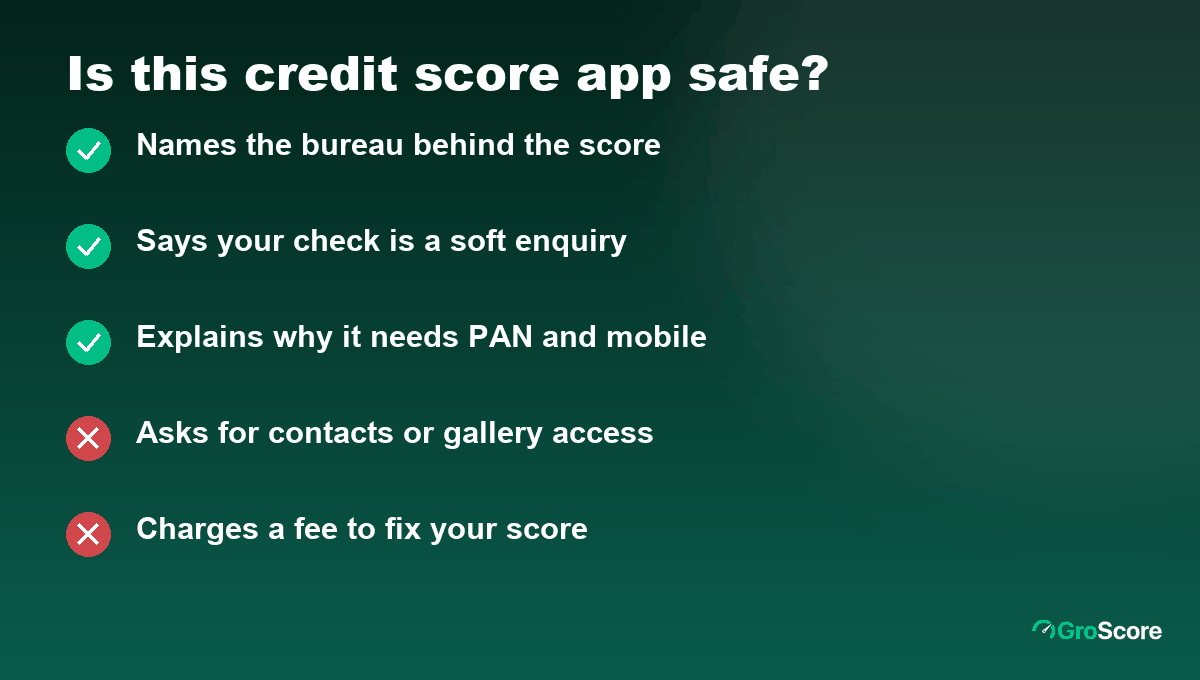
Five checks before you share your PAN with any app.
Never share an OTP with someone who calls you about your score. A genuine app doesn't need it over the phone.
Can a Credit Score App Increase Your Score?
No app can raise your score directly. Your score moves when your report changes: when you pay on time, lower your card balances, space out applications, or get a genuine error corrected.
A good app can show you what to fix, and in what order. GroScore says its coaching draws on 1 lakh+ analysed credit reports (groscore.in). It ranks the fixes for your profile and shows the points each one can gain you (groscore.in). It also alerts you to a new enquiry, a report error, an overdue payment or possible fraud. The work is still yours, and results depend on what's on your report. Nobody can promise a number of points or a date.
The app shows the path. Your payments move the score.
What Should You Do After an App Shows Your Score?
Here's an illustrative example. Kavya, 26, checks her score on an app and sees 688. She doesn't know what to do with it. Arjun, GroScore's credit coach, reads her report and flags three things, in this order:
- Card use of 58% on her only card (an indicative figure for this example). GroScore suggests keeping card use under 30% (groscore.in, retrieved 2026-10-05). Paying the balance down before the statement date is the quickest fix she controls.
- Two enquiries in the past month from loan apps she only "checked". If the app ran a hard enquiry, it shows on her report. She should stop applying for now.
- A closed loan still showing a balance. If she has the closure letter, this is a possible error, and she can dispute it with the bureau herself, free. There's no need to pay one of the CIBIL score improvement agencies for it.
The point isn't the number. It's the report behind it, and knowing which item to deal with first.
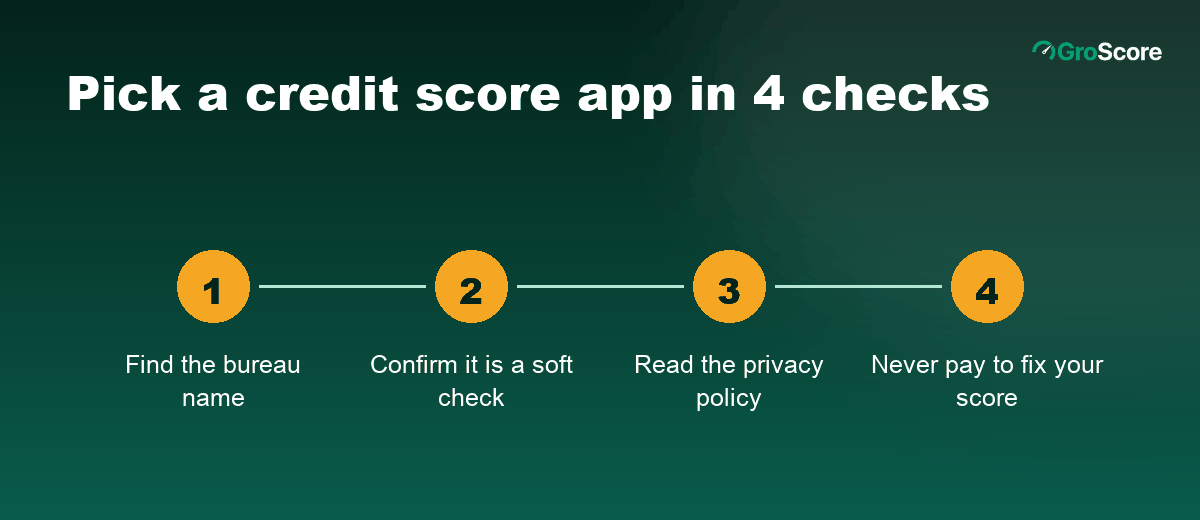
A one-minute check before you install anything.
Which Credit Score App Works in Hindi?
Language support varies, and it changes often, so check the app's own listing. GroScore explains your report and what to fix in Hindi or English (groscore.in). The bureau websites mostly work in English.
If you'd rather keep a copy of your report to read at your own pace, see our guide to getting a free credit report PDF.
So, Which Is the Best App to Check CIBIL Score Free?
The answer depends on the job:
- You need the CIBIL score itself, for a loan application that asks for it: use TransUnion CIBIL's official site. Your free annual report is there.
- You want a free score you can track and act on every month: use a credit score app that names its bureau. GroScore does this with your Equifax score and full report.
- You want all four views: take each bureau's free annual report, spread across the year.
Whatever you pick, look at the report, not just the number. That's where the fixes are.
Frequently Asked Questions
Which app is best to check CIBIL score for free?
For the CIBIL score itself, TransUnion CIBIL's official site is the source, and it gives you one free full report a year under RBI rules. For free monthly tracking, pick a credit score app that names its bureau and uses a soft check. GroScore shows your Equifax score, not CIBIL.
Are credit score apps safe?
Most are, if the app names its bureau, confirms a soft check, explains why it needs your PAN and mobile number, and has a clear privacy policy. Avoid any app that asks for needless phone permissions or charges to remove entries from your report.
Do credit score apps show the real CIBIL score?
Only apps that get your score from TransUnion CIBIL show a CIBIL score. Many show a score from Equifax, Experian or CRIF instead. Those scores are real too, just from a different bureau, so check the bureau name on the score screen.
Can an app increase my credit score?
No. Your score changes only when your report changes, through on-time payments, lower card use, fewer applications or a corrected error. An app can show you which of those to work on first.
Which credit score app works in Hindi?
GroScore explains your Equifax report and what to fix in Hindi or English. For other apps, check the language options on their store listing, since features change often.
The Bottom Line
Pick the route that matches the job. Use the bureau's own site when you need that bureau's score, and a free credit score app when you want to track your score and fix it month by month. Whichever you choose, check the bureau name, the soft check and the privacy policy before you share your PAN. If an app asks for money to clean up your report, close it. Before you trust one that promises points, read whether a credit score improver can really raise your score.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
