CIBIL Report Download: Get Your Credit Report PDF Free
One free report a year from each bureau, a PDF password that trips everyone up, and what to check first.

For a free CIBIL report download, sign in to cibil.com, claim your free annual report, open it on the myCIBIL dashboard and save it as a PDF. You get one free full report a year from CIBIL. Equifax, Experian and CRIF High Mark each give one more, so four free reports a year in all.
Key TakeawaysEvery RBI-registered credit bureau must give you one free full credit report, with your score, each calendar year (RBI).There are four such bureaus: TransUnion CIBIL, Equifax, Experian and CRIF High Mark (RBI list of CICs).Downloading your own report is a soft enquiry. It doesn't affect your score (groscore.in).Your report PDF carries your PAN, date of birth and addresses. Store it like a passport copy.
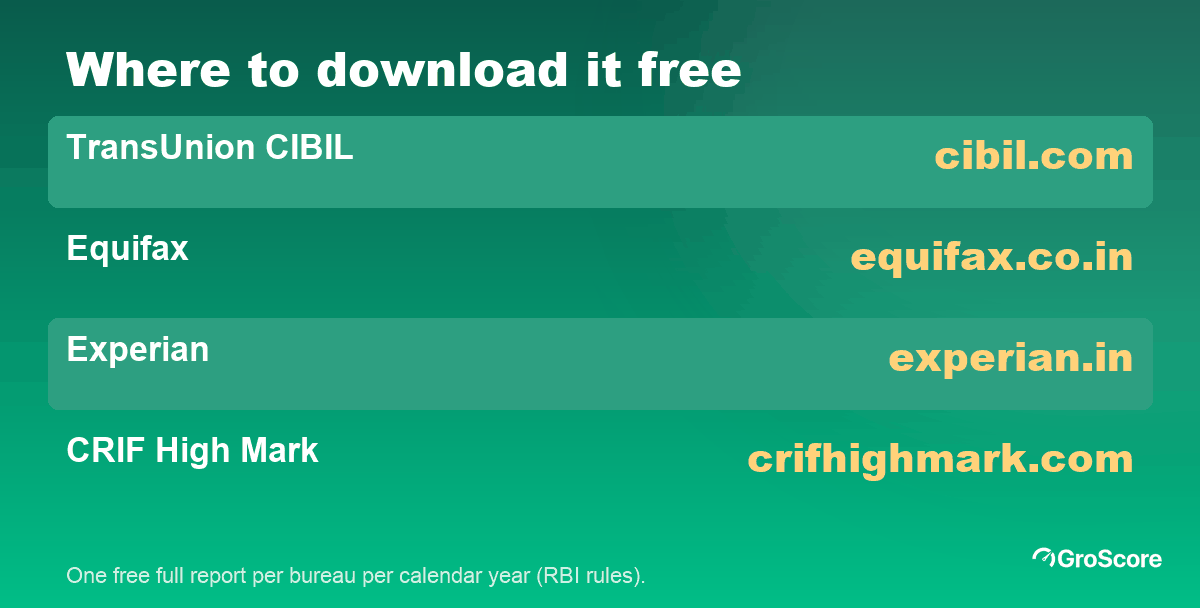
One free credit report download per bureau, every calendar year.
How Does a Free CIBIL Report Download Work?
Start on the official site. Your full CIBIL report lives only with TransUnion CIBIL, at cibil.com. If you haven't signed up yet, our CIBIL score check guide walks through registration and the OTP step.
Once you're registered, the download itself is short. As of October 2026, it goes like this:
- Sign in to your myCIBIL account with your email or username and the OTP.
- Claim the free annual report. Skip the paid plans offered first.
- Open the full report from your dashboard, not just the score.
- Use the download or print option and save it as a PDF.
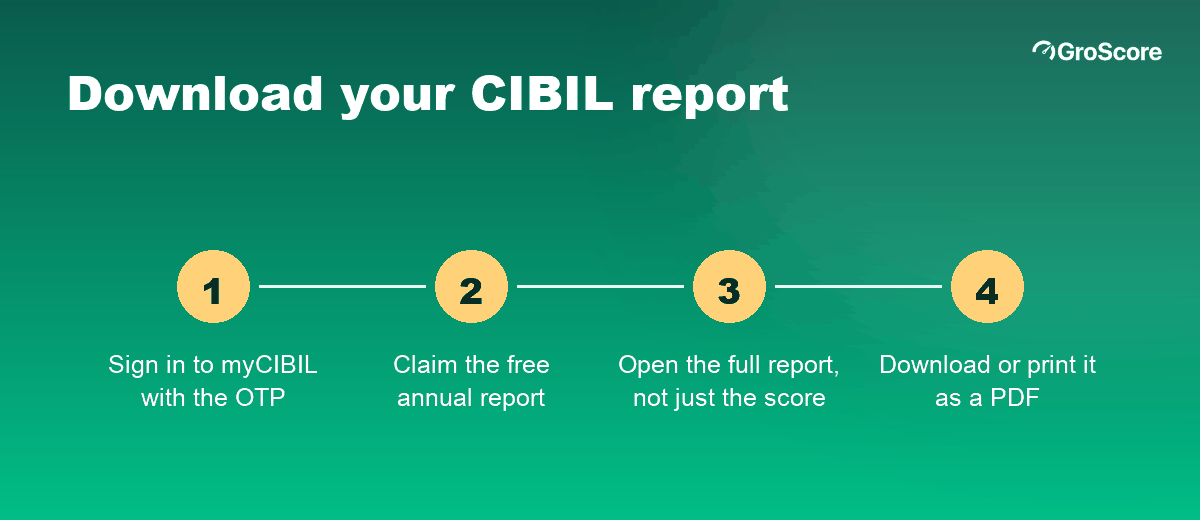
Open the full report, not only the score, before you save.
Two snags catch people. First, the free report resets each calendar year. If you claimed it in March, your next free one comes on 1 January. Second, a CIBIL score download isn't the report. You want the pages with your accounts and enquiries, because that's where problems hide. If all you need is the number, you can check your CIBIL score free online by PAN number.
Free Credit Report Download From Every Bureau
CIBIL is one source. Three more give you a free report, and a lender may check any of them. India's four credit information companies are listed on the RBI's register of credit information companies.
| Bureau | Free report | Website |
|---|---|---|
| TransUnion CIBIL | 1 per calendar year | cibil.com |
| Equifax | 1 per calendar year | equifax.co.in |
| Experian | 1 per calendar year | experian.in |
| CRIF High Mark | 1 per calendar year | crifhighmark.com |
Every bureau follows the same basic routine. You fill in your name, PAN, date of birth and mobile number, verify an OTP, and the report opens online or arrives by email. Screens differ, and they change, so follow each site's prompts rather than a screenshot from two years ago. Our guide to the Experian credit score shows that bureau's version step by step.
Why bother with all four? Not every lender reports to every bureau. A card from one bank might sit in your Experian file and be missing from CIBIL. Downloading more than one report is how you catch that.
Equifax deserves a word here. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. Its report is your Equifax report, not your CIBIL report, and you can read it in the app any month. More on that bureau in our guide to your Equifax credit score.
Is a free CIBIL report really free?
Yes, once a year. The RBI's credit information rules (2025) requires each bureau to give you one free full credit report, score included, every calendar year. You don't need a subscription, and you shouldn't pay an agent for it.
Paid plans exist for people who want monthly refreshes or alerts. That's a choice, not a requirement.
A paid plan is optional. Your annual report isn't paywalled.
Anyone charging you for "the official free CIBIL report PDF" is selling what the RBI already gave you.
What Is the Password for the CIBIL Report PDF?
There's no single universal password, which is why so many people who download a CIBIL report PDF get stuck here. Credit report PDFs are often locked because they hold your PAN and date of birth, and the format depends on the bureau and how the file reached you.
Common patterns include your date of birth written as DDMMYYYY, or part of your name with your birth year. Don't guess endlessly. The email or download screen that gave you the file says what the password is. Read that first.
Still locked out? Request the report again from the bureau's own site. Never upload the PDF to a random "PDF unlocker" website. You'd be handing your PAN, addresses and loan history to a stranger's server.
What to Check First in Your Downloaded Report
A report download is only useful if you read it. Bureau layouts differ, but every report carries the same blocks: your personal details, contact details, every account, and every enquiry. For a section-by-section walkthrough, see credit report explained.
Here's an illustrative example. Kavya, 27, downloads her report before applying for a two-wheeler loan. She sends it to Arjun, GroScore's credit coach, who reads one account row with her:
| Field | What her report shows | What it means |
|---|---|---|
| Account type | Credit card, XXXX4821 | Her only card |
| Ownership | Individual | She alone is liable |
| Current balance | Rs 54,000 on a Rs 75,000 limit | 72% of the limit in use |
| Payment history (DPD) | 000 000 030 000 | Paid 30 days late once |
| Enquiries | 3 in the last 60 days | Three lenders checked her |
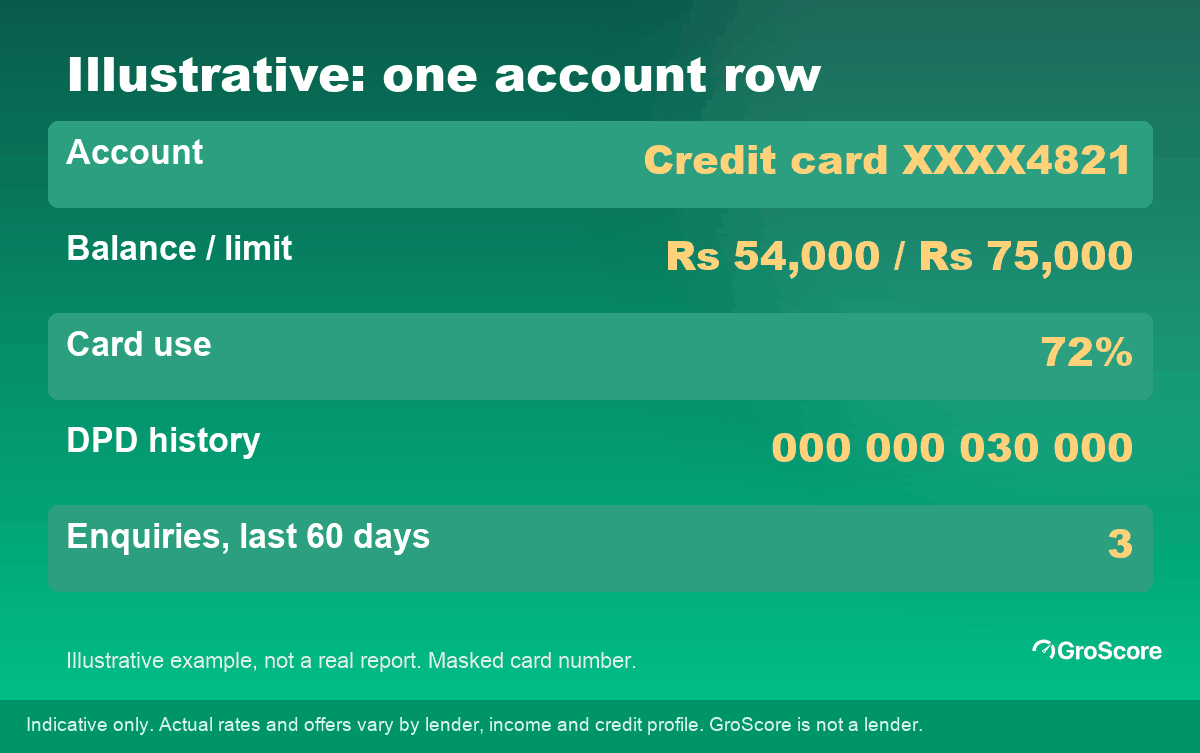
Illustrative: one account row, read the way a coach reads it.
DPD means days past due. A "000" is a month paid on time. A "030" means a payment ran 30 days late. The arithmetic on her card is simple too: Rs 54,000 divided by Rs 75,000 is 72%.
Arjun flags three things, in this order:
- Card use at 72%. GroScore advises keeping it under 30% of the limit (groscore.in, retrieved 2026-10-05). Paying it down before the next statement is the one fix she can make this month.
- Three enquiries in two months. Each loan application triggers a hard enquiry. She holds off on new applications until she's ready to borrow.
- The 30-day late payment. It's accurate, so nobody can remove it early. It fades as on-time months pile up.
No promise of a number comes with this. What moves her score depends on what lenders report next.
If a row in your own report is wrong, like a loan you never took, that's different. Errors can be disputed with the bureau. GroScore says about 1 in 5 reports, or 20%, carries an error (groscore.in, retrieved 2026-10-05). Under RBI rules, you are entitled to Rs 100 a day in compensation if a bureau takes more than 30 days to resolve your complaint.
How Should You Store and Share Your Credit Report PDF?
Treat the file like a passport scan. It lists your PAN, date of birth, phone numbers, past addresses and every loan in your name.
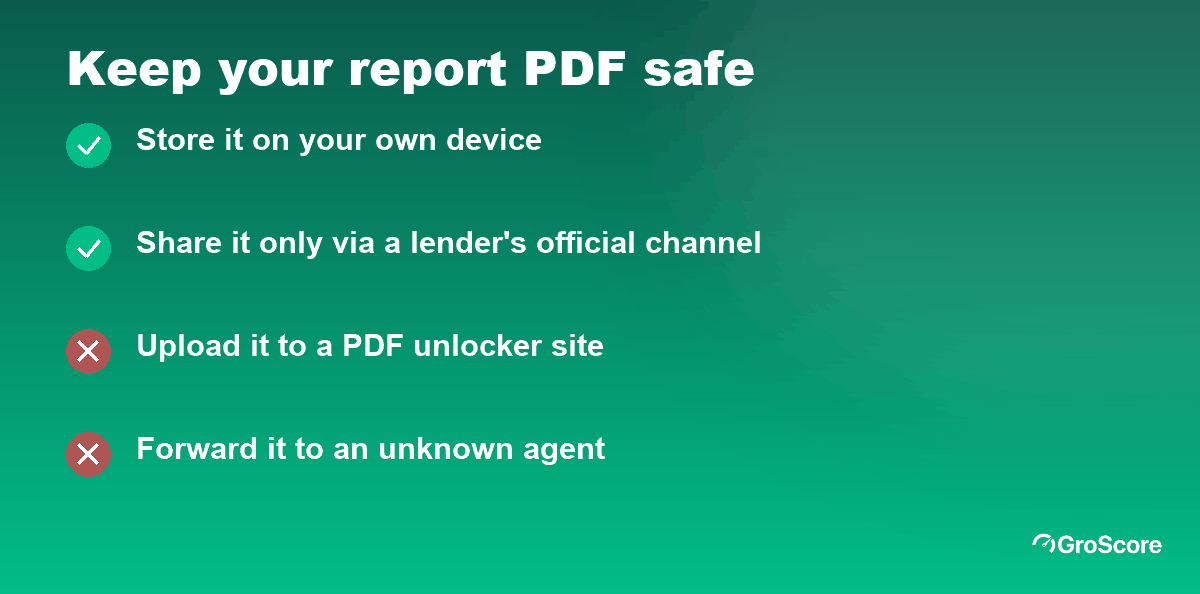
Your report is an identity document in disguise.
Some plain habits help:
- Keep it on your own phone or laptop, not in a shared folder.
- Share it with a lender only through their official app, branch or email.
- Delete old copies you don't need.
Watch for one scam in particular. Someone calls, claims to be from "CIBIL" or a bank, and asks you to forward your report or read out an OTP so they can "fix" your score. Bureaus don't call to repair scores. Hang up.
Is My Downloaded Report the Same One Banks See?
Mostly, yes. The data comes from the same file: your accounts, payment history and enquiries. Lenders get a version formatted for credit decisions, and they may pull it on a different day, so a recent payment may show in one and not yet in the other.
Two more things differ. A bank may check a bureau other than CIBIL. And it reads your report next to your income, job and existing EMIs, which the report doesn't contain. So a clean report helps, but it's one input among several.
Want to track your report monthly instead of once a year? Compare the options in our guide to the best credit score app in India, free ones included.
Frequently Asked Questions
How can I download my CIBIL report for free?
Register or sign in at cibil.com, verify the OTP and claim the free annual report instead of a paid plan. Open the full report on your dashboard and save it as a PDF. You get one free report each calendar year.
What is the password for the CIBIL report PDF?
There's no single universal format. Your date of birth as DDMMYYYY, or part of your name with your birth year, are common. The email or download screen that gave you the file tells you which, so check that before guessing.
How many free credit reports can I get in a year?
Four. Each of the four RBI-registered bureaus, CIBIL, Equifax, Experian and CRIF High Mark, must give you one free full report per calendar year. Spacing them out gives you a fresh look every few months.
Can I download my Equifax report free?
Yes. Equifax gives one free full report a year through equifax.co.in. GroScore also shows your full Equifax report in the app, free and with a soft check, so you can read it any month.
Is the downloaded report the same one banks see?
The data is the same: accounts, payment history and enquiries. Lenders see a version built for credit decisions, may pull it on a different date, and may use a different bureau. They also weigh your income and existing EMIs.
Disclaimer
This article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
