CIBIL Score Improvement Agency: Do Credit Repair Services Work?
What a paid credit repair service can really change on your report, what it can't, and the free route most people never hear about.

A CIBIL score improvement agency can't do anything you can't do yourself for free. No agency can delete an accurate late payment, default or settlement from your credit report. An agency can dispute a genuine error for you, but you can raise that dispute directly with the bureau at no cost. Pay for advice if you want it. Never pay for a promise.
Key TakeawaysNobody can remove accurate negative entries early. Only genuine errors can be corrected.A bureau dispute is free and must be resolved within 30 days, or you're owed Rs 100 a day (RBI).The RBI registers four credit bureaus. It doesn't license "credit repair".GroScore says about 1 in 5 credit reports carries an error (groscore.in).
Accurate history stays. Only errors can be corrected.
What Does a Credit Repair Agency Actually Do?
Strip away the ads and most credit score improvement services do three things. They read your credit report. They raise disputes with the bureau or lender for you. And they give general advice: pay on time, use less of your card limit, stop applying for new loans.
None of that is illegal. None of it needs an agency, either.
You'll see the same business under many names: CIBIL score repair agency, improve CIBIL score agency, credit fixing company. The pitch is usually "we'll clean your report and raise your score". That's where honest help and a scam part ways. Explaining your report is a service. Promising to remove a default is a lie.
Your credit report is the record of every loan and card in your name, as your lenders report it. Your score is calculated from it. Only two things change a report: your lender sends new data, or a bureau corrects an error. Both routes are open to you directly. For the full list of fixes in order, read how to improve your CIBIL score step by step.
Is a CIBIL score improvement agency legal?
A consultancy that helps people read reports and file disputes isn't banned. But there's no RBI licence for credit repair. The RBI's list of credit information companies names four bureaus: TransUnion CIBIL, Equifax, Experian and CRIF High Mark. An agency isn't one of them and has no power to change their data. If something goes wrong, you have far fewer places to complain than you would against a bank.
Why No Agency Can Delete an Accurate Default
If the default really happened, it stays. Your lender reported it, and the bureau stores what lenders report. The Credit Information Companies (Regulation) Act, 2005 gives you the right to have inaccurate data corrected. It gives nobody the right to delete accurate data.
Here's how that plays out for the entries agencies most often claim to "fix":
| Entry on your report | True or false? | What actually happens |
|---|---|---|
| A loan you never took | False | Dispute it free with the bureau |
| A closed loan shown as active | False | Dispute it with your no-dues letter |
| A late payment that happened | True | It stays and fades as on-time months build up |
| A "settled" or "written-off" loan | True | It stays; paying the balance can update the status |
| A default you really made | True | It stays; nobody can delete it early |
Some agencies dispute true entries anyway, hoping the lender won't reply in time. It rarely works. The bureau asks the lender, the lender confirms the data, and the entry stays. You've paid for a month of waiting.
How Do You Fix a Credit Score Yourself, for Free?
Follow the same steps a legitimate agency would. None of them costs a rupee.
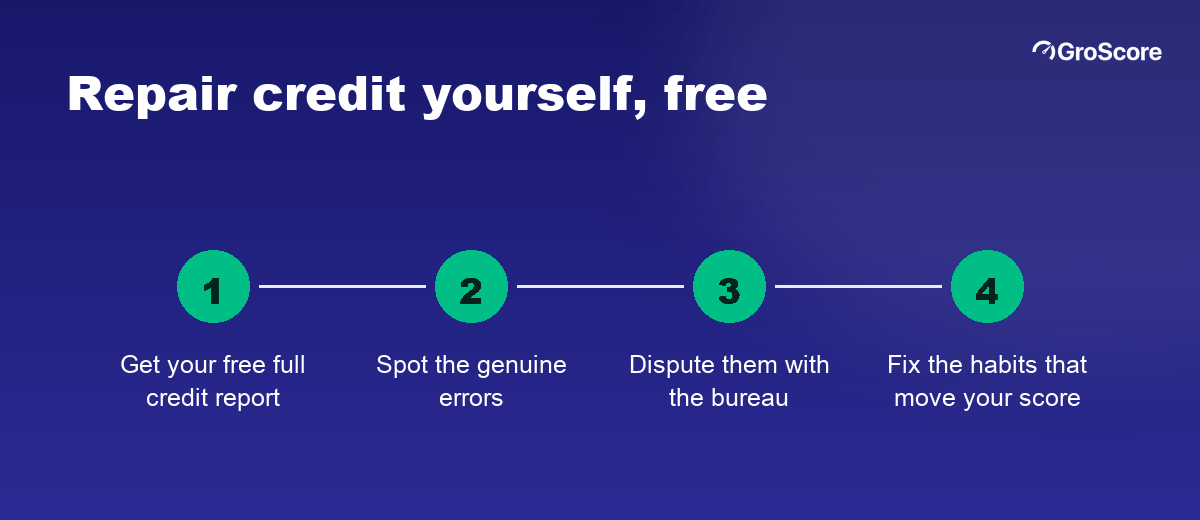
These are the steps an agency would follow, minus the fee.
- Get your full report. Every bureau must give you one free full credit report, with your score, each calendar year. Free apps also show a report with a soft check that never lowers your score.
- Find the genuine errors. Look for accounts you don't recognise, closed loans still shown as open, wrong late marks and wrong personal details.
- Raise a dispute with the bureau. Each bureau runs a free online process. Attach proof, such as a closure letter or bank statement. Our guide on how to raise a CIBIL dispute covers each bureau's route.
- Fix the habits that move the score. Clear overdues, pay on time, keep card use under 30% of your limit and pause new applications.
The rules favour you. Under the RBI's credit information rules (2025), a complaint about wrong credit data must be resolved within 30 calendar days, or you're owed Rs 100 for every day of delay. A lender that rejects your correction must tell you why. And after a correction, the bureau sends a free corrected report to anyone who pulled yours in the previous six months (RBI).
An agency can't speed any of this up. Lenders and bureaus work to the same 30-day clock whoever files.
Red Flags of a Credit Repair Scam
Fixing a credit score is slow, honest work. Scams sell speed. Walk away if a service does any of these:
- It promises a number. "We'll take you from 580 to 750." Nobody controls what lenders report.
- It promises to delete a default, settlement or write-off. Accurate entries stay.
- It asks for a large fee upfront, before any work, for "guaranteed" results.
- It asks for your OTP, UPI PIN, net-banking password or bureau login. Nobody needs these to help you.
- It tells you to dispute everything, including entries you know are true.
- It claims a "special contact" at CIBIL or a bank. Bureaus don't sell back-door edits.
Some "repair" offers end in a loan pitch from an app you can't verify. Before you borrow from anyone, check that the lender is a bank or appears on the RBI's list of registered NBFCs at rbi.org.in.
Already paid and got nothing? Ask for a refund in writing and keep every message. If you shared an OTP or banking details, call your bank straight away to block the account or card. You can report online fraud at cybercrime.gov.in or on the 1930 helpline.
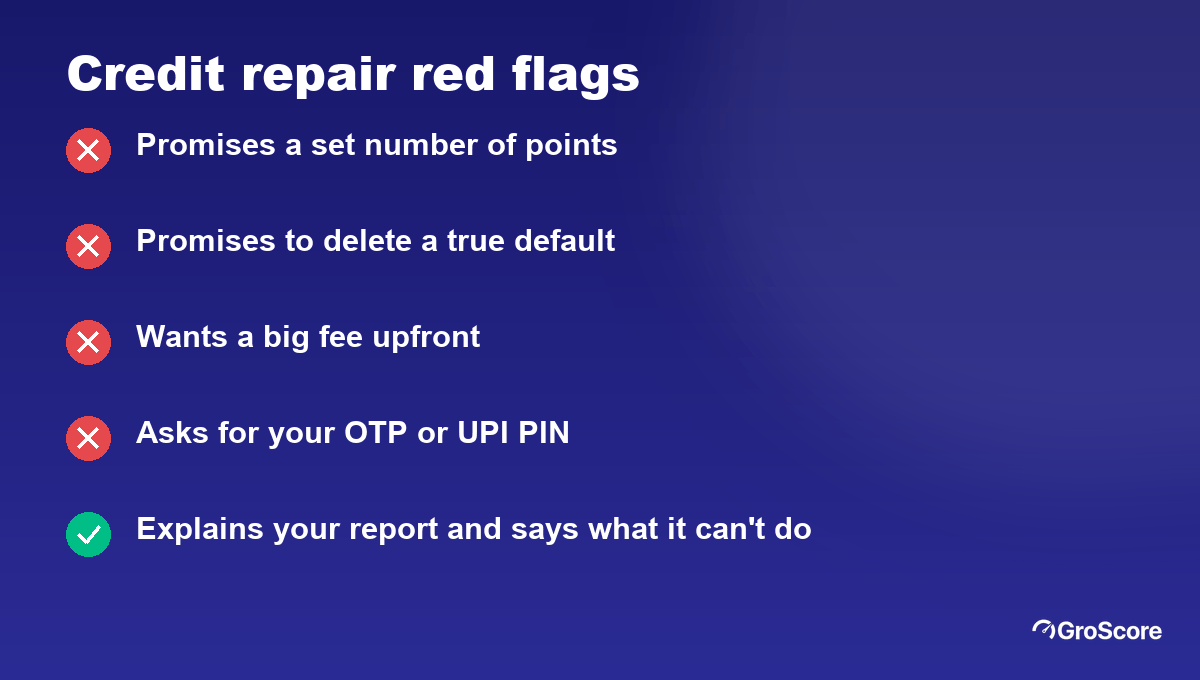
Any one of these is enough to say no.
What Would a Credit Coach Flag Before You Pay Anyone?
Here's an illustrative example, not a real customer. Kiran, 33, has an Equifax score of 641, and an agency has offered to "clean his report". Before he pays, Arjun, GroScore's credit coach, sorts every item on the report by who can fix it.
- A personal loan Kiran never took. It's an error, and possibly fraud. He disputes it with the bureau and writes to the lender.
- A card he closed in 2025, still showing Rs 12,000 due. That's also an error. He disputes it and attaches the closure letter.
- A DPD of 60 on a two-wheeler loan last year. DPD means days past due. He did pay late, so it stays and fades with clean months.
- High card use. His only open card has a Rs 50,000 limit and a Rs 39,000 balance, which works out to 78%. No agency can change that. Only Kiran can.
The arithmetic on item 4 works out simply. To get under GroScore's suggested 30%, his balance must fall to Rs 15,000, so he pays down Rs 24,000 (groscore.in, retrieved 2026-10-05). At Rs 8,000 a month, that takes about three months, ignoring interest. Our guide on how to improve your credit score fast shows what else can realistically change in 30 to 90 days.
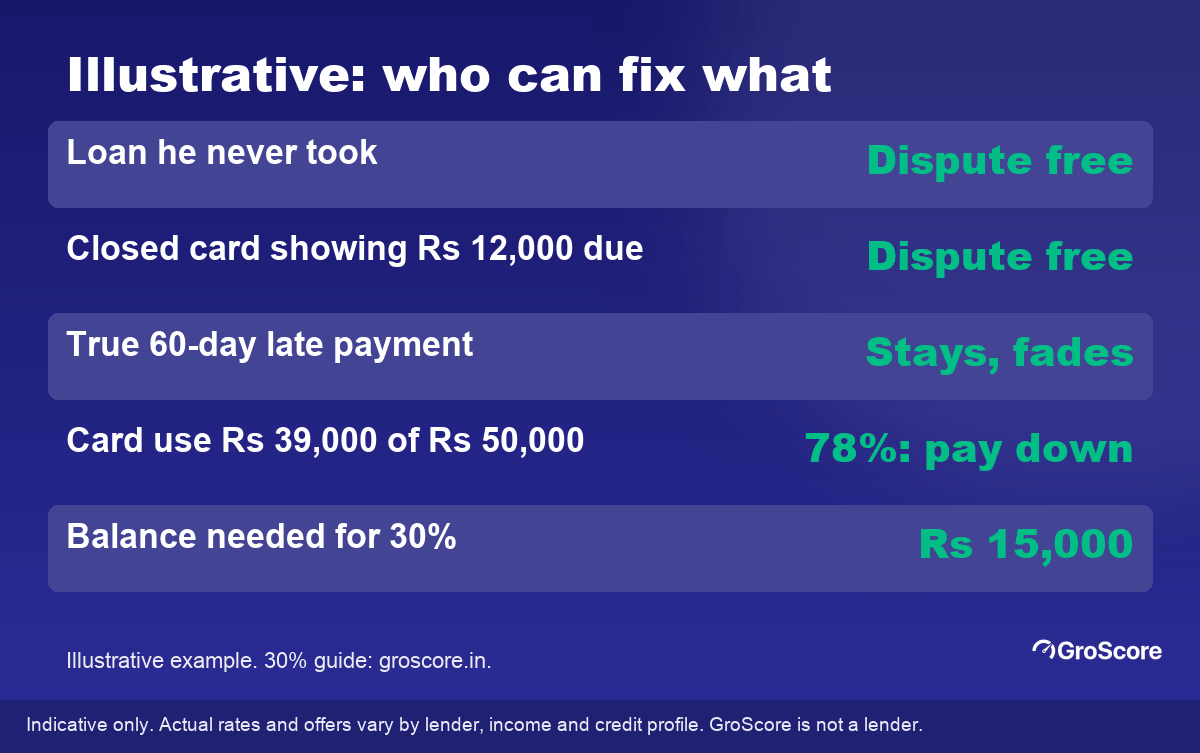
Illustrative example: four items, and none of them needs a paid agency.
Two items are disputes he can file free. One is history only time fixes. One is a habit only he can change. An agency would have charged him for the first two and promised him the third.
Credit Coach vs Repair Agency: What's the Difference?
A credit coach explains your report and ranks what to fix. You raise the disputes and change the habits. A repair agency offers to do some of that for a fee, and the risky ones promise results nobody can guarantee. We compare the two in more depth in our piece on whether a credit score improver can help.
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender, and the score it shows is your Equifax score, not a CIBIL score.
On a page about CIBIL, that distinction matters. TransUnion CIBIL is one of the four RBI-registered bureaus, and each calculates its own score. GroScore can help you spot an error on your Equifax report and show you how to dispute it. It can't change any bureau's data or remove an accurate entry.
The same report gets very different promises.
Do You Need a CIBIL Score Improvement Agency at All?
You rarely do. If your debts are more than you can handle, you need help with the debt, not the score. Talk to your lender before you miss a payment and ask about a revised EMI or restructuring. Your bank can tell you whether it offers free credit counselling. A chartered accountant can help you plan repayments, and charges for time, not promised points.
Comparing tools rather than services? Our roundup of the best credit score app options covers the free ones. Pick one that names its bureau and says plainly what it can't do.
Frequently Asked Questions
Can a credit repair agency delete my loan default?
No. If the default is accurate, it stays on your report, and no agency, app or bureau contact can remove it early. Only genuine errors can be corrected, and you can dispute those yourself for free.
Are CIBIL improvement agencies legal?
A service that explains reports and files disputes isn't illegal, but the RBI doesn't license credit repair. Any agency promising to delete true entries or guaranteeing points is making claims it can't keep.
How much do credit repair services charge?
There's no standard or regulated fee, and charges vary widely. Whatever the price, a bureau dispute itself costs nothing, and the RBI's 30-day timeline applies whether you file it or an agency does.
Can I repair my credit score myself for free?
Yes. Get your free report, dispute genuine errors with the bureau, clear overdues and keep card use low. That's the same work an agency does, and repairing a credit score this way costs nothing but time.
What is the difference between a credit coach and a repair agency?
A credit coach explains your report and ranks the fixes, and you act on them, usually free. A repair agency offers to act for you for a fee. Neither can remove accurate entries, so the coach route keeps the money in your pocket.
The Bottom Line
Credit repair isn't a product. It's a short list of jobs: find the errors, dispute them free, stop the damage and let clean months build up. An agency can do the paperwork, but it can't do the part that moves your score most, which is how you pay from here on. Check your report, fix what's false, and keep your money for your EMIs.
Disclaimer
This article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
