Instant Gold Loan: The Easiest Loan With a Low CIBIL Score?
Your gold, not your score, does most of the work. Here's how much you can borrow, what it costs, and what happens if repayment goes wrong.

Often, yes. An instant gold loan leans on your jewellery, not your credit history, so a low score is less of a barrier than for a personal loan. Under RBI rules in force since 1 April 2026, regulated lenders can lend up to 85% of your gold's value on loans up to ₹2.5 lakh. The catch is real, though. Miss repayments, and the lender can auction your gold.
Key TakeawaysGold is the security, so a low CIBIL score matters less. Many lenders still pull your credit report, and loans above ₹2.5 lakh need a fuller assessment of your repayment capacity (RBI).The RBI caps the loan at 85% of the gold's value up to ₹2.5 lakh, 80% up to ₹5 lakh and 75% above that (RBI).A gold loan is reported to the credit bureaus. Repaying on time can help rebuild your record; missing payments hurts it like any other loan.Borrow only from a bank or an RBI-registered NBFC, and read the auction terms before you pledge anything.
Before We Start: What GroScore Is and Isn't
Because this page discusses loans, here's a plain note. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. It doesn't give gold loans, value gold or hold collateral.
A word on "CIBIL" too. TransUnion CIBIL is one of four RBI-registered credit bureaus, alongside Equifax, Experian and CRIF High Mark. A gold loan lender may check any of them. The number GroScore shows is your Equifax score, not a CIBIL score.
If you're comparing every option open to you, start with our guide to a loan for a low CIBIL score. This page goes deep on one of them.
How Does an Instant Gold Loan Work?
You take gold jewellery or coins to a lender. It tests purity, weighs the gold and values only the gold content, not stones or fittings. It lends you a share of that value, keeps the gold safely, and returns it when you repay.
Why "instant"? With less to assess than a personal loan, a gold loan can be quick, sometimes same-day at a branch. Speed depends on the lender, the amount and your documents, so no timing is guaranteed. Expect to show KYC documents: identity and address proof, plus PAN.
RBI rules protect you during valuation. The lender must test the gold in your presence and explain deductions for stone weight and fastenings. It must also publish on its website how it values gold. The RBI also caps how much you can borrow against that value.
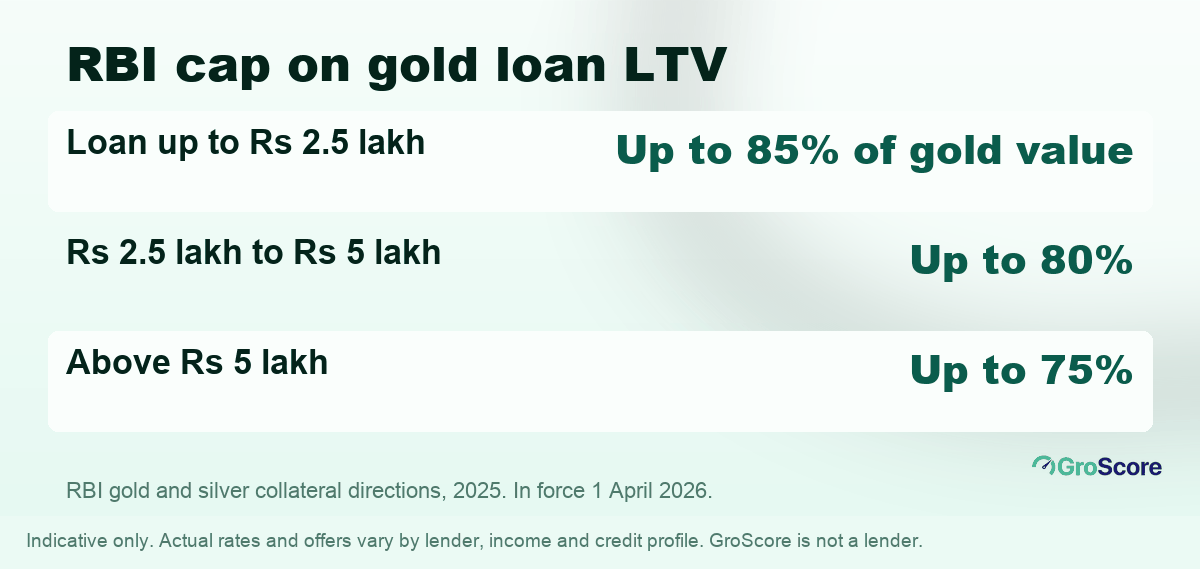
The RBI's ceilings. A lender may offer less.
You'll usually choose between two repayment styles:
- EMI loans, where you pay principal and interest every month.
- Bullet loans, where you pay interest and principal together at the end. The RBI caps bullet gold loans for personal use at 12 months, though they can be renewed after accrued interest is paid.
Do Gold Loans Check CIBIL?
Usually, yes. Most regulated lenders still pull at least one bureau report, but they weigh it lightly because the gold covers their risk. That's why a gold loan without CIBIL worries is realistic in a way an unsecured loan isn't.
The loan size matters too. The RBI's Lending Against Gold and Silver Collateral Directions, 2025 require a detailed credit assessment, including your repayment capacity, when your total gold loan is above ₹2.5 lakh. Above that line, expect questions about income and existing EMIs.
No regulated lender promises approval to everyone. An ad offering a loan with "no CIBIL check" and guaranteed approval is a myth, and often a scam. For a wider view of score cut-offs by loan type, see the CIBIL score needed for a loan.
How Much Can You Borrow Against Your Gold?
Your borrowing limit depends on the loan-to-value ratio, or LTV: the loan as a share of your gold's value. The RBI sets the ceiling, and it shrinks as the loan grows.
| Total gold loan per borrower | Maximum LTV |
|---|---|
| Up to ₹2.5 lakh | 85% |
| Above ₹2.5 lakh, up to ₹5 lakh | 80% |
| Above ₹5 lakh | 75% |
Source: RBI Lending Against Gold and Silver Collateral Directions, 2025, in force from 1 April 2026 (RBI). Lenders must keep the LTV within the cap for the whole loan.
Two details change the maths. On a bullet loan, the LTV counts the total amount repayable at maturity, interest included, not just what you take home. And because the cap applies throughout the loan, a sharp fall in gold prices can lead the lender to ask you to top up.
Here's an illustrative example of how the numbers work.
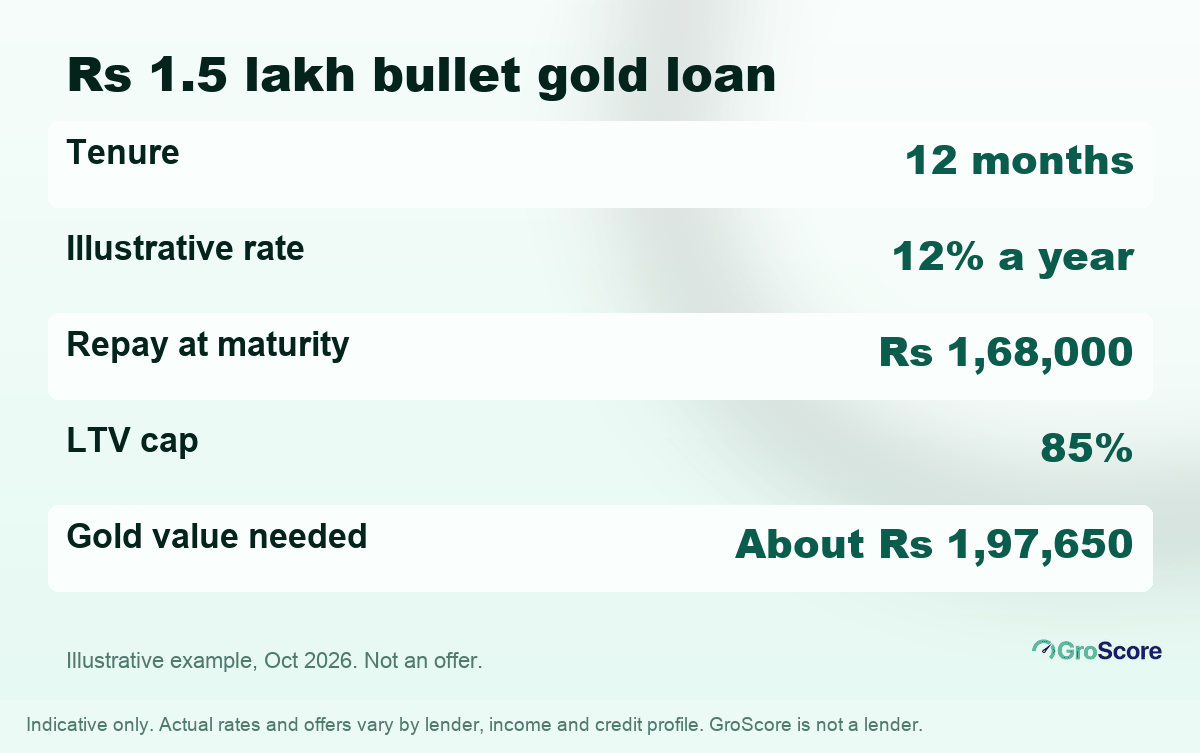
Illustrative example: interest is counted inside the LTV on a bullet loan.
For example, say you want ₹1,50,000 as a 12-month bullet loan at an illustrative 12% a year, with simple interest charged at maturity. The interest works out to ₹18,000, so ₹1,68,000 is due at the end. At the 85% cap, your gold needs to be valued at about ₹1,97,650 or more (₹1,68,000 divided by 0.85). These figures are illustrative, as of October 2026, and aren't offers. Actual offers vary by lender, income and credit profile.
What Does a Gold Loan Really Cost?
Gold loan interest is usually lower than what a low-score borrower pays on an unsecured loan, because the lender's risk is lower. At very low scores, unsecured offers thin out fast, as our guide to 300 credit score loans shows band by band. The rate isn't the whole cost. Look for processing fees, valuation or assaying charges, penal charges for late payment, and renewal charges.
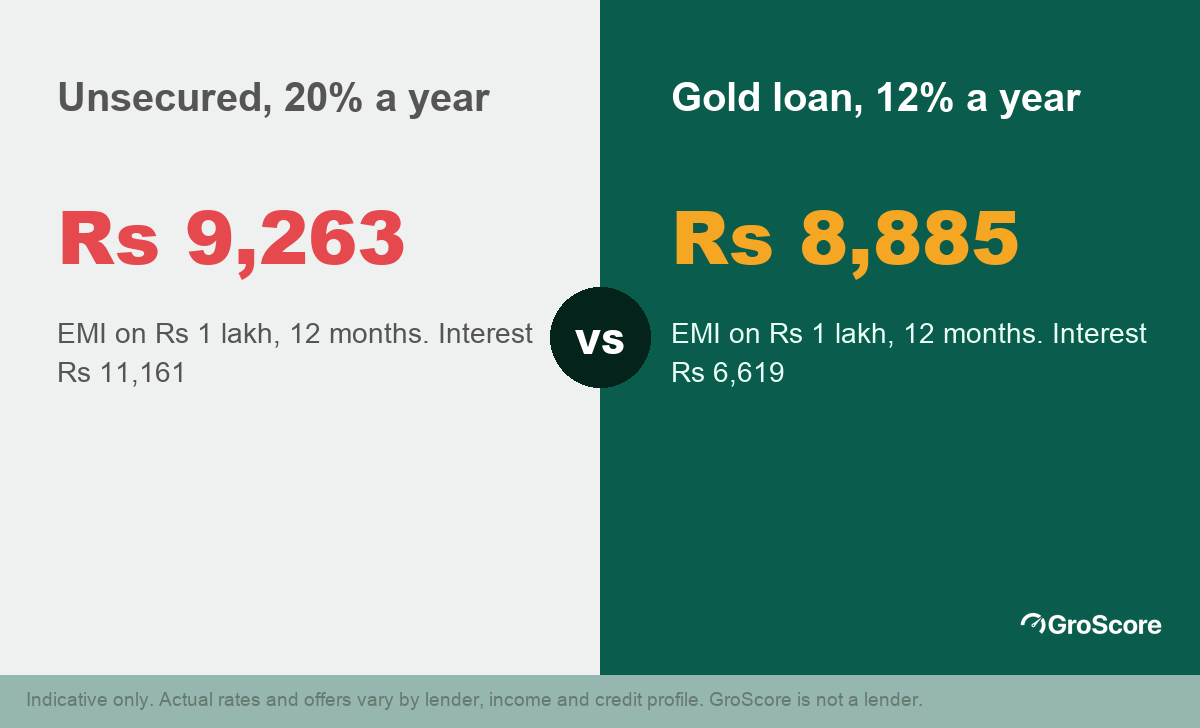
Illustrative example: a secured rate against an unsecured one.
For example, take ₹1,00,000 repaid over 12 months. At an illustrative 12% gold loan rate, the EMI works out to ₹8,885 and total interest to ₹6,619. At 20%, a rate an unsecured lender might charge a low-score borrower, the EMI is ₹9,263 and interest climbs to ₹11,161. The gap is ₹4,542 on a small loan. These are illustrative figures from the standard EMI formula as of October 2026, not offers.
| Gold loan | Unsecured loan with a low score | |
|---|---|---|
| Main security | Your gold | Your credit record and income |
| Weight on your score | Low | High |
| Illustrative EMI on ₹1 lakh, 12 months | ₹8,885 at 12% | ₹9,263 at 20% |
| If you can't repay | Gold can be auctioned | Collection calls and a damaged report |
Illustrative figures as of October 2026, not offers. Actual offers vary by lender, income and credit profile.
To compare lenders properly, ask for the Key Fact Statement. RBI rules require it before you sign, with the all-in annual percentage rate (APR) and every charge listed. If an app instead promises an instant loan without CIBIL checks and no collateral, check who the lender is before you share any documents.
What Happens If You Can't Repay a Gold Loan?
Read this part twice. If you default, the lender can sell your gold at auction. RBI rules set conditions on how it's done:
- Notice first. The lender must give you adequate notice to repay or settle before starting an auction.
- A floor price. The reserve price can't be less than 90% of the gold's current value, or 85% if two auctions fail.
- Full accounts. The lender must tell you what the auction fetched and which dues it adjusted.
- Your surplus back. Anything left over after dues must be refunded within seven working days of the lender receiving the auction proceeds. If the sale falls short, the lender can recover the shortfall from you.
The credit damage is separate. A missed gold loan payment shows as DPD (days past due) on your report, and an auction doesn't wipe that record.
Repay on time, and the protection runs the other way. The lender must return your gold within seven working days of full repayment. If the delay is its fault, it owes you ₹5,000 for each day beyond that (RBI).
Does Repaying a Gold Loan Improve Your Credit Score?
Yes, it can. Gold loans are credit accounts, so they're reported to the bureaus. On-time payments add positive history to a report that may badly need it. Results depend on what else is on your report and aren't guaranteed.
Here's an illustrative example. Say Farhan, 41, has an Equifax score of 582 and needs ₹1 lakh for six months. Arjun, GroScore's credit coach, reads his report with him and flags three things, in this order:
- A credit card at 90% of its limit (an indicative figure for this example). Paying it down is the quickest item he controls. GroScore's guidance is to keep card use under 30% of the limit (groscore.in, retrieved 2026-10-05).
- A personal loan written off three years ago. It's accurate, so nobody can remove it early. It fades as new on-time payments build up.
- The gold loan itself. An EMI version adds a payment to his record every month. He sets a reminder for each due date and borrows only the ₹1 lakh he needs.
Why the card first? Lenders have reported to bureaus every week since 1 July 2026 (RBI), so a lower balance can show up faster than it used to. The gold loan, repaid on time, then helps with the slower work. For the full plan, see how to improve your credit score.
GroScore can't lend to Farhan or value his gold. It ranks the fixes on his report and shows which lenders' criteria his profile clears across 100+ loans and cards from 60+ banks and NBFCs (groscore.in). The lender decides.
How to Pick a Safe Gold Loan Lender
Pledged gold may be irreplaceable, so check the lender first.
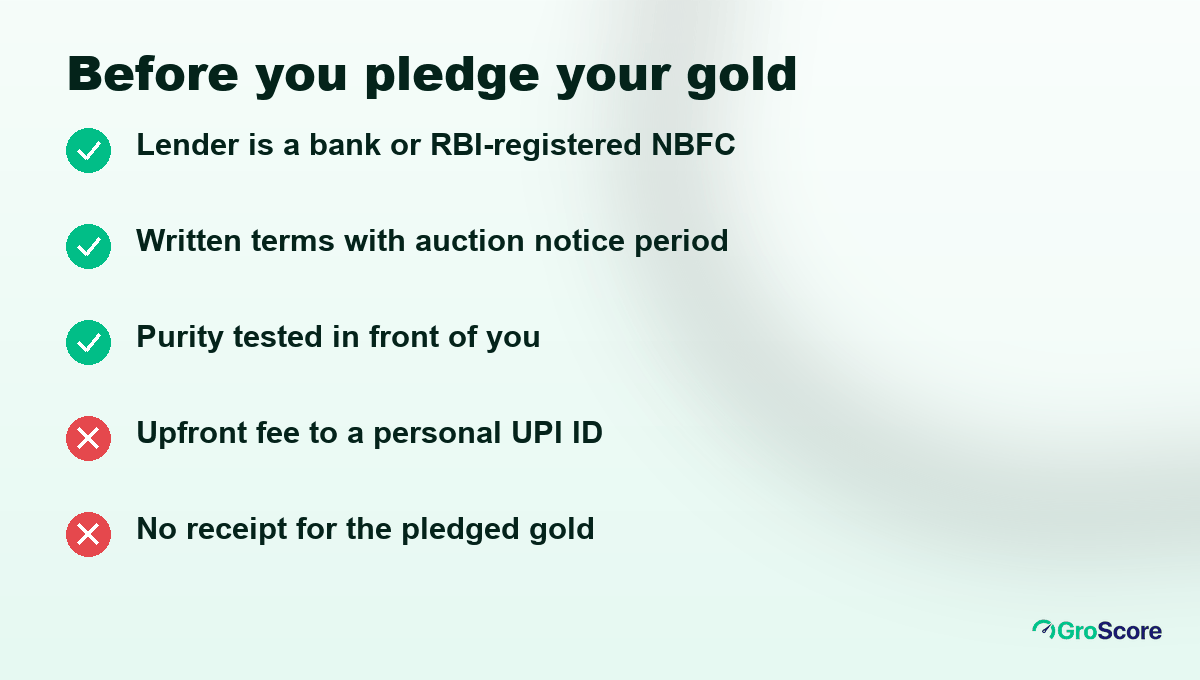
Any red cross is a reason to walk away.
- Verify the lender. A bank is easy to confirm. For an NBFC, search the RBI's list of registered NBFCs. Local pawnbrokers and moneylenders work under state laws, not RBI regulation, so the RBI's protections above may not apply to them.
- Get it in writing. The loan document should describe the gold, its value, the auction process and the notice period before any auction.
- Watch the valuation. Testing should happen in front of you, with deductions explained.
- Never pay upfront to a personal UPI ID. Regulated lenders list charges in the Key Fact Statement.
- Use a regulated app, if you go digital. Our guide to a loan app for a low CIBIL score shows how to check who actually lends.
Got a problem with a regulated lender? Complain to the lender first, then escalate to the RBI's Complaint Management System (cms.rbi.org.in). Report an unauthorised lender on the RBI's Sachet portal, and call 1930 for fraud.
Frequently Asked Questions
Do gold loans check CIBIL?
Most regulated lenders still check at least one credit bureau, but the gold is the main security, so a low score is far less of a barrier. Above ₹2.5 lakh in total, RBI rules require a fuller assessment of your repayment capacity.
How much can I borrow against my gold?
Up to 85% of the gold's value for loans up to ₹2.5 lakh, 80% for loans above ₹2.5 lakh up to ₹5 lakh, and 75% above ₹5 lakh, under RBI rules in force since 1 April 2026. Only the gold content is valued, not stones, and a lender may offer less than the cap.
Does repaying a gold loan improve my credit score?
Yes, it can. Gold loans are reported to the bureaus, so on-time payments add positive history. Results depend on everything else on your report. A missed payment hurts your score just as it would on any loan.
What happens if I can't repay a gold loan?
The lender can auction your gold after giving you notice. RBI rules set a reserve price of at least 90% of the gold's current value and require any surplus to be refunded within seven working days of the lender receiving the proceeds. The missed payments also stay on your credit report.
The Bottom Line
An instant gold loan is often the most realistic credit for someone with a low score, and from a regulated lender it comes with real protections on valuation, return and auction. Treat it as a short-term tool. Borrow the smallest amount you need, and pay on time so the loan helps your record instead of costing you your jewellery. For other routes, including FD-backed cards, see our guide to a credit card for a low CIBIL score.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
