300 Credit Score Loans: What You Can Get at 300, 500 and 600
Your score band decides which doors are open. Here's what each one realistically unlocks, and how to reach the next.

Realistic 300 credit score loans from regulated lenders are almost always secured: a gold loan or a loan against your own FD. Around 500 to 549, the same secured routes stay open, plus an FD-backed card. From about 550 to 649, some RBI-registered NBFCs consider small unsecured loans at high rates. Nothing is guaranteed at any band, and a score of 0 or -1 means no history, not a bad one.
Key TakeawaysGroScore's guidance treats below 600 as the zone where approvals get hard, and 750+ as good (groscore.in).Secured credit (gold, an FD, an FD-backed card) is the realistic route at every band below 600.Two people on the same score can need opposite fixes. The reason for the score matters more than the number.Any offer of guaranteed approval or no credit check at these bands is a scam, not a shortcut (RBI-regulated lenders always check a bureau).
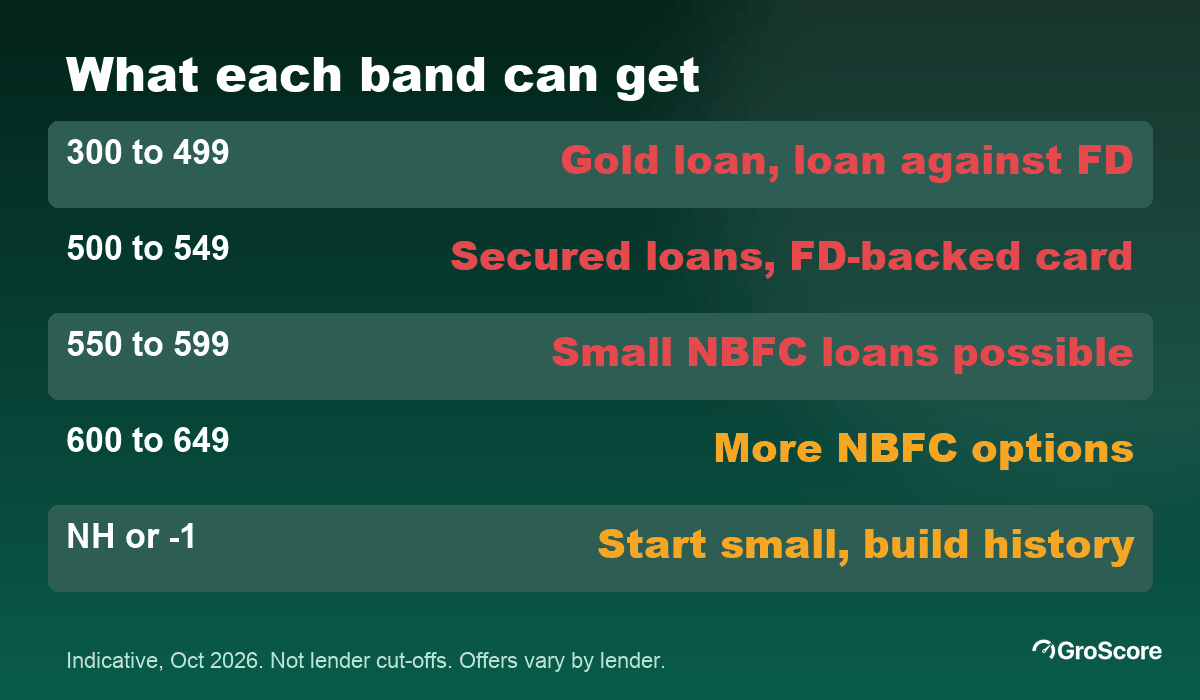
Indicative, as of October 2026. Find your band first, then read its section.
Not sure which band you're in? Check your score free on GroScore. It's a soft check, so it doesn't affect the score.
Are 300 Credit Score Loans Possible?
A score of 300 is the floor of India's 300 to 900 scale. Hardly anyone sits exactly there. Scores in the 300s usually mean several serious problems at once: loans unpaid for months, accounts "written off" or "settled", cards handed to collections.
To a lender, that reads as a high chance of not being repaid. Unsecured credit (a personal loan, a regular credit card) is very unlikely from any regulated lender. Secured credit is a different story, because the lender holds something it can recover.
So what can you get with a 300 to 499 score? Mainly:
- A gold loan. The gold is the security, so the score carries less weight.
- A loan against your own fixed deposit. Often the cheapest borrowing there is.
Two routes may not sound like much, but they're real. For the full list of safe options at a low score and what each costs, see our guide to a loan for low CIBIL score. This page goes band by band instead.
A note on who's writing. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender.
And on the word "CIBIL": TransUnion CIBIL is one of four credit bureaus on the RBI's list of credit information companies, with Equifax, Experian and CRIF High Mark. Your score can differ a little between them, and a lender may check any one. The number GroScore shows is your Equifax score, not a CIBIL score.
Loan Options by Score Band: 300, 500, 550 and 600
Here's what each band tends to unlock. These are indicative patterns, not lender cut-offs.
| Score band | Realistic options | Unlikely | Your first move |
|---|---|---|---|
| 300 to 499 | Gold loan, loan against FD | Any unsecured loan or card | Find and settle open overdue accounts |
| 500 to 549 | Gold loan, loan against FD, FD-backed card | Personal loans at most lenders | Start an FD-backed card, pay in full |
| 550 to 599 | The above, plus small NBFC loans at a higher cost | Bank personal loans | Cut card use, stop applying |
| 600 to 649 | More NBFC personal loan options; co-applicant loans | Cheaper bank loans | Fix errors, then apply once |
| NH or -1 | First-time borrower products, secured loans | Large unsecured loans | Build a history first |
Indicative, as of October 2026. These aren't lender-published cut-offs, and actual offers vary by lender, income and credit profile.
Income moves every row. A salaried borrower at 610 with no other EMIs may get an offer that a borrower at 640 with three running loans won't. Lenders also check your FOIR (fixed obligations to income ratio), the share of your monthly income already going to EMIs.
Can You Get a Loan With a 500 CIBIL Score?
A secured one, usually yes. An unsecured one, usually no.
At 500 to 549, the report typically shows a recent serious delay: a loan 90 days or more overdue, or a settlement. Most banks and many NBFCs won't approve a personal loan here. Searches for "loans for 500 credit score" mostly turn up offers you shouldn't trust.
Here's what does work at a 500 CIBIL score:
- Gold loans and loans against an FD, as above.
- An FD-backed credit card. It won't fund a big expense. It will add on-time payments to your report every month, which is how the band starts to move. Our guide to a credit card for a low CIBIL score shows how these cards work.
Here's why the route matters. For example, take an illustrative ₹50,000 (as of October 2026) over 12 months. At 12% a year, a rate a secured loan might carry, the EMI works out to ₹4,442 and total interest to ₹3,309. At 28%, a rate an unsecured lender might charge a low-score borrower, the EMI is ₹4,825 and total interest ₹7,904.
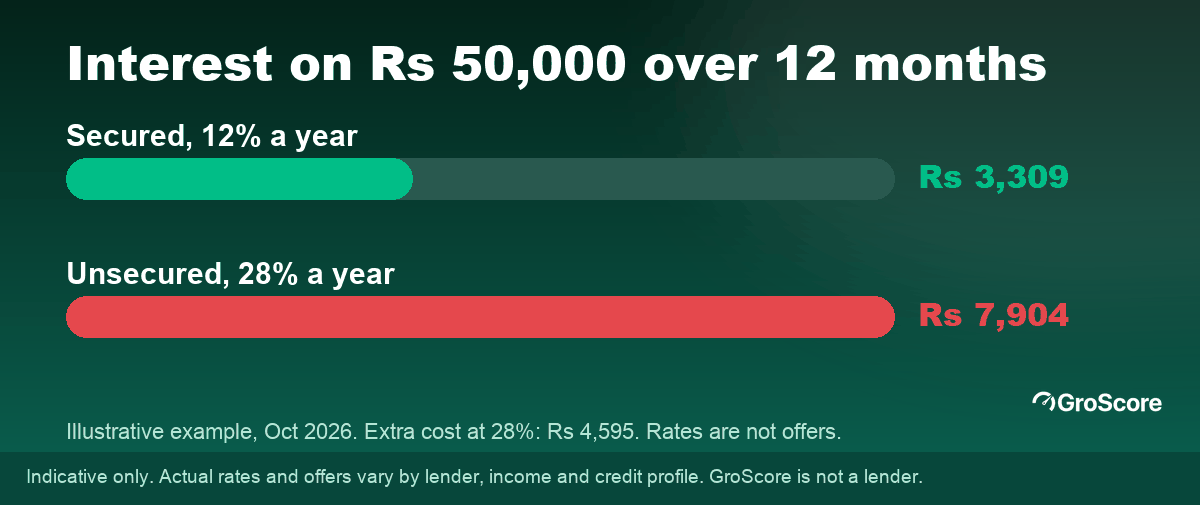
Illustrative example as of October 2026: the same ₹50,000, two very different bills.
The secured route works out ₹4,595 cheaper in this case. These are illustrative figures as of October 2026, worked out with the standard EMI formula. They aren't offers, and actual offers vary by lender, income and credit profile. Compare the APR in each lender's Key Fact Statement, which RBI rules require before you sign. If gold is your route, our guide to an instant gold loan covers how much you can borrow and what happens if you can't repay.
Is 600 CIBIL Enough for a Personal Loan?
Sometimes, from an NBFC, for a smaller amount, at a higher rate. Rarely from a bank.
Between 550 and 649, your report usually shows one or two late payments in the last year, or cards used close to their limit. Neither is permanent. That's why this band moves fastest when you act on the right item.
A personal loan for a CIBIL score of 550 is a stretch at most lenders. Some RBI-registered NBFCs do consider it with steady income, and a co-applicant with a strong score improves the odds. At a 600 CIBIL score, more NBFCs open up, though the rate stays well above what a 750+ borrower would pay.
Before you apply, ask two questions:
- Can it wait two or three months? If yes, paying card balances down first may move you up a band.
- Have you already applied elsewhere? Each application adds a hard enquiry. Several in a month can pull a 600 lower.
Why start with card balances? GroScore's guidance is to keep card use under 30% of the limit (groscore.in, retrieved 2026-10-05), and lenders have reported to the bureaus every week since 1 July 2026 (RBI). A paid-down balance can show up on your report sooner than it used to, though how much the score moves depends on the rest of the report.
For the full climb, our 600 to 750 plan breaks it into steps.
What Does a 0 or -1 CIBIL Score Mean for a Loan?
A 0 or -1 means no history, not bad history. A "0 CIBIL score loan" search usually comes from someone who has never borrowed.
Your report shows "NH" (no history) or "-1" when nothing has been reported in your name. Some reports show "NA" or a 0 when there's credit, but too little or too recent to score. None of these is a penalty. Lenders simply can't judge you yet, so they lean on your income, job and bank statement, and they start you small.
Your best first steps are a loan against an FD, a small first loan from a regulated lender, or an FD-backed card to build a record. Our guide to a loan without a CIBIL score covers which of these work, and why "no credit check" offers aimed at you are a red flag.
Same Score, Different Plan: What a Credit Coach Would Flag
Here's an illustrative example. For instance, say two people both show an Equifax score of 550. Arjun, GroScore's credit coach, reads each report.
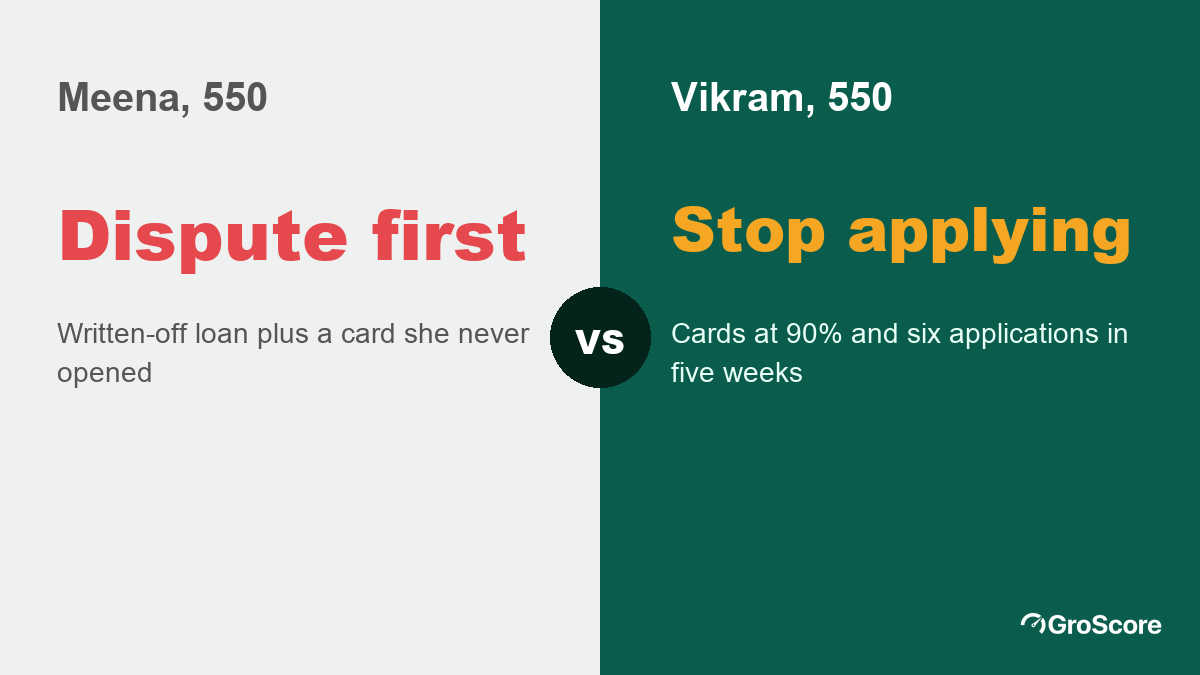
Illustrative example: the same 550, two different reports.
Meena, 38, has a personal loan marked "written off" from three years ago, plus a credit card she says she never opened. Arjun's order:
- Dispute the card she doesn't recognise. If it isn't hers, it's an error, and errors can be corrected. Our guide to a CIBIL dispute shows how.
- Talk to the lender about the written-off loan. Paying it can change the status, though the history stays.
- Borrow only against gold or an FD for now.
Meena's first step isn't unusual. GroScore says about 1 in 5 reports carries an error, roughly 20% (groscore.in, retrieved 2026-10-05), which is why Arjun reads every account line before the score.
Vikram, 27, has no defaults at all. His two cards are at 90% of their limits (an indicative figure for this example), and he's made six loan applications in five weeks. Arjun's order:
- Stop applying. Every new enquiry costs him a little more.
- Pay the cards down below 30% before the next statement date.
- Then apply once, to one regulated lender.
Vikram's score can recover faster, because his problems are recent and fixable. Meena's written-off loan is accurate, so nobody can remove it early, whatever a "credit repair" agency claims. It fades as new on-time payments build up. Results depend on what's on each report, and neither gets a promised number of points.
GroScore can't approve either loan. It can rank the fixes and show which lenders' criteria each profile clears, across 100+ loans and cards from 60+ banks and NBFCs (groscore.in, retrieved 2026-10-05). The lender still decides.
How to Move Up a Band Without Getting Scammed
Low bands attract the worst offers. "Loan for any CIBIL score", "approval for everyone", "300 CIBIL score loan app, no questions". Every RBI-regulated bank and NBFC checks a credit report, so these promises are a myth at best and a scam at worst.
Keep to three rules:
- Never pay a fee upfront to unlock a loan, especially to a personal UPI ID.
- Check the lender. A bank, or an NBFC on the RBI's list of registered NBFCs. For an app, the RBI's directory of digital lending apps. Our guide on how to check if a loan app is RBI-registered walks through it.
- Report fraud. Call 1930, file at cybercrime.gov.in, or report an unauthorised lender on the RBI's Sachet portal.
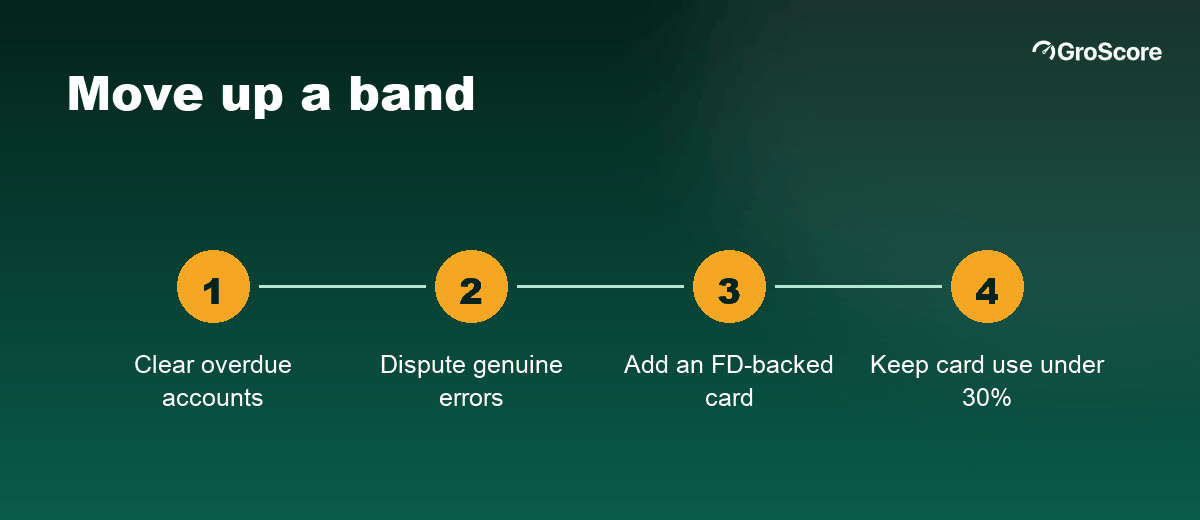
Four moves, in this order, for most low-band reports.
Frequently Asked Questions
Can I get a loan with a 300 credit score?
From a regulated lender, usually only a secured one: a gold loan or a loan against your own FD. A score in the 300s typically reflects serious defaults, so unsecured loans and regular cards are very unlikely until the report improves.
Which loan can I get with a 550 CIBIL score?
Gold loans, loans against an FD and FD-backed cards are the realistic options. Some RBI-registered NBFCs may consider a small personal loan at 550 with steady income, at a high rate. A co-applicant with a strong score can help.
Is 600 CIBIL enough for a personal loan?
Sometimes, from an NBFC, for a smaller amount and at a higher rate than a 750+ borrower would pay. Banks rarely approve unsecured loans at 600. Paying card balances down first may lift you into a better band before you apply.
What does a 0 or -1 CIBIL score mean for a loan?
A 0 or -1 means no credit history, not a bad one. Lenders can't judge you yet, so they look at your income and bank statement and usually start small. A loan against an FD or an FD-backed card is the easiest first step.
The Bottom Line
Your band tells you which doors are open today. At 300 to 549, that's secured credit, so use it to borrow less and build history. From 550 to 649, small NBFC loans become possible, but a few months of fixing can make them cheaper or unnecessary. At every band, check the lender, compare the APR and never pay to unlock a loan. The next band is usually closer than the number suggests, once you know which line on the report is holding you there.
Disclaimer
This article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
