Instant Loan Without CIBIL: What's Possible and What's a Scam
Three things people mean by a loan without CIBIL. Two of them have honest answers. The third is how scams find you.

An instant loan without CIBIL, in the sense of no credit check at all, doesn't exist at RBI-regulated banks and NBFCs. Every one of them checks a credit bureau before lending. Here's what is possible: a small first loan when you have no score yet, a secured loan where the score matters less, or a lender that checks Equifax or Experian instead of CIBIL. Anyone promising "no check, guaranteed approval" is the warning sign.
Key Takeaways"No credit check" and "guaranteed approval" are myths, not offers, at RBI-regulated lenders. They all read at least one bureau report (RBI).No score (shown as NH or -1) is different from a bad score. Some regulated lenders do lend small amounts to first-time borrowers.A gold loan or a loan against your own FD leans far less on your score, but the lender still runs a check.RBI rules bar lending apps from reading your contacts, photos or call logs, and loans must be paid into your own bank account (RBI, May 2025).
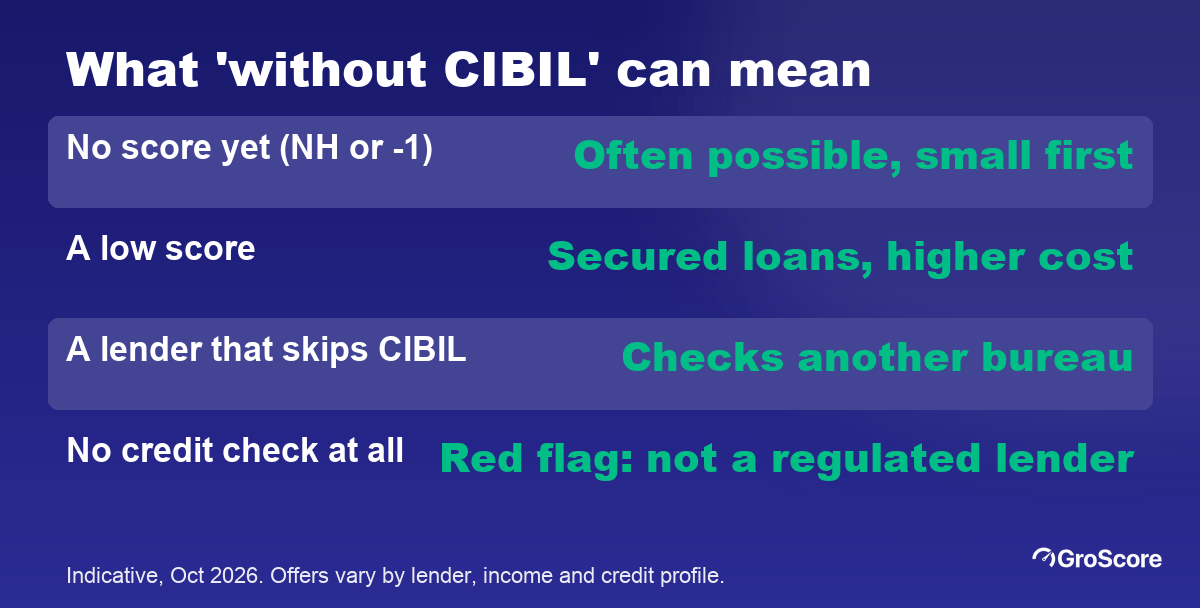
Four different situations hide behind the same search.
Before you apply anywhere, see what a lender will see. You can check your score free on GroScore, with a soft check that doesn't affect it.
What Does "Loan Without CIBIL" Actually Mean?
People type the same words for three very different problems. The one that fits you decides the answer.
| What you mean | Is it possible? | Where to start |
|---|---|---|
| "I have no CIBIL score yet" | Often, for small amounts | First-time borrower products, secured loans |
| "My CIBIL score is low" | Sometimes, at a higher cost | Gold loan, loan against FD, a co-applicant |
| "I want a lender that skips CIBIL" | Yes, but it checks another bureau | Your history still shows |
| "I want a lender that checks nothing" | Not from a regulated lender | Treat it as a red flag |
Indicative, as of October 2026. Actual offers vary by lender, income and credit profile.
So the honest answer to "can I get a loan without CIBIL?" is: it depends which of these you are. Most of this guide is about the first, third and fourth rows. If you're in the second, our guide to a personal loan with a low CIBIL score walks through the safe options and what they cost.
A quick word on who's writing. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. It doesn't give, approve or disburse loans, and the score it shows is your Equifax score, not a CIBIL score.
Do RBI-Regulated Lenders Ever Skip the Credit Check?
No. A lender might skip CIBIL, though. That's the part most pages miss.
"CIBIL" has become shorthand for any credit score, the way people say "Xerox" for a photocopy. In fact TransUnion CIBIL is one of four credit bureaus registered with the RBI. The others are Equifax, Experian and CRIF High Mark, according to the RBI's list of credit information companies. A lender may pull any one of them, or several.
So a lender that "doesn't check CIBIL" may simply check Equifax. Your history still counts. A default reported to one bureau is usually reported to the others too, because lenders send data to all four.
A different bureau isn't the same thing as no check.
What about loans backed by gold or a fixed deposit? These lean much less on your score, because the lender holds security. They still look at your report. A secured loan just forgives more.
Real "no credit check loans" do exist in one place: outside the regulated system. Unregistered apps and informal lenders skip the check because they plan to recover the money some other way, often through crushing fees or harassment.
Can You Get a Loan With No CIBIL Score at All?
Often, yes. You just won't get a large unsecured loan on day one.
Having no credit score means the bureau has nothing to judge. Your report shows "NH" (no history) or "-1". You've never had a loan or a credit card, or nothing has been reported yet. That's unknown risk, not bad risk, and lenders treat the two differently.
When there's no score, a lender leans on other things:
- Your bank statement. Regular salary credits and steady balances tell a story.
- Your employer and job. A salaried role at a known company helps.
- Your KYC. PAN, Aadhaar and a verified address are the baseline.
- The amount. Small and short is easier than large and long.
A loan without credit history usually starts small. Some salary-linked products and small-ticket loans from regulated NBFCs are built for exactly this borrower. They still pull a bureau report, and they'll see NH. That's fine.
A slower but cheaper route is to build a score first. An FD-backed credit card is the usual starting point; our guide to build a credit score from scratch has a worked six-month plan. Once you have one or two clean accounts on your report, an instant personal loan without CIBIL history problems becomes an ordinary instant personal loan.
Secured Routes That Need Less From Your Score
If the money is needed soon and you have no score, or a thin one, security does the work your score can't.
Loan against an FD. You borrow against your own deposit. It's usually priced only a little above the FD rate, and the deposit keeps earning.
Gold loan. You pledge gold jewellery, and the lender lends part of its value. It's fast. Miss payments, though, and the lender can auction the gold. Our guide explains how an instant gold loan works with a low score.
A co-applicant. A family member with a good score and income applies with you. Their score helps. Their score also gets hurt if an EMI is missed.
Here's what the choice can cost. For example, take an illustrative ₹40,000 needed for six months.
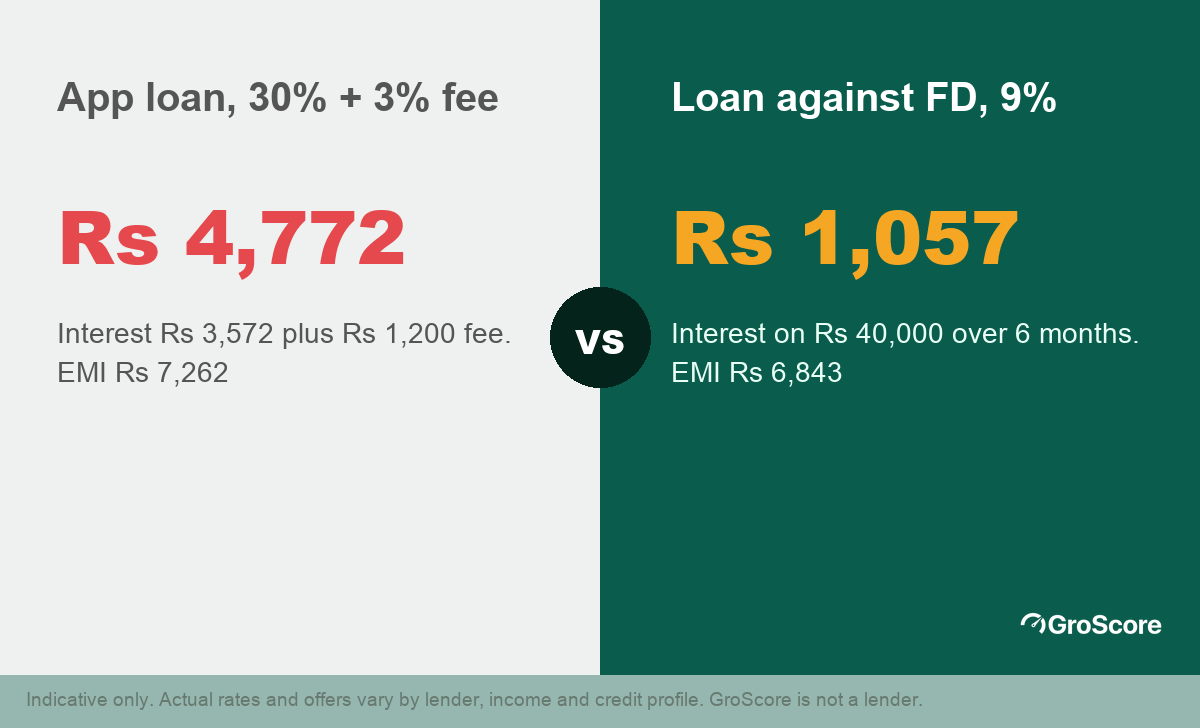
Illustrative example as of October 2026: the same ₹40,000, two very different bills.
- Loan against FD at 9% a year (illustrative, as of October 2026): the EMI works out to ₹6,843 and total interest to ₹1,057.
- Unsecured app loan at 30% a year, plus a 3% processing fee: the EMI is ₹7,262. Interest comes to ₹3,572, and the ₹1,200 fee takes the total cost to ₹4,772.
The FD route works out ₹3,715 cheaper for the same money over six months. These are illustrative figures, worked out with the standard EMI formula as of October 2026. They aren't offers. Actual offers vary by lender, income and credit profile. Whichever you pick, compare the APR in the Key Fact Statement, which RBI rules require before you sign.
For a band-by-band view of what each score range can realistically get, see our guide to a loan with a 500 or 600 score.
How to Spot a Fake Instant Loan Without CIBIL Offer
Scam apps go after this exact search. The pitch writes itself. No CIBIL, no documents, money in ten minutes.
Real rules make the fake ones easy to catch. Under the RBI's Digital Lending Directions of May 2025 (RBI):
- The loan goes straight into your bank account. Never to a third party, never "after you pay a fee".
- The app can't read your contacts, photos, files or call logs. It may ask for one-time camera, microphone or location access for KYC, with your consent.
- You get a Key Fact Statement showing the all-in annual percentage rate (APR) before you sign.
- Any fee the app's service provider charges is paid by the lender, not collected from you.
- You get a cooling-off period of at least one day to exit the loan by repaying the principal and proportionate interest, without a penalty.
Any app that breaks one of these isn't following RBI rules.
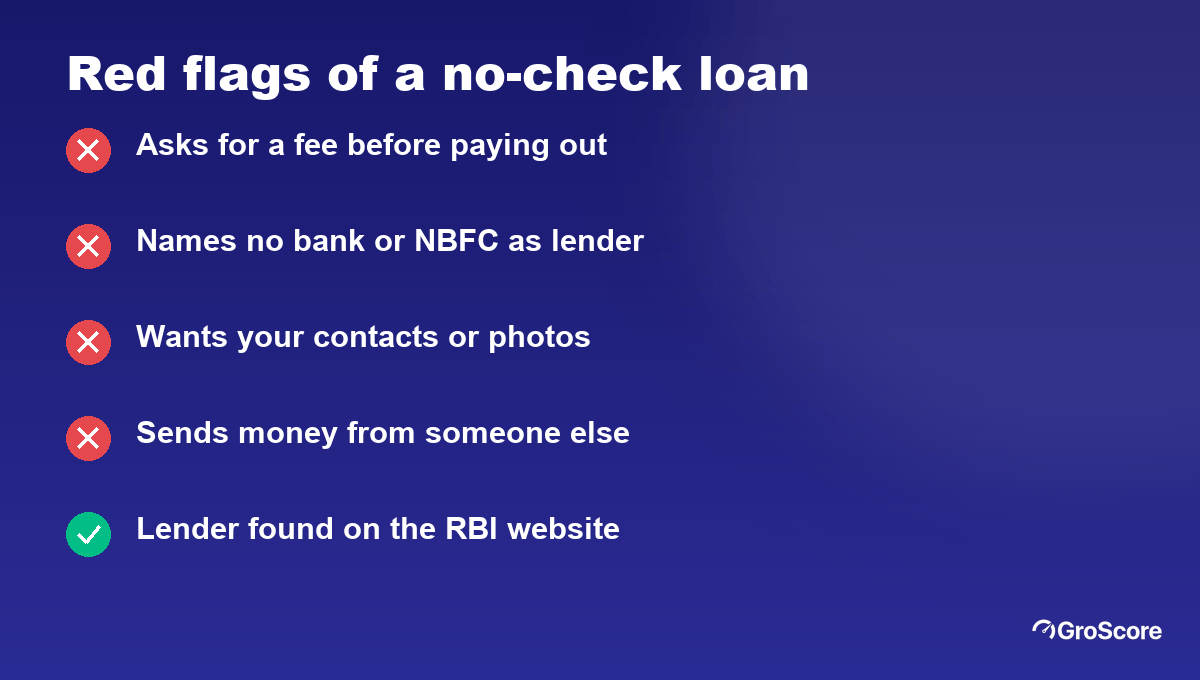
Any one of these is reason enough to stop.
Before you share your PAN, find out who the lender really is. The app should name a bank or an NBFC. Search for an NBFC on the RBI's list of registered NBFCs, and look for the app in the RBI's directory of digital lending apps on its website. Our guide on how to check if a loan app is RBI-registered shows each step.
Already paid a "processing fee" and got nothing? Stop paying. More money never unlocks the loan. Keep the screenshots, call the cybercrime helpline on 1930 or file at cybercrime.gov.in, and report the app on the RBI's Sachet portal.
What Would a Credit Coach Check Before You Apply?
Here's an illustrative example. For instance, say Kavya, 24, has been in her first job for eight months and needs ₹40,000 for a short course. She searched "personal loan without cibil" and found an app promising approval in five minutes. Before she applies, Arjun, GroScore's credit coach, goes through her situation with her:
- Her report. It shows NH. No bad marks, just no history. So the app's "no CIBIL" promise solves a problem she doesn't have.
- The app. It names no lender and asks for contacts access. Two red flags. She deletes it.
- Her savings. She has an FD of ₹60,000 (an indicative figure for this example). A loan against it is the cheapest route, and it keeps the deposit earning.
- The next six months. An FD-backed card, used lightly and paid in full, starts a history. Next time she borrows, she'll have a score to show.
Why read a report that shows NH at all? Errors reach new borrowers too, and GroScore says about 1 in 5 reports carries one, roughly 20% (groscore.in, retrieved 2026-10-05). For the card, Arjun's rule of thumb is GroScore's own guidance: keep use under 30% of the limit (groscore.in).
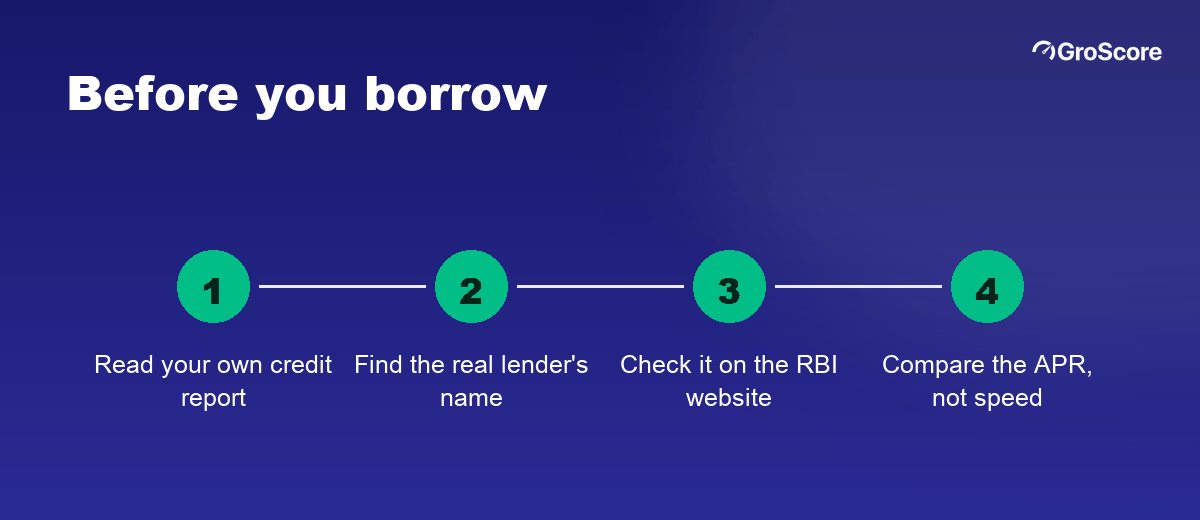
Four checks, about ten minutes, before you share a document.
GroScore can't approve Kavya's loan or speed it up. It shows her Equifax report and which lenders' criteria her profile clears, and the lender decides. If you're shopping for an app specifically, our guide to safe loan apps for low scores shows how to vet one.
Frequently Asked Questions
Can I get a loan with no CIBIL score?
Often, yes, for a small amount. No score (NH or -1) means no history, not bad history. Regulated lenders will look at your salary credits, job and KYC instead, and a loan against an FD or gold is easier still. Expect smaller amounts first.
Do any RBI-regulated lenders give loans without checking CIBIL?
Some don't pull TransUnion CIBIL specifically, but they check at least one of the four RBI-registered bureaus: CIBIL, Equifax, Experian or CRIF High Mark. A loan with no bureau check at all only comes from outside the regulated system.
What is the easiest first loan to get with no credit history?
A loan against your own fixed deposit is usually the easiest and cheapest, because your deposit secures it. A gold loan is also quick. For building a score, an FD-backed credit card is the common first step.
Is a 'no credit check loan' safe?
No. A lender that checks nothing is usually unregistered and plans to recover the money through high fees or pressure. Under RBI rules, a real lending app names its bank or NBFC, pays the loan into your account and can't read your contacts.
Is a salary advance loan without a CIBIL check real?
Salary advance products from regulated lenders still check a bureau, even if the decision is quick. They may not need a high score, though, because your salary credits carry more weight. If an offer says "no check at all", verify the lender before you share anything.
The Bottom Line
There's no honest version of an instant loan without CIBIL or any other check. There are honest versions of what most people actually need: a first loan with no history, a secured loan with a thin file, or a lender that reads a different bureau. Know which one you are, verify the lender on the RBI website, and compare the APR, not the speed. And if an app promises approval for everyone, you've already learned the most useful thing about it.
Disclaimer
This article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
