Low CIBIL Score Loan App: How to Pick a Safe One
No list can tell you which app is safe for you. Six checks, about fifteen minutes, can.

A safe low CIBIL score loan app is one where a bank or RBI-registered NBFC is the actual lender, the app appears in the RBI's directory of digital lending apps, and you see the full APR before you sign. Some regulated lenders do consider scores in the 500s and 600s through apps, usually for small amounts at high rates. No genuine app skips the credit check or promises approval.
Key TakeawaysA loan app is a shopfront. The lender behind it must be a bank or an RBI-registered NBFC, and the app must name it (RBI).RBI rules bar lending apps from reading your contacts, photos or call logs, and give you a cooling-off period of at least one day (RBI, May 2025).A "2% a month" loan with fees can cost far more than 24% a year. Compare the APR in the Key Fact Statement, never the headline rate."Best loan app for low CIBIL" lists can't vet an app for you. The six checks below can.
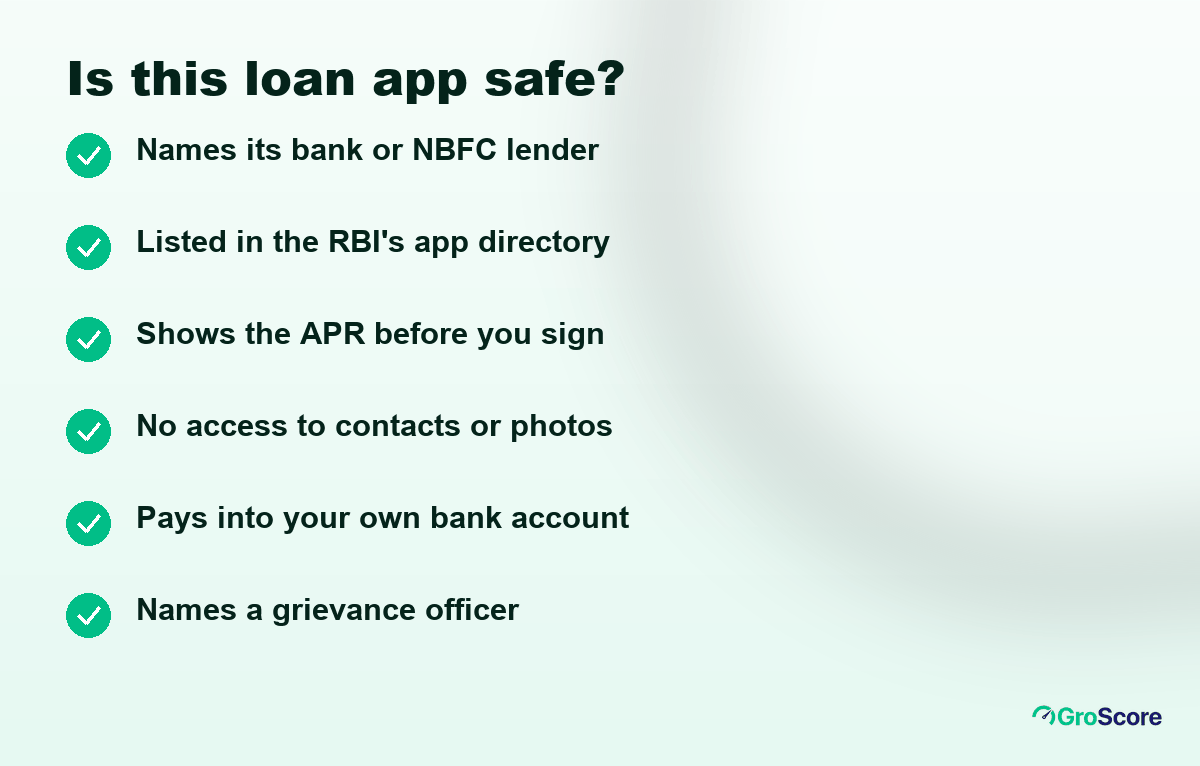
If an app fails any one of these, close it.
Before you try any app, know what it will see. You can check your score free on GroScore, with a soft check that doesn't affect it.
Is There a Safe Loan App for a Low CIBIL Score?
Yes, but "safe" describes the lender, not the app.
Most loan apps don't lend their own money. The app is run by a lending service provider (LSP), a tech company that finds borrowers. The money comes from a regulated entity: a bank or an NBFC (non-banking financial company) registered with the RBI. When people ask which loan app gives loans on a low CIBIL score, the real question is which regulated lender behind an app will.
Some will, within limits. Expect smaller amounts, shorter tenures and higher rates than someone with 750+ would get. Whether you qualify depends on your income, existing EMIs and what's on your report, not the app's ads. For the wider picture of loans at a low score, including gold loans and co-applicants, see our guide to a loan for low CIBIL score.
A note on who's writing. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender and isn't a loan app. It doesn't give, approve or disburse loans.
One more thing about the word "CIBIL". TransUnion CIBIL is one of four RBI-registered credit bureaus, alongside Equifax, Experian and CRIF High Mark. An app's lender may check any of them. The score GroScore shows is your Equifax score, not a CIBIL score.
How Do I Check If a Loan App Is RBI-Registered?
Run these six checks before you upload a single document. Each one comes straight from the RBI's Digital Lending Directions, 2025.
| Check | Where to look | What a safe app shows |
|---|---|---|
| 1. Named lender | The app's loan offer and website | The bank or NBFC that funds the loan, by name |
| 2. RBI directory | The digital lending apps directory on the RBI website | The app listed against that lender |
| 3. Real cost | The loan offer screen | The APR, EMI and penal charges, with a Key Fact Statement |
| 4. Phone access | The permissions it asks for | No contacts, photos, files or call logs |
| 5. Money flow | Your bank statement | Loan paid into your own account; repayments go to the lender |
| 6. Complaints | The app and lender websites | A named grievance redressal officer |
For an NBFC, also search its name on the RBI's list of registered NBFCs. A bank needs no such search, but the app should still name it.
A few details trip people up. The RBI allows an app one-time access to your camera, microphone or location for KYC, with your consent. Anything beyond that is a red flag. And any fee the LSP charges is paid by the lender, under the same Directions. It isn't collected from you.
What Does a Low CIBIL Score Loan App Really Cost?
More than the headline rate, almost always. Low-score app loans tend to be small and short, so fixed fees weigh heavily. If your score is very low, our guide to 300 credit score loans shows what's realistic at 300, 500 and 600.
Here's an illustrative example as of October 2026, with the arithmetic shown. Say an app offers ₹20,000 over three months at "2% a month", which sounds like 24% a year. It also charges a 3% processing fee of ₹600, plus 18% GST on that fee, which is ₹108. Both are deducted from the payout.
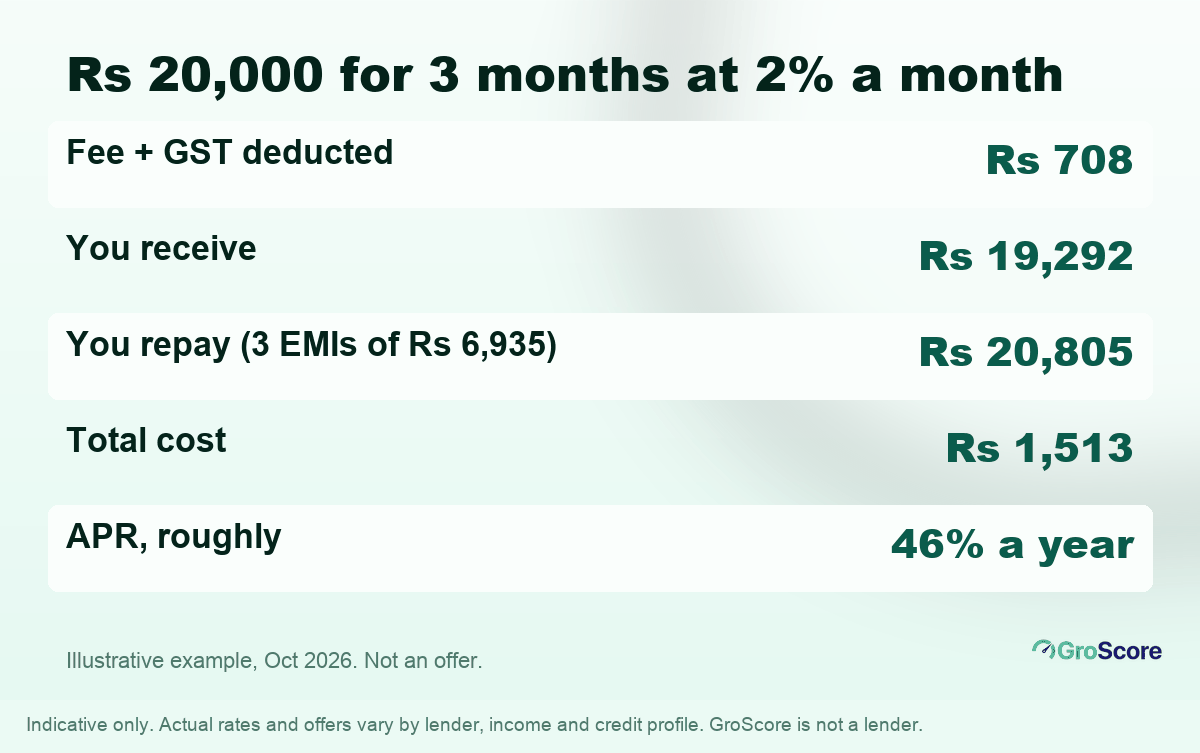
Illustrative example as of October 2026: a 24% headline can mean a 46% APR.
- You receive (illustrative, October 2026): ₹20,000 minus ₹708 in fee and GST, which is ₹19,292.
- You repay: three EMIs of ₹6,935, about ₹20,805 in all.
- Total cost: ₹805 in interest plus ₹708 in fee and GST, or ₹1,513.
Measured against the ₹19,292 that actually reached you, that works out to an APR of roughly 46% a year. These are illustrative figures as of October 2026, not offers. Actual offers vary by lender, income and credit profile. Under RBI rules, the lender must show you the APR in the Key Fact Statement before you sign, so you never have to work it out yourself.
Two habits keep the cost honest:
- Compare APRs (as shown in the Key Fact Statement), not "per month" or "per day" rates. A daily rate hides the annual cost better than anything.
- Use the cooling-off period. The RBI requires at least one day in which you can exit by repaying the principal and the proportionate APR, with no penalty. The lender may keep a one-time processing fee only if the Key Fact Statement disclosed it.
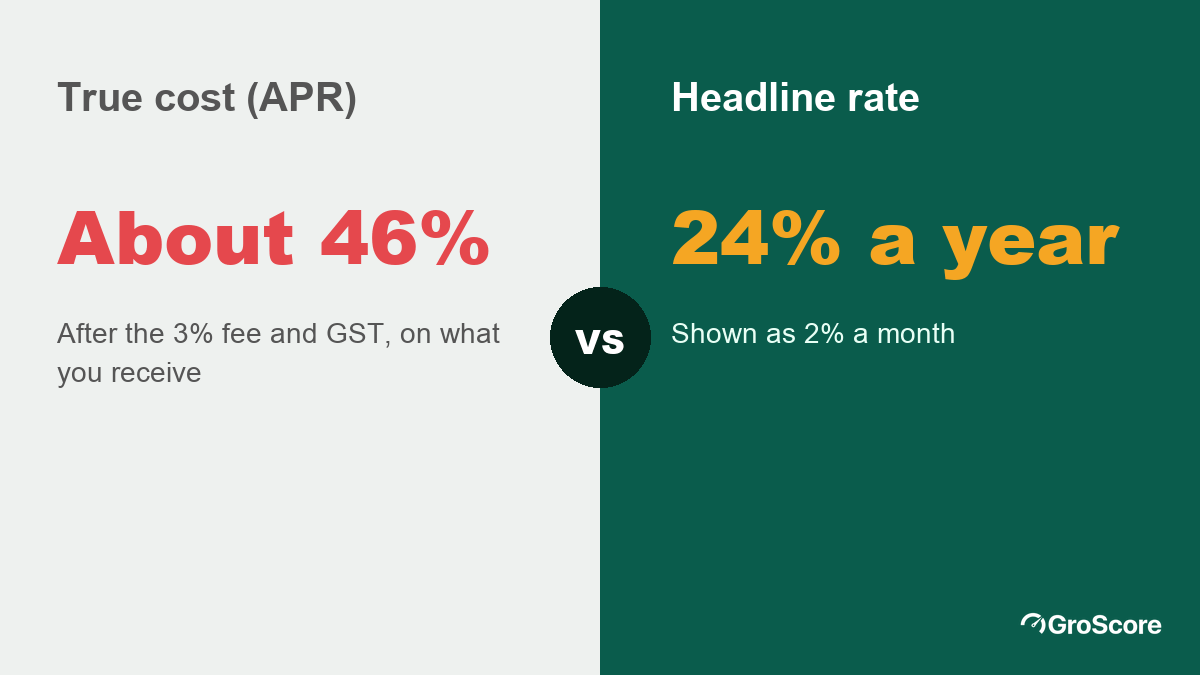
Illustrative, October 2026. The fee is small. On a short loan, its effect isn't.
Why "Best Loan App Without CIBIL Score" Lists Mislead
Search "bad CIBIL loan app list" and you'll find pages ranking a dozen apps. We don't name apps here, for three reasons.
Approval isn't the app's to give. The lender decides on your full profile. An app that approved your friend at 580 may decline you at 620 because of your income or an overdue account.
Lending partners change. An app can switch, add or lose a lender. A list written in March can be wrong by June.
"Without CIBIL" is a myth for regulated lenders. A genuine app's lender always checks a bureau, even if it isn't CIBIL. If you have no score at all, that's a different problem with better answers, covered in our guide to an instant loan without CIBIL.
There's a cost to trying apps one by one, too. Each full application can add a hard enquiry, a lender's check of your report that other lenders can see. Several in a few weeks reads as credit hunger and can pull a low score lower. Checking your own score is a soft enquiry and never affects it.
What Would a Credit Coach Check Before You Download One?
Here's an illustrative example. For instance, say Imran, 31, has an Equifax score of 610 and wants ₹25,000 for a family wedding. He's already installed three loan apps. Arjun, GroScore's credit coach, goes through his report and phone with him, in this order:
- An app loan from last year showing a DPD of 60. DPD means days past due, so this one was two months late. It's still open with a small balance. Clearing it comes first, because an open overdue account hurts more than anything else here.
- Four enquiries in three weeks from the apps he's tried. The advice: stop applying until the overdue loan is closed.
- One of the three apps names no lender and asked for his contacts. He uninstalls it and revokes the permission.
- The other two apps. Both name an NBFC. Imran checks each on the RBI's list of registered NBFCs and the digital lending directory, then compares their APRs.
Why the overdue loan first? Missed payments do the most damage to a score, and GroScore says a single missed EMI can cost 50 to 100 points (groscore.in, retrieved 2026-10-05). Results depend on what else is on the report, so nobody can promise how much clearing it helps, or how fast.
Arjun also reads every account line, not just the score. GroScore says about 1 in 5 reports carries an error, roughly 20% (groscore.in, retrieved 2026-10-05), and a genuine error can be disputed with the bureau.
GroScore can't get Imran a loan, and it can't remove the late payment, because accurate entries stay on the report. It can rank his fixes and show which lenders' criteria his profile clears, across 100+ loans and cards from 60+ banks and NBFCs (groscore.in, retrieved 2026-10-05). The lender still decides. If Imran needs money sooner, a secured option like an instant gold loan relies more on the gold than on his score.
What to Do If a Loan App Harasses You
Recovery is allowed. Abuse isn't. Under the RBI's Directions, a lender must tell you by email or SMS who its recovery agent is before that agent contacts you.
If an app threatens you, calls your contacts or shares your photos, take these steps:
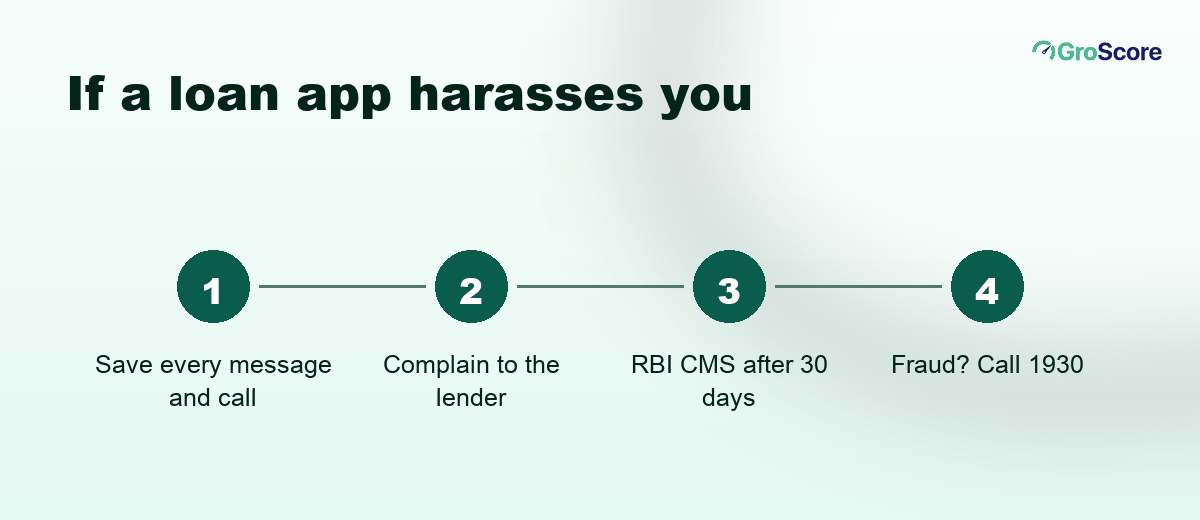
Keep every message. Evidence is what makes each step work.
- Save everything. Screenshots, call logs, numbers, payment receipts.
- Complain to the lender's grievance redressal officer. The RBI gives a regulated lender 30 days to respond.
- Escalate to the RBI. If the lender doesn't resolve it in 30 days, or rejects your complaint, file on the RBI's Complaint Management System at cms.rbi.org.in.
- Report crime and unregistered apps. Call the national cybercrime helpline on 1930 or file at cybercrime.gov.in. Report an unauthorised lender on the RBI's Sachet portal.
Don't pay money you don't owe to make the calls stop. If the app was never regulated, paying rarely ends it. Our guide to fake loan apps covers what to do if you've already shared documents.
Frequently Asked Questions
Which loan app gives loans on a low CIBIL score?
Some apps whose lending partner is an RBI-registered NBFC do consider scores in the 500s and 600s, usually for small amounts at high rates. No app can promise approval, because the lender decides on your income, existing EMIs and report. Verify the lender before you apply rather than trusting a ranked list.
Is there any loan app that doesn't check CIBIL?
Not one backed by an RBI-regulated lender. Every bank and NBFC checks at least one of the four bureaus: CIBIL, Equifax, Experian or CRIF High Mark. An app that says it checks nothing is either misleading you or isn't regulated.
How do I check if a loan app is RBI-registered?
Find the bank or NBFC the app names as its lender. Search an NBFC on the RBI's list of registered NBFCs, and look for the app in the RBI's directory of digital lending apps. If the app names no lender, or the names don't match, don't apply.
What is a safe interest rate for an app loan?
There's no single safe number, so compare the APR in the Key Fact Statement across two or three regulated lenders. Be wary when fees are large against a small, short loan. For example, in our illustrative case as of October 2026, a 24% headline rate became an APR of about 46% once fees were counted.
What should I do if a loan app harasses me?
Save the evidence and complain to the lender's grievance officer. If it isn't resolved in 30 days, escalate on the RBI's Complaint Management System. For threats, fraud or an unregistered app, call 1930 and report the app on the RBI's Sachet portal.
The Bottom Line
The safest low CIBIL score loan app is the one you've verified yourself: a named, regulated lender, a listing in the RBI's directory, an APR you've read and a phone that keeps its contacts private. Apply to one or two, not ten, because each application can leave a mark (our guide to hard vs soft enquiries explains why). And if your report has an overdue account or an error on it, fixing that first may do more for your next loan than any app can.
Disclaimer
This article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
