CIBIL Score for Personal Loan: Minimum Needed and Rates
Most banks want 750+ for a personal loan. Here's what changes at 700, 650 and 600, and what the rate gap really costs.

At most banks, the CIBIL score for personal loan approval is 750 or above, and that's also where the better rates usually start. Some NBFCs consider scores around 650 to 700, at higher interest. Below 600, unsecured approval gets hard. Each lender sets its own cut-off, so use these numbers as an indicative guide, not a rule.
Key TakeawaysA personal loan is unsecured, so lenders lean on your credit score more than for a home or car loan.GroScore's guidance treats 750+ as good and below 600 as the zone where approvals get hard (groscore.in).On an illustrative ₹5 lakh, five-year loan, 18% instead of 11% costs about ₹1.1 lakh more in interest.No RBI-regulated lender skips the credit check or promises approval. Offers that do are a red flag.
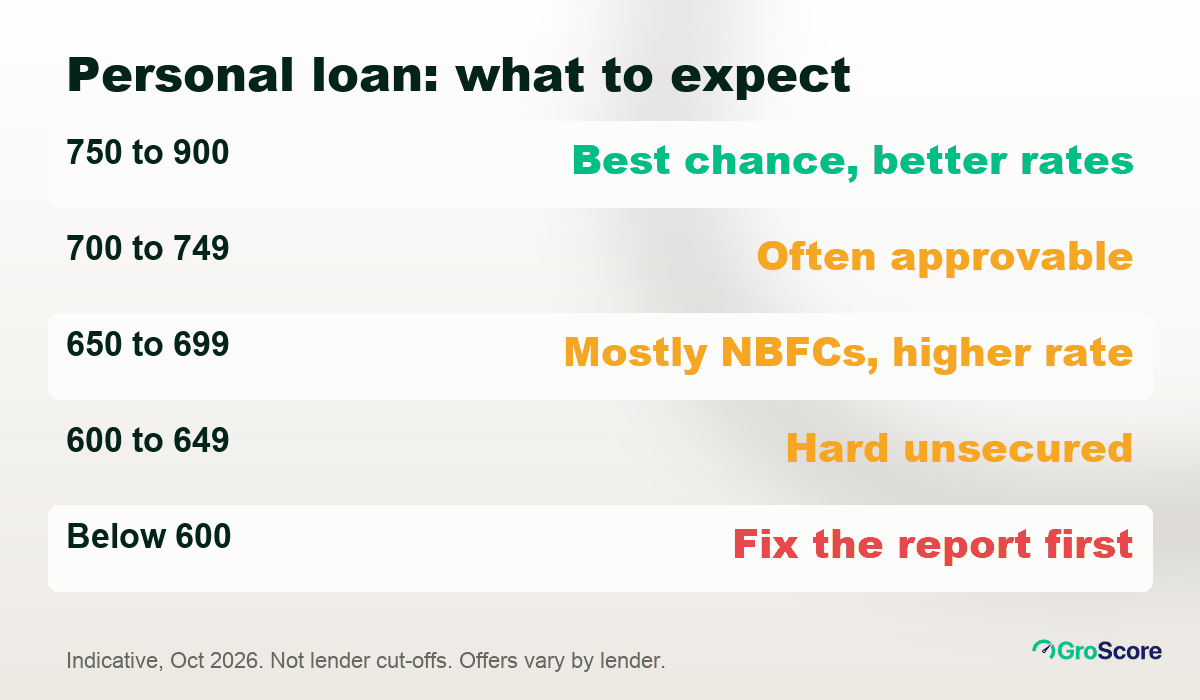
Indicative bands. Every lender draws its own lines.
What Is the Minimum CIBIL Score for a Personal Loan?
There isn't one official number. The RBI doesn't set a minimum credit score; each bank and NBFC decides its own. In practice, here's how a personal loan application tends to go at each score, as of October 2026:
| Your score | What usually happens (indicative) |
|---|---|
| 750 to 900 | Most banks and NBFCs will consider you. Better rates and pre-approved offers are more likely. |
| 700 to 749 | Often approvable, sometimes at a slightly higher rate or a smaller amount. |
| 650 to 699 | Mostly NBFCs. Expect a higher rate and closer checks on income. |
| 600 to 649 | Unsecured approval is hard. Secured options or a co-applicant work better. |
| Below 600 | Fix the report first. Approvals get hard (groscore.in). |
Indicative, based on GroScore's guidance bands (groscore.in), October 2026. These aren't lender-published cut-offs, and actual offers vary by lender, income and credit profile.
Before going further, a word on who's telling you this, since the personal loan credit score you see depends on the bureau. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. It can't approve or disburse a personal loan.
And "CIBIL"? TransUnion CIBIL is one of four credit bureaus registered with the RBI, alongside Equifax, Experian and CRIF High Mark. Lenders may pull any of them. The number GroScore shows is your Equifax score, not a CIBIL score, and it can differ from your CIBIL score by a few points.
For the cut-offs on home, car, gold and business loans, see our guide to the minimum CIBIL score for a loan.
How Much Does Your Credit Score for Personal Loan Pricing Matter?
A lot. Lenders use risk-based pricing, which means the rate you're offered depends partly on how risky your report looks. Two people borrowing the same amount can pay very different EMIs.
For example, take an illustrative ₹5 lakh personal loan over five years.
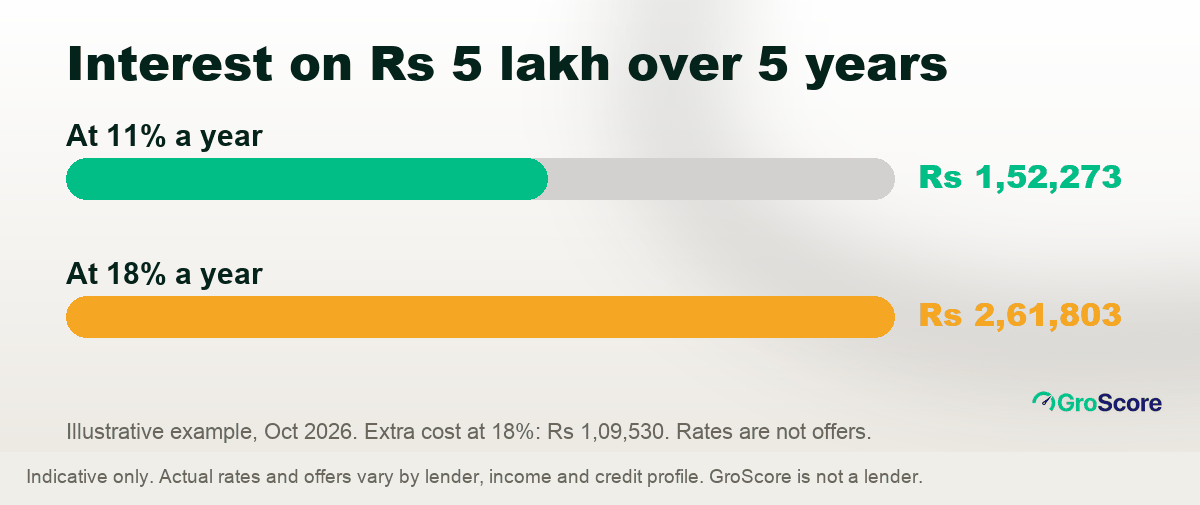
Illustrative example: the same loan at two rates.
At 11% a year, the EMI works out to ₹10,871 and total interest to ₹1,52,273. At 18%, the EMI rises to ₹12,697 and total interest to ₹2,61,803. That's ₹1,826 more every month and ₹1,09,530 more over the loan. These figures are illustrative, worked out with the standard EMI formula as of October 2026. They aren't offers or a promise of what any score will get. Actual offers vary by lender, income and credit profile. When you compare offers, compare the APR, the all-in annual percentage rate, which RBI rules require lenders to show in a Key Fact Statement before you sign (RBI). Rates track your score on secured loans too, as our guide to the home loan credit score shows, though the property gives the lender more comfort.
Banks vs NBFCs: Who Sets the CIBIL Score for Personal Loan Approval?
Each lender does, and the two groups behave differently.
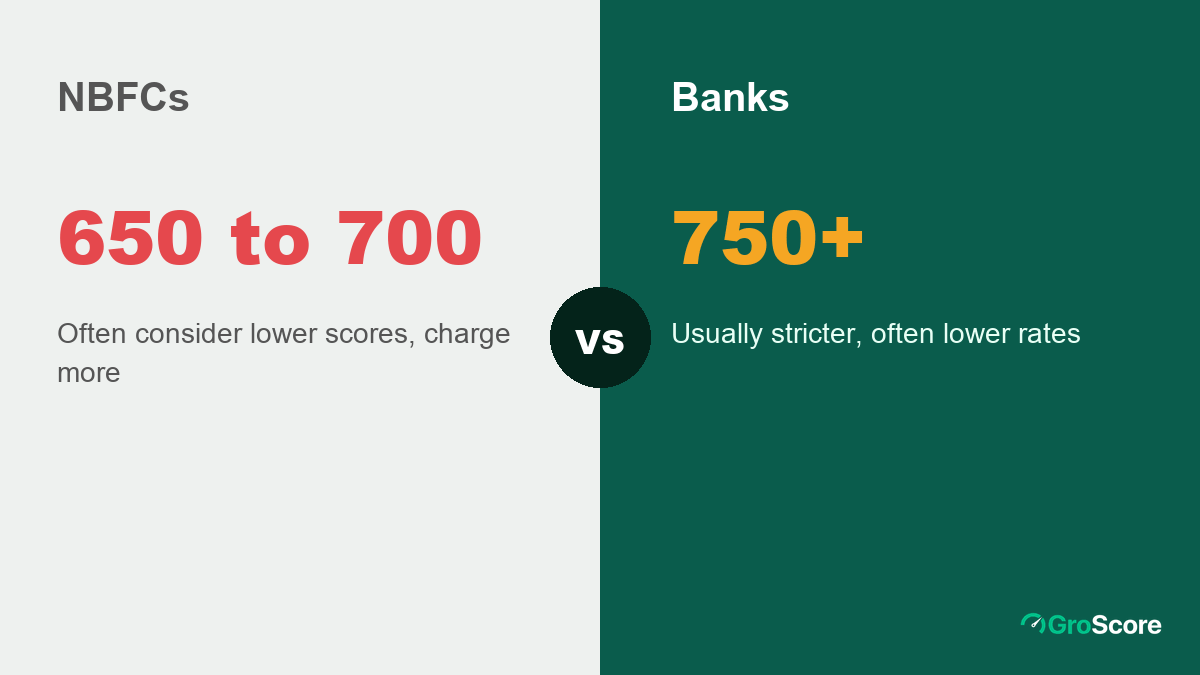
Same score, different doors.
Banks tend to be stricter. They usually prefer 750+, salaried applicants with steady employers and low existing EMIs. In return, their rates are often lower. If you already hold a salary account, check your bank app for a pre-approved offer before you apply anywhere else.
NBFCs (non-banking financial companies) often consider scores in the 650 to 700 range, and some go lower. They price that risk into the rate and the processing fee.
Whichever you choose, check it's regulated. Banks are licensed by the RBI. For an NBFC, look it up on the RBI's list of registered NBFCs. For a loan app, check the RBI's directory of digital lending apps, live on the RBI website since July 2025, and see which regulated lender actually funds the loan.
Can You Get a Personal Loan With a 650 Credit Score?
Sometimes, yes. A 650 credit score personal loan is usually an NBFC conversation, not a bank one, and loans for 650 credit score borrowers tend to be smaller. What tips it your way:
- a steady salary, credited to a bank account every month
- few existing EMIs
- no late payments in the last year
- one or two applications, not six
What you'll likely give up is price and size. The rate is higher, and the amount may be smaller than you asked for. Compare that with what a 750 credit score usually gets you.
Here's the honest question to ask first: why is the score 650? A one-off late payment from two years ago and a card maxed out today are very different problems. The second one you can fix before you apply.
Is a Personal Loan at a 600 Credit Score Possible?
If you're looking up a personal loan 600 credit score holders can get, here's the honest answer: unsecured approval from a regulated lender is hard. That's not a judgement on you. It's how lenders read the risk. Your realistic options look different:
- A secured loan. A gold loan or a loan against an FD leans on the security, not mainly the score.
- A co-applicant with a strong score and income.
- A smaller amount from an NBFC, repaid on time, to rebuild your record.
Our guide to a personal loan with a low CIBIL score walks through each option, what it costs, and the scams aimed at borrowers in this band.
What Else Decides Your Personal Loan?
Your score gets you past the first filter. Then lenders look at the rest of the file.
FOIR. Your fixed obligation to income ratio is the share of monthly income already going to EMIs. For example, earn ₹50,000 and pay ₹15,000 in EMIs, and your FOIR is 30%. Each lender sets its own ceiling, and the RBI leaves that call to the lender's own credit policy.
Income and employer. Salary level, how long you've been in the job and the employer's profile all count.
Recent enquiries. Every application adds a hard enquiry. Several in a few weeks reads as credit hunger. Our explainer on hard vs soft enquiries shows how they show up on your report.
What's in the report. A "settled" or "written-off" status, even on an old card, can matter more than the score itself.
What Would a Credit Coach Fix Before You Apply?
Here's an illustrative example. For instance, say Karan, 27, wants a ₹3 lakh personal loan. His Equifax score is 688. Arjun, GroScore's credit coach, reads the report with him and flags three things, in this order:
- Card utilisation at 82% (an indicative figure for this example). He can pay it down before the next statement date. Of everything on his report, this can move soonest.
- A wrongly reported late payment on a phone EMI he paid on time. If he has proof, it's a genuine error, and he can raise a dispute with the bureau.
- Four loan enquiries in a month from clicking "check eligibility" buttons. Nothing to fix now. The advice: stop applying until the first two items are sorted.
Why this order? GroScore's guidance is to keep card use under 30% of the limit (groscore.in, retrieved 2026-10-05), and a card balance updates with every statement. The error fix takes longer, and the enquiries simply have to age.
None of this can guarantee a loan, and no app can remove accurate late payments early. It makes sure the lender sees Karan's real record, not a messy one.
How to Spot a Fake Personal Loan Offer
People searching for a personal loan get targeted, especially with a fair or low score. Learn the signs.
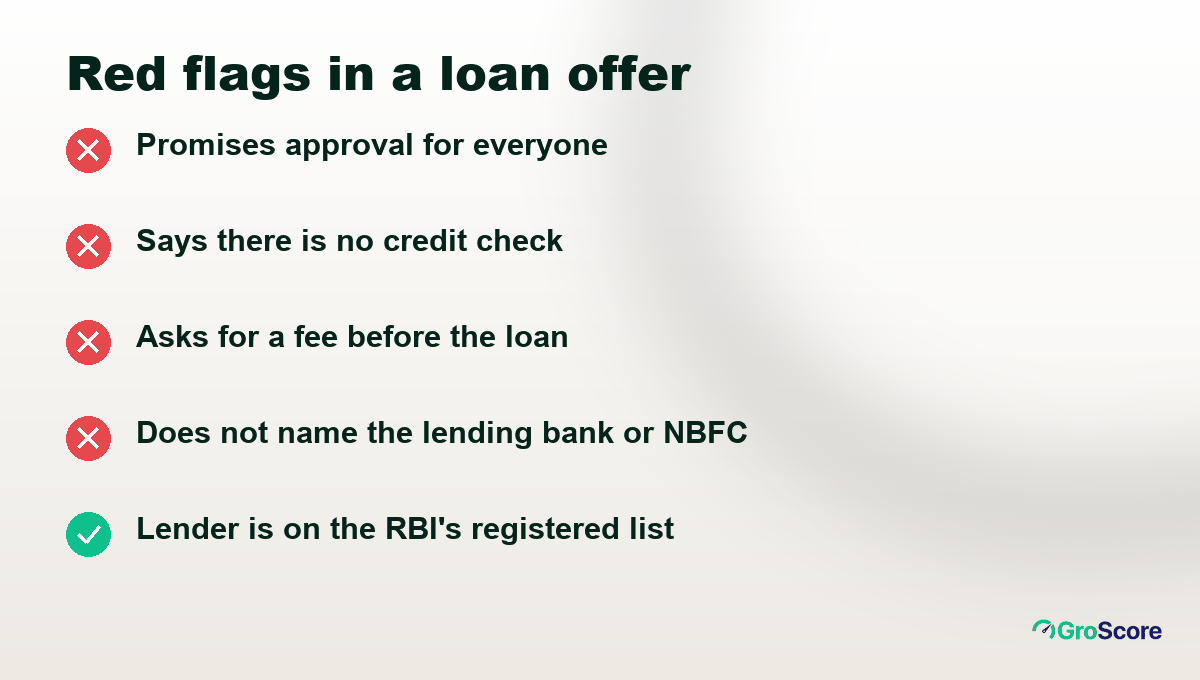
If an offer ticks any red box, walk away.
- "Guaranteed approval" or "no CIBIL check". Both are a myth. Every regulated lender checks a bureau report.
- An upfront fee to "release" or "unlock" the loan, paid to a personal UPI ID.
- No named lender. A real app tells you which bank or NBFC is lending.
- Access to your contacts and photos that has nothing to do with the loan.
A genuine instant loan still comes from a named, RBI-regulated lender that checks your report, however fast the app feels. Report an unauthorised lender on the RBI's Sachet portal. If a regulated lender hasn't resolved your complaint, escalate to the RBI's Complaint Management System at cms.rbi.org.in.
Frequently Asked Questions
What is the minimum CIBIL score for a personal loan?
There's no RBI-set minimum CIBIL score for personal loan approval. Most banks look for around 750 or above, while some NBFCs consider 650 to 700 at higher rates. Treat these as indicative and check the lender's own criteria before you apply.
Can I get a personal loan with a 650 CIBIL score?
Possibly, mostly from NBFCs, and usually at a higher rate or for a smaller amount. A steady salary, low existing EMIs and no recent late payments help. Fixing a high card balance first can make a real difference to how your report reads.
How much lower is the interest rate at 750+?
The gap depends on the lender, so there's no fixed number. For example, on an illustrative ₹5 lakh, five-year loan, the difference between 11% and 18% is ₹1,826 a month and about ₹1.1 lakh in total interest. Compare the APR in each lender's Key Fact Statement, which RBI rules require.
Do NBFCs approve personal loans at lower scores?
Many NBFCs do consider lower scores than banks, and they charge more for it. Check that the NBFC appears on the RBI's list of registered NBFCs, and read the processing fee and APR before you sign.
The Bottom Line
Aim for 750+ if you want a personal loan at a good rate. At 650 to 749, a personal loan for fair credit is still possible, mostly with NBFCs, so shop carefully and compare APRs. Below that, look at secured options and clean up your report first. Whatever your score, apply to one or two lenders, not ten, and never pay a fee to "unlock" a loan. If your score needs work first, start with our guide on how to improve your credit score.
Disclaimer
This article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
