650 Credit Score: Is It Good? What 600-699 Means for Loans
Fair, not bad. What a 650 unlocks, what it costs you on a loan, and the three fixes that usually move it first.

A 650 credit score is fair, not good. On GroScore's guidance it sits in the 600 to 749 band, 100 points below the 750 line. You can still get credit, mostly from NBFCs and on secured products, but usually at a higher rate and with closer checks on income. Your first target is 700.
Key TakeawaysGroScore's guidance treats 600 to 749 as fair and below 600 as poor (groscore.in). A 650 is fair, 100 points below good.At 650, secured options like a gold loan, a loan against an FD or an FD-backed card are usually easier to get than an unsecured loan.On a ₹2 lakh, three-year loan, an illustrative rate of 22% instead of 14% costs about ₹28,900 more in interest (October 2026 example, not an offer).High card use and recent applications are often the quickest things to fix. GroScore suggests keeping card use under 30% (groscore.in).
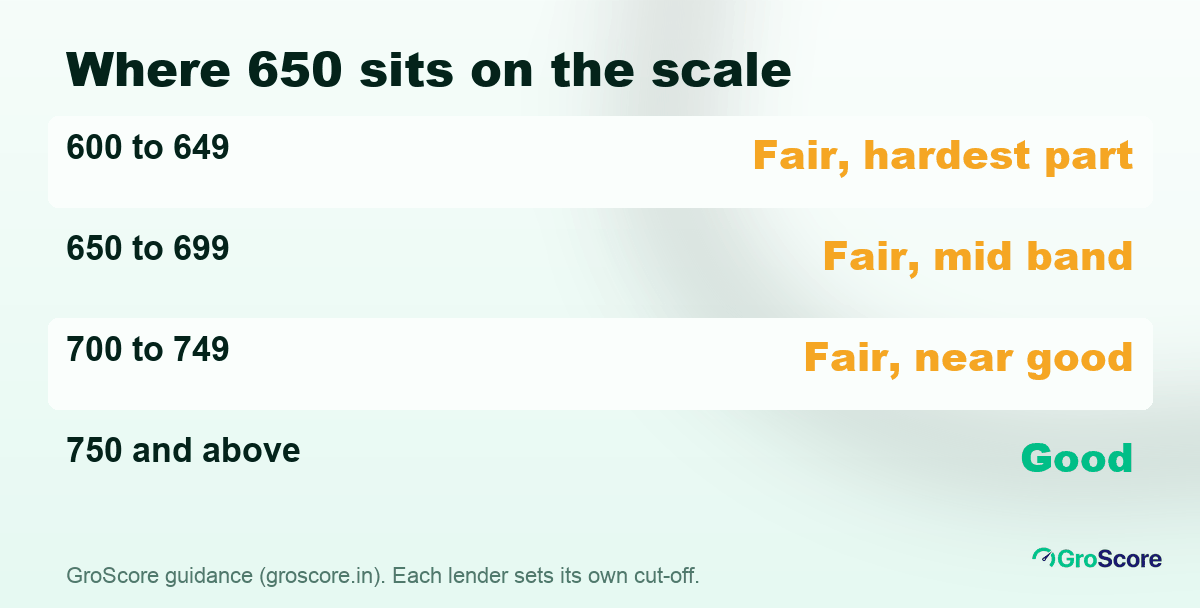
The fair band covers 150 points, and lenders notice where in it you sit.
Is 650 a Good CIBIL Score? Where 600 to 699 Sits
A 650 isn't good yet. It's a fair credit score: lenders will talk to you, but they'll price for the risk. If you want the basics first, our credit score guide explains the whole 300 to 900 scale.
Inside the 600 to 699 CIBIL score range, the two halves get treated a little differently.
| Score | What usually happens (indicative) |
|---|---|
| 600 to 649 | Unsecured approval is hard. Secured options or a co-applicant work better. |
| 650 to 699 | Mostly NBFCs for unsecured loans. Expect a higher rate and closer checks on income. |
Indicative, based on GroScore's guidance bands (groscore.in), October 2026. These aren't lender-published cut-offs. Actual offers vary by lender, income and credit profile.
CIBIL is one of four RBI-registered credit bureaus. Equifax, Experian and CRIF are the others, and each calculates its own score. So is 650 a good CIBIL score at every bureau? It's fair at all of them, but your exact number may differ by a few points from one to the next. Our explainer on what a CIBIL score is covers how it compares with the other bureau scores.
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender, and the score it shows is your Equifax score, not a CIBIL score.
What Can You Get With a 650 Credit Score?
You can get more than most people think, if you pick the right product. Here's how each one tends to look at 650.
| Product | At 650 (indicative) |
|---|---|
| Personal loan | Possible, mostly from NBFCs, at a higher rate and often a smaller amount |
| Credit card | An FD-backed or secured card is the realistic start; some entry-level cards may consider you |
| Car loan | Often possible, since the car secures it; a bigger down payment helps |
| Home loan | Some lenders consider it, usually at a higher rate |
| Gold loan or loan against FD | The security matters more than the score |
Indicative, not lender-published, October 2026. Actual offers vary by lender, income and credit profile.
A loan for a 650 credit score is mostly a question of where you apply. Our page on the personal loan credit score lenders look for sets out the indicative lines by band.
For credit cards for a 650 credit score, an FD-backed card is often the cleanest route. You open a fixed deposit, the bank issues a card against it, and on-time payments build your record. None of these options is guaranteed. Lenders decide on their own criteria, and income and existing EMIs count as much as the score.
What Does a 650 Score Cost You on a Loan?
Mostly it costs you interest. Here's an illustrative example of the interest rate at 650 compared with a better score, with only the rate changing.
Take a ₹2 lakh personal loan over three years. Say one borrower is offered 14% a year and another 22%. These are illustrative figures for October 2026, not offers.
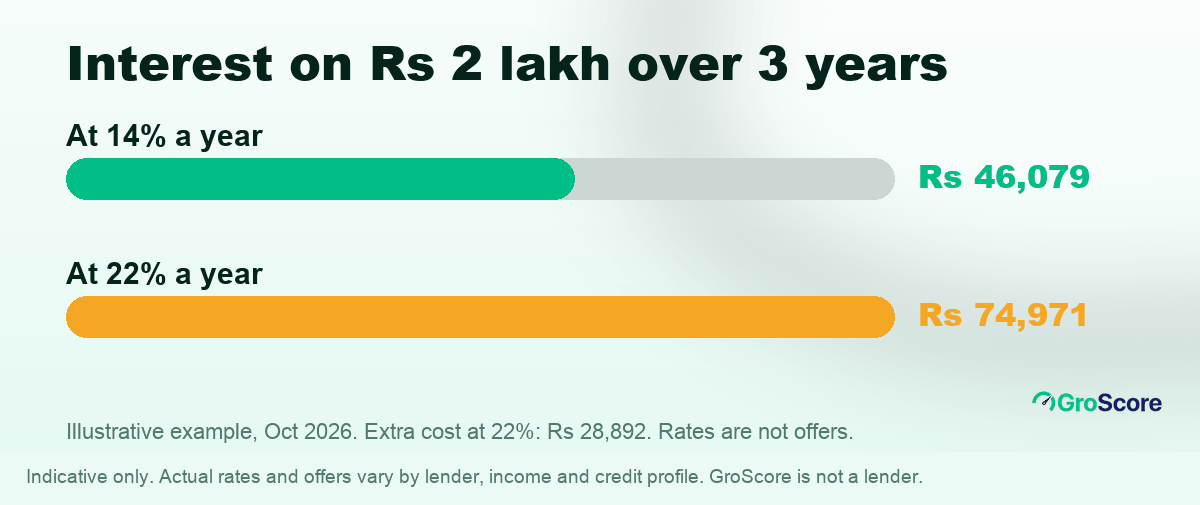
Illustrative example, October 2026: the same loan at two rates.
At 14%, the EMI works out to ₹6,836 and total interest to ₹46,079. At 22%, the EMI rises to ₹7,638 and interest to ₹74,971. That's ₹28,892 more for the same ₹2 lakh, worked out with the standard EMI formula (illustrative, October 2026). Actual offers vary by lender, income and credit profile.
So what should you do? If the need can wait two or three months, fixing one or two items first may change the offer. If it can't, a secured option often costs less than an unsecured loan at a fair-band rate. Longer term, the cheapest fix is climbing toward a good CIBIL score, where rates usually get better.
How Do You Borrow Safely With a Fair Score?
Fake loan apps often target borrowers with fair or low scores. A few checks keep you safe.
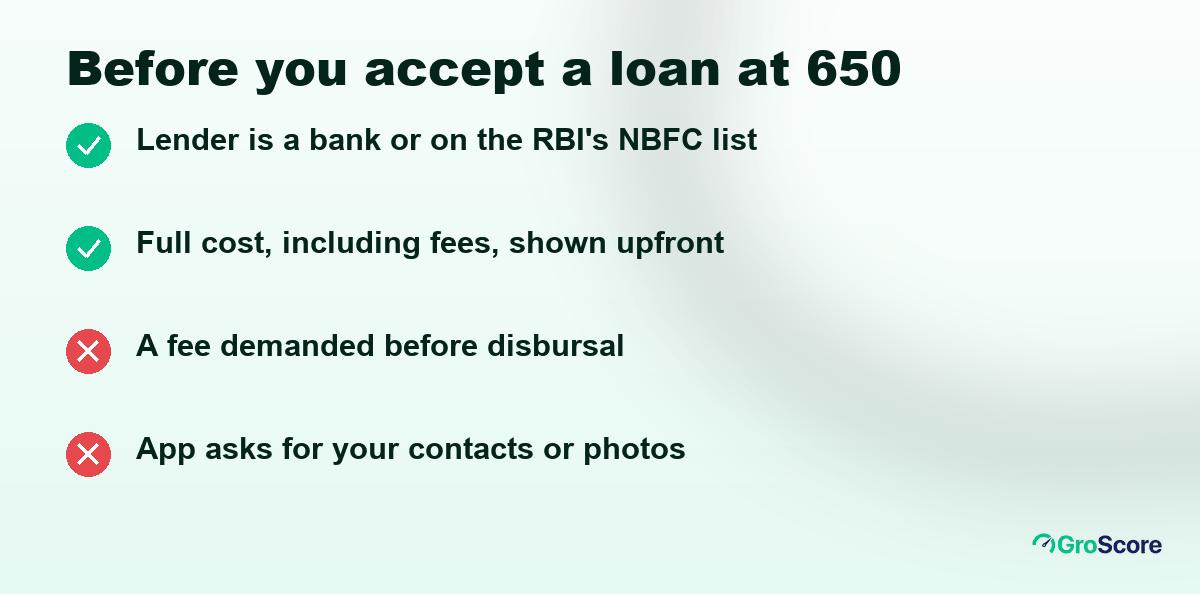
Four checks before you accept any loan offer.
- Check that the lender is a bank or appears on the RBI's list of registered NBFCs. A loan app should name its lending partner.
- Read the full cost, including the processing fee, before you sign.
- Never pay a fee before the money reaches you. Regulated lenders usually deduct any processing fee from the loan amount instead.
- Refuse any app that wants access to your contacts or photos.
If something feels wrong, you can report it on the RBI's Sachet portal, sachet.rbi.org.in.
What Usually Pulls a Score Into the 600s?
A score in the 600s rarely comes from one big disaster. It usually reflects a few mid-sized problems stacked together:
- One or two late payments in the last year or two. GroScore says a single missed EMI can cost 50 to 100 points (groscore.in).
- High card use, often above 50% of the limit.
- Several applications in a short period, often from shopping across loan apps.
- A settled account, where the lender accepted less than the full amount.
If your card use is above 50%, start there. For a deeper look at causes, see why your credit score is low.
What Would a Coach Flag at 648?
Here's an illustrative example, not a real customer. Sana, 26, has a 648 credit score. She was declined for a personal loan last month and wants to know what to fix. Arjun, GroScore's credit coach, reads her report and ranks three items:
- Card use of 85%. She has one card with a ₹50,000 limit and a ₹42,500 balance. GroScore suggests keeping card use under 30% (groscore.in, retrieved 2026-10-05). That means a balance of ₹15,000 or less, so she'd need to pay down ₹27,500. It's the fastest lever she has.
- Four enquiries in three months. She applied through several loan apps after the first rejection. Each one added a hard enquiry. The fix is to stop applying until the rest of the report improves.
- Two DPDs of 30 in the last year. Both are card bills paid a month late. They're accurate, so they stay on her credit history. Setting up autopay for at least the minimum due stops a third one.
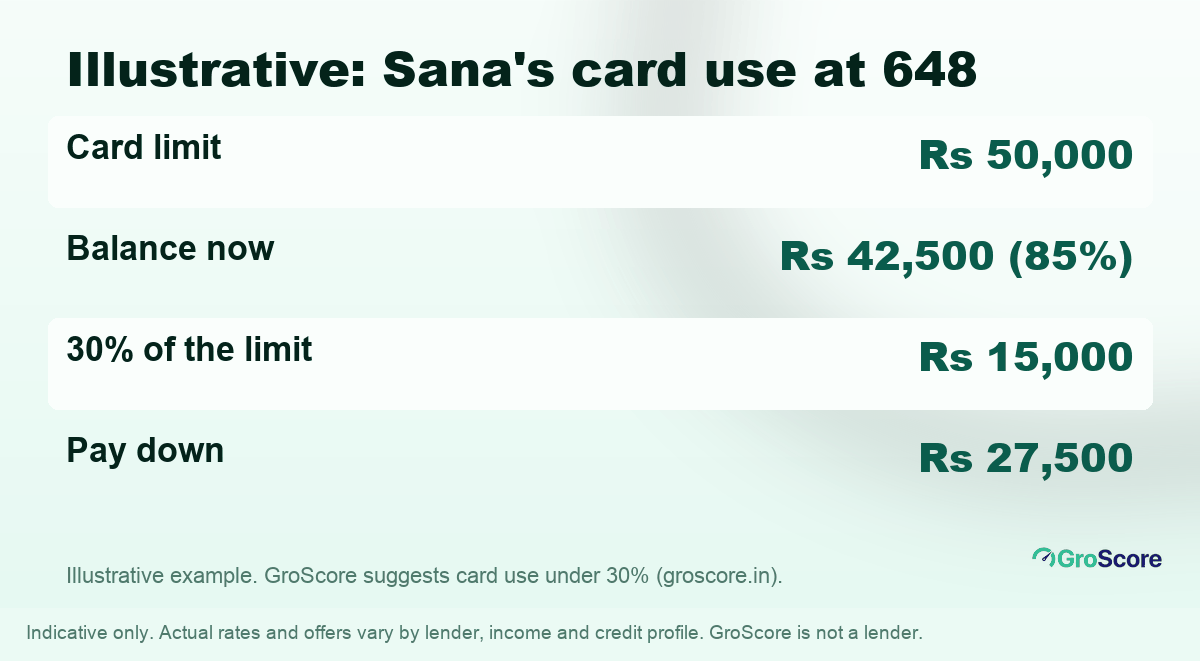
Illustrative example: the arithmetic behind Sana's first fix.
Notice that Arjun doesn't suggest a new card or another application. At 648, more credit isn't the answer. Less use of the credit she has is.
How Long Does It Take to Go From 650 to 750?
The timeline depends entirely on what's on your report. GroScore's guidance says moving from 600 to 750 usually takes six to twelve months (groscore.in). Nobody can promise a number of points or a date.
Aim for 700 first. Utilisation and enquiries can change within a few statement cycles. Late payments fade more slowly, as on-time months pile up.
Once you're past 700, the conversation with lenders shifts. Here's what a 700-749 score means for the same loans.
Frequently Asked Questions
Is 650 a good CIBIL score?
A 650 is fair, not good. GroScore's guidance puts it in the 600 to 749 band. Lenders may still approve you, often at a higher rate, and many prefer secured loans at this level.
Can I get a personal loan with a 650 credit score?
You may be able to, mostly from NBFCs, at a higher rate and possibly a smaller amount. Check that the lender is a bank or an RBI-registered NBFC, and never pay a fee before disbursal.
Will a bank give me a credit card at 650?
Some banks may offer an entry-level card, but an FD-backed card is the more reliable route at 650. It builds a repayment record while your score recovers.
How long does it take to go from 650 to 750?
GroScore's guidance says going from 600 to 750 usually takes six to twelve months, but it depends on your report. Lowering card use and pausing applications usually show results soonest.
What usually pulls a score into the 600s?
Usually a mix of things: a late payment or two, high card use, several recent applications or a settled account. Your credit report shows which ones apply to you.
The Bottom Line
A 650 credit score keeps doors open, just not the cheapest ones. Borrow only what you need, prefer secured options, and check every lender against the RBI's list. Then work on the two fixes you control this month: card use, ideally under 30%, and applications. The 700s are usually closer than they look. Whether an 800 credit score is worth chasing is a question for later.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
