Instant Loan Without Documents: What KYC You Still Need
Paperless isn't document-free. Here's the KYC every genuine lender still needs, the routes with the least paperwork, and why 'no KYC' means scam.

An instant loan without documents usually means a paperless loan, not a loan with no checks. You won't upload photocopies, but every RBI-regulated lender still has to verify your identity (KYC), pull your credit report and record your age, occupation and income before lending. The least paperwork comes from a pre-approved offer with your own bank, or a lender that can fetch your existing KYC record.
Key TakeawaysKYC is mandatory for every RBI-regulated lender. "No KYC" loan offers are a scam signal, not a shortcut (RBI).RBI's Digital Lending Directions (May 2025) require lenders to record at least your age, occupation and income before lending (RBI).If you already have a Central KYC (CKYC) record, a lender can retrieve it instead of asking for the same documents again (RBI).Every digital loan has a cooling-off period of at least one day, when you can exit without a penalty (RBI).Verify only by Aadhaar OTP and RBI's KYC rules cap term loans at Rs 60,000 a year until full KYC is done (RBI).
Paperless still means verified.
What Does "Without Documents" Actually Mean?
"Without documents" means you don't carry paper to a branch. That's all it means.
Most instant personal loans without documents work like this. You type your PAN, approve an Aadhaar OTP or share an Aadhaar XML file, take a selfie or join a short video call, and consent to the lender reading your credit report. Each of those steps is a document check. It just happens on your phone, in minutes, which is why lenders prefer the term instant paperless loan.
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. It doesn't give, approve or disburse loans, and its number is your Equifax score, not a CIBIL score.
So when an ad promises an instant loan without documents online, ask one question: which checks does it still run? A genuine lender will answer it plainly. For how the whole process fits together, read how instant loans work from application to disbursal.
Is an Instant Loan Without KYC Legal in India?
No. An instant loan without KYC isn't something a regulated lender can offer.
RBI's KYC Master Direction requires every bank and NBFC to identify a customer before opening an account or lending, using an officially valid document (OVD) plus a PAN or Form 60 (RBI, as consolidated into RBI's KYC Directions in November 2025). Officially valid documents include a passport, driving licence, proof of possession of an Aadhaar number, voter ID, NREGA job card or a National Population Register letter.
So why do "instant loan without KYC" searches turn up so many apps? Because the phrase works as bait. An app that genuinely skips KYC is either not a regulated lender or is breaking the rules. Either way, you lose the protections that come with a regulated loan: a Key Fact Statement, a grievance officer, and a route to the RBI Ombudsman.
KYC protects you as much as the lender.
The bait often hides something worse. Fake apps ask for an "insurance" or "file" fee before any money arrives, then vanish. Our guide to fake loan apps shows how to check an app against the RBI's lists.
What Is the Minimum KYC a Lender Needs?
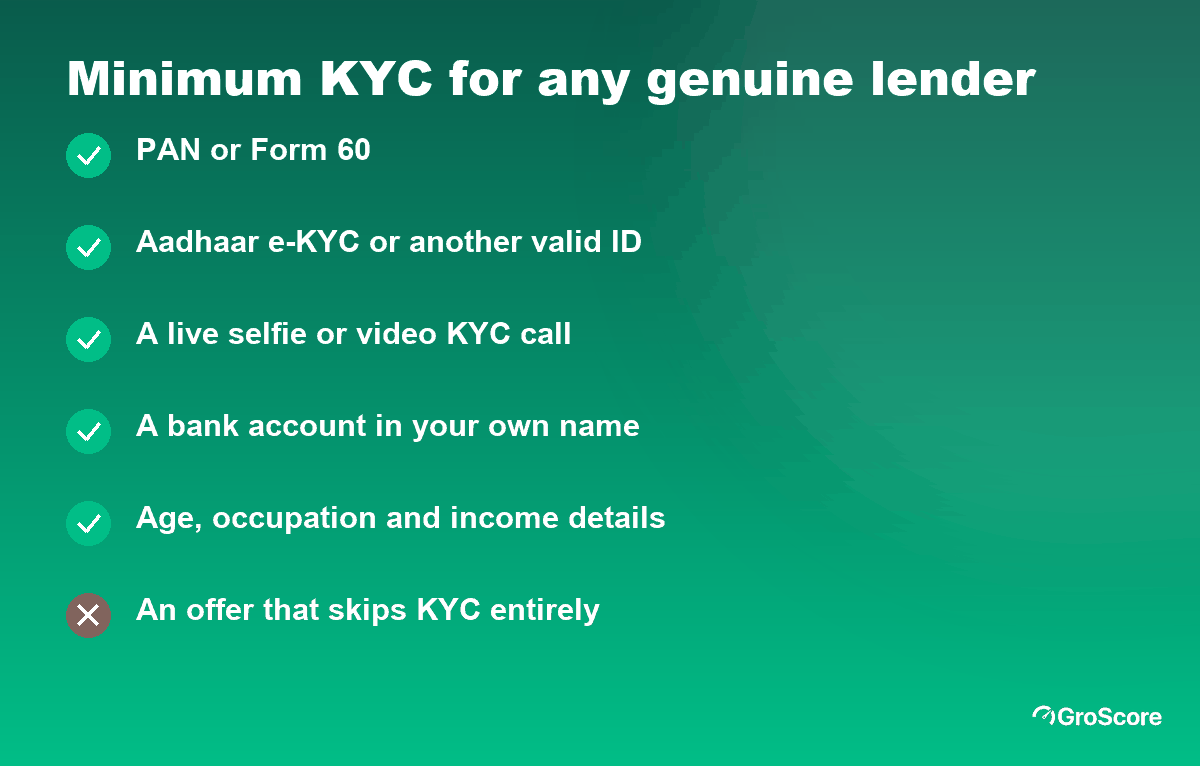
Lenders differ in the details, but the floor looks like this:
- PAN or Form 60. RBI's KYC rules require one, and PAN is also how the lender pulls your credit report.
- Proof of identity and address. Aadhaar e-KYC is the usual route, though any officially valid document counts.
- A live photo or video check. Lenders use a selfie with liveness detection, or a video KYC call with an official.
- A bank account in your name. RBI's digital lending rules say the money must go straight into your account.
- Your economic profile. The Digital Lending Directions require at least your age, occupation and income details before a loan (RBI).
The income check surprises people. "No documents" never means "no income check". If you can't show a salary slip, bank statements or ITR can usually stand in.
One more limit applies if you verify only by Aadhaar OTP. RBI's KYC rules cap term loans on such an account at Rs 60,000 a year until full KYC is done. Our Aadhaar card loan guide explains how that cap works in practice.
Which Loans Need the Least Paperwork?
Some routes really are close to paperless, because the lender already knows you or can fetch what it needs.
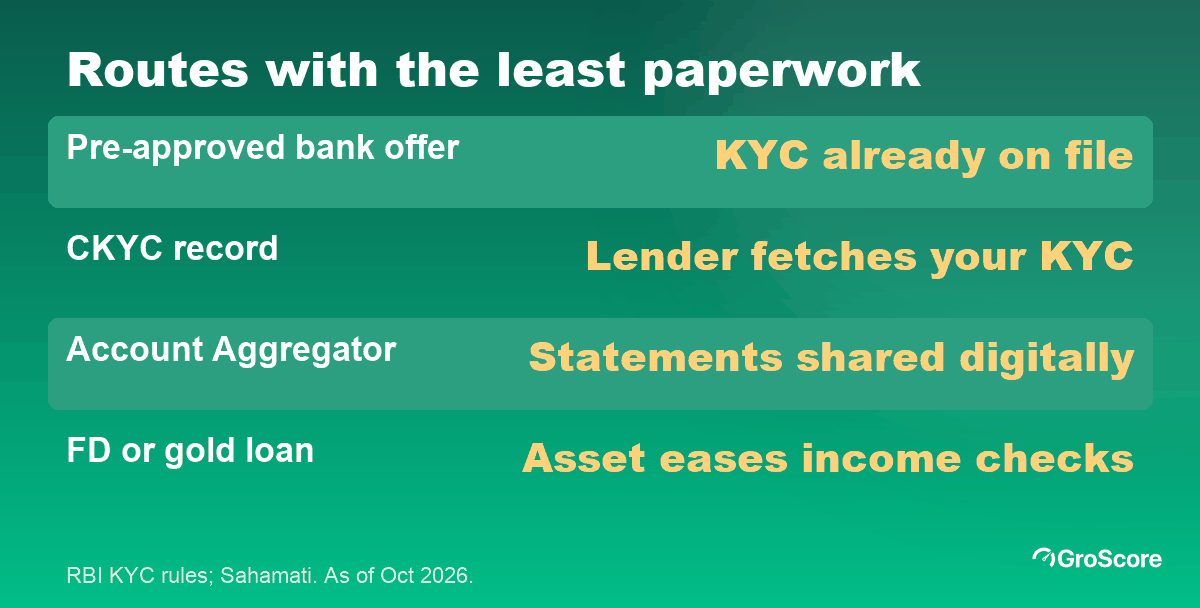
| Route | Why it needs less paperwork | Watch for |
|---|---|---|
| Pre-approved offer from your bank | KYC and account history are already on file | Offer can change after a fresh credit check |
| Lender that uses your CKYC record | It retrieves your existing KYC from the central registry | You may still need to refresh outdated details |
| Bank statements via Account Aggregator | You share statements digitally, with consent, instead of PDFs | Consent covers a set period; read what you share |
| Loan against an FD or gold | The asset backs the loan, so income checks are lighter | KYC still applies; you can lose the asset if you default |
The CKYC route deserves more attention than it gets. Once a regulated entity uploads your KYC to the Central KYC Records Registry, you get a 14-digit KYC identifier. Under RBI's KYC rules, a lender that retrieves your record shouldn't ask for the same documents again, unless your details changed, the record is incomplete or it needs more checks (RBI).
Account Aggregators are RBI-regulated NBFCs that act as consent managers. They pass your bank data to a lender only with your consent, and Sahamati, the industry body, says they aren't allowed to store, process or sell it (Sahamati, retrieved 2026-10-06).
Less paperwork comes from data the lender already trusts.
What Would a Credit Coach Check Before You Apply?
Here's an illustrative example. Say Ravi, 26, a delivery partner, needs Rs 20,000 for a bike repair and keeps seeing ads for an instant cash loan in 1 hour without documents. Arjun, GroScore's credit coach, reads his Equifax report with him and flags three things, in this order:
- A name mismatch. His PAN says "Ravi Kumar S" and his bank account says "Ravikumar". Small KYC gaps like this are the most common reason a paperless application stalls. Fixing it first saves days.
- Three loan enquiries in two weeks, all from apps that ran a check and never lent. Each one was a hard enquiry. He should stop and pick one lender he has verified.
- An old phone EMI shown as open. He closed it last year. If the lender never reported the closure, that's an error he can dispute.
Then Arjun walks him through the exit option, because new borrowers rarely know it exists. Every digital loan comes with a cooling-off period of at least one day (RBI). Inside it, you can leave by repaying the principal and the proportionate APR (annual percentage rate), with no penalty.
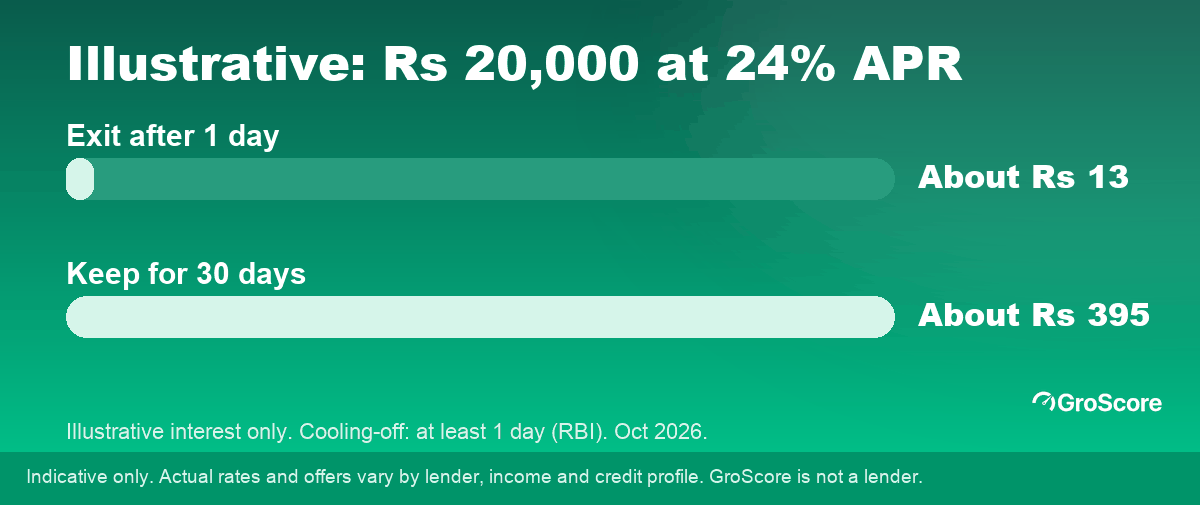
Illustrative example: the cooling-off exit is cheap if you change your mind.
Here's the arithmetic behind RBI's cooling-off rule. On Rs 20,000 at an illustrative 24% APR, one day's interest is 20,000 × 24% ÷ 365, or about Rs 13. Keep the loan 30 days and it's about Rs 395. These figures are indicative, as of October 2026, and ignore any fee the Key Fact Statement says is non-refundable. Actual offers vary by lender, income and credit profile.
Ravi's income arrives as weekly platform payouts, so he has no salary slip either. Bank statements can show that income, and our guide to a loan without income proof covers each substitute. Arjun can't promise Ravi a loan; the lender decides. GroScore can show which lenders' criteria a profile clears, across 100+ loans and credit cards from 60+ banks and NBFCs (groscore.in).
Red Flags in Instant Loan Without Documents Offers
A genuine paperless loan and a scam can look identical on a phone screen. The difference shows up in what they ask for.
- The app promises an urgent loan without documents, KYC or a credit check.
- It asks you to pay a fee before any money arrives, often to a personal UPI ID.
- It won't name the RBI-regulated bank or NBFC that lends.
- It wants your contacts, photos or call logs. RBI's rules bar lending apps from these and allow only one-time camera, microphone or location access for KYC (RBI).
- The money arrives from someone else's account instead of the lender's.
Before you share anything, find the lender's name and search for it on the RBI's list of registered NBFCs. Then look for the app in the RBI's directory of digital lending apps. Already paid a fee and got nothing? Stop paying, keep the screenshots, call the cybercrime helpline on 1930 and report the app on the RBI's Sachet portal.
If an offer looks genuine, compare its APR before you accept. Our guide to the real cost of an instant loan shows how fees change it.
Frequently Asked Questions
Can I get a loan without any documents?
Not from a regulated lender. You may not upload any paper, but the lender still verifies your PAN or Form 60, your identity through Aadhaar e-KYC or another valid document, a live photo or video, your bank account and your credit report. Paperless and document-free aren't the same.
Is a loan without KYC legal in India?
No. RBI's KYC rules require every bank and NBFC to verify a customer before lending. An app offering an instant loan without KYC is either not a regulated lender or is breaking the rules, and you'd have little protection if something went wrong.
Which loan needs the least paperwork?
A pre-approved offer from a bank where you already hold an account usually needs the least, since your KYC is on file. Lenders that retrieve your CKYC record or read statements through an Account Aggregator also cut paperwork. Gold and FD loans need lighter income checks.
Can I get a loan without income proof as a freelancer?
Often, if your earnings land in a bank account. Lenders must still record your income, but bank statements, ITR or GST returns can replace a salary slip. The amount offered may be lower when income is irregular.
Does applying for a paperless loan affect my credit score?
Yes, in the same way as any loan application. The lender's check is a hard enquiry, so many applications in a short time can hurt. Checking your own score on GroScore is a soft enquiry and doesn't affect it.
The Bottom Line
An instant loan without documents is really a loan without paperwork, and that's a good thing when the lender is genuine. KYC, a credit check and an income check still happen. They just happen fast. Keep your PAN, bank and Aadhaar details matching, check your report before you apply, and walk away from anything that promises a loan with no KYC at all.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
