Aadhar Card Loan: Can You Get a Personal Loan on Aadhaar?
Aadhaar proves who you are. It doesn't prove you can repay. Here's what an Aadhaar loan really involves, and where the scams hide.

No lender gives a loan on your Aadhaar card alone. An aadhar card loan is an ordinary personal loan where Aadhaar handles the KYC step, proving who you are and where you live. Lenders still need your PAN, a bank account, a credit check and some sign that you can repay. If a lender verifies you only by Aadhaar OTP, RBI rules cap its term loans to you at Rs 60,000 a year.
Key TakeawaysAadhaar is an identity and address document. It says nothing about your income or repayment record.Under RBI's KYC rules, a loan account opened with Aadhaar OTP e-KYC alone allows term loans of up to Rs 60,000 a year, and only for one year unless full KYC follows (RBI).PIB Fact Check called a viral "Rs 3 lakh loan on Aadhaar" government scheme false in August 2026. No central scheme lends against Aadhaar alone (PIB).You can check every Aadhaar authentication from the last six months on the UIDAI website (UIDAI).
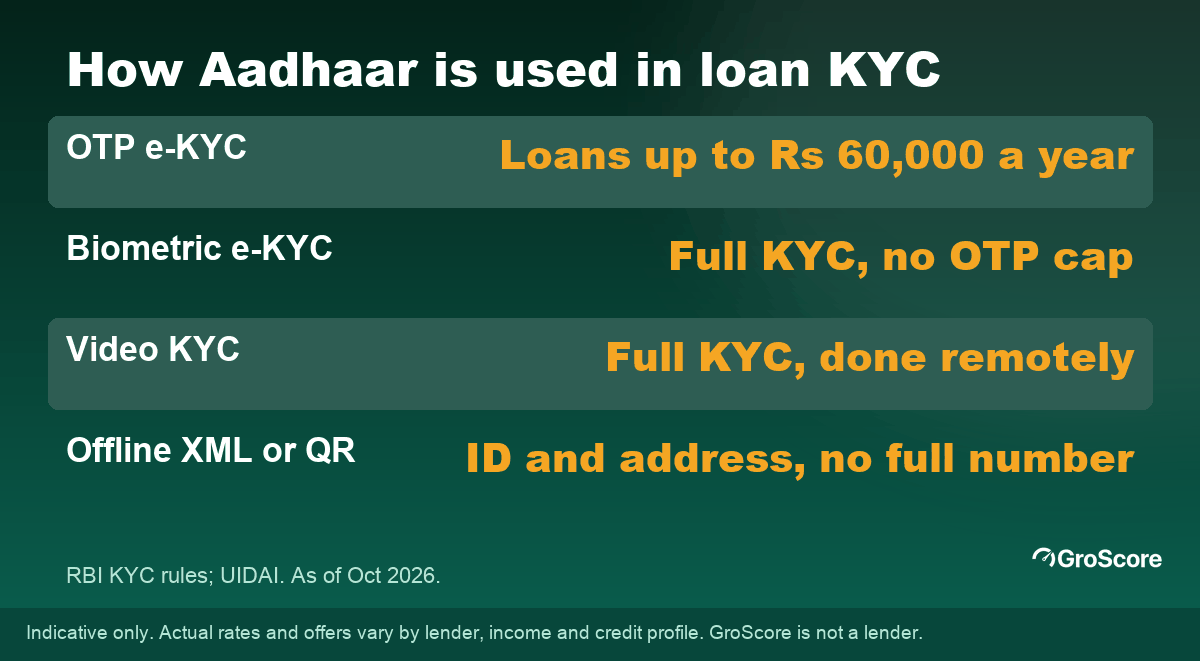
Aadhaar plays a different role depending on how the lender verifies you.
What Does Aadhaar Actually Do in a Loan Application?
Think of Aadhaar as the front door. It lets the lender confirm, in seconds, that you're a real person with a real address. That's KYC (know your customer), and every RBI-regulated lender must complete it before lending.
Here's the catch. Passing KYC only gets you in the door. The credit decision happens after it, and Aadhaar plays no part there.
Lenders can use Aadhaar in a few ways:
- OTP e-KYC. You type the OTP sent to your Aadhaar-linked mobile number, and the lender receives your name, address and photo from UIDAI.
- Biometric e-KYC. You give a fingerprint or face scan, usually at a branch or on an agent's device.
- Offline verification. You share a digitally signed Aadhaar XML file or QR code. UIDAI says the lender then gets a reference ID instead of your full Aadhaar number (UIDAI).
- Video KYC. You join a live video call with the lender's official and show your PAN.
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. It doesn't give, approve or disburse loans, and its number is your Equifax score, not a CIBIL score.
So when an ad offers an "aadhar card personal loan" or asks you to apply online for an aadhar loan, it means the KYC step is digital. It doesn't mean the lender skips everything else. For the full process, read how an instant personal loan works from application to disbursal.
Is There a Limit on Loans With Aadhaar OTP e-KYC?
Yes, and almost no lender's ad mentions it.
RBI's KYC Master Direction treats an Aadhaar OTP e-KYC account as a lower-assurance, non-face-to-face account. For loans, it sets three conditions (RBI, as updated in August 2025 and carried into RBI's consolidated KYC Directions of November 2025):
- Only term loans can be given, so overdrafts and credit lines aren't allowed.
- The total of term loans sanctioned can't exceed Rs 60,000 in a year (RBI).
- The account can't run beyond one year unless the lender completes full KYC, in person or through video KYC.
RBI's cap explains a pattern you may have noticed. Many apps offer small first loans, then ask for a video KYC call before they'll lend more. They're following the rules, not stalling. What does a lender still need when it asks for very little paperwork? Our guide to an instant loan without documents lists the minimum KYC.
If an app offers you Rs 3 lakh on an Aadhaar OTP alone, with no video call and no other checks, something is wrong.
What Else Do You Need Besides Aadhaar?
Every lender sets its own list, but these show up almost everywhere:
| What lenders ask for | Why they need it |
|---|---|
| PAN | RBI's KYC rules require a PAN or Form 60, and lenders use it to pull your credit report |
| Bank account in your name | The loan must be paid straight into your account under RBI digital lending rules |
| Credit report | Lenders check one or more of the four RBI-registered bureaus |
| Income signal | Salary credits, bank statements, ITR or GST returns |
| Mobile linked to Aadhaar | Needed for OTP e-KYC and loan alerts |
PAN matters more than people expect. It's the key bureaus use to match your credit history, which is why you can check your CIBIL score by PAN card but not by Aadhaar alone. No PAN at all? Some lenders accept Form 60 for KYC, though most personal loan products still want a PAN.
Aadhar Card Loan Amount: How Much Can You Get?
Aadhaar doesn't set the amount. Three other things do.
Your credit report. A clean repayment record opens bigger, cheaper offers. GroScore's guidance treats 750+ as good and below 600 as the zone where approvals get hard (groscore.in).
Your income and existing EMIs. Lenders look at FOIR (fixed obligations to income ratio), the share of your income already going to EMIs. If half your salary is spoken for, the offer shrinks. Self-employed or paid in cash? Our guide to a loan without income proof covers what you can show instead of a salary slip.
How the lender verified you. Under RBI's KYC rules, OTP-only KYC caps term loans at Rs 60,000 a year. Full KYC removes that cap, though not the lender's own limits.
Searches like "2000 loan on aadhar card", "aadhar card loan apply online" or "aadhar card loan 50000" are really asking how small or how large a first loan can be. Small loans of a few thousand rupees do exist, usually from app-based lenders. Short tenures make their fees expensive in annual terms, so read the APR (annual percentage rate) in the Key Fact Statement before you accept.
What Would a Credit Coach Flag Before You Apply?
Here's an illustrative example. Say Meena, 27, works in retail, earns Rs 22,000 a month and wants Rs 50,000 for a course. She found an aadhar card loan app online and plans to verify by OTP. Arjun, GroScore's credit coach, reads her Equifax report with her and flags three things, in order:
- The OTP cap. Rs 50,000 fits under the Rs 60,000 yearly limit that RBI sets for OTP-only KYC. But she already expects to need another Rs 20,000 in six months. That's Rs 70,000 in total, Rs 10,000 over the cap, unless she completes video KYC with that lender. Better to do full KYC now than get stuck later.
- Two loan enquiries this month. Each was a hard enquiry from an app she tried and then dropped. Applying everywhere looks like credit hunger, so she should pick one lender.
- A phone EMI marked 30 days late. It's accurate, so it can't be removed. More on-time payments will slowly outweigh it.
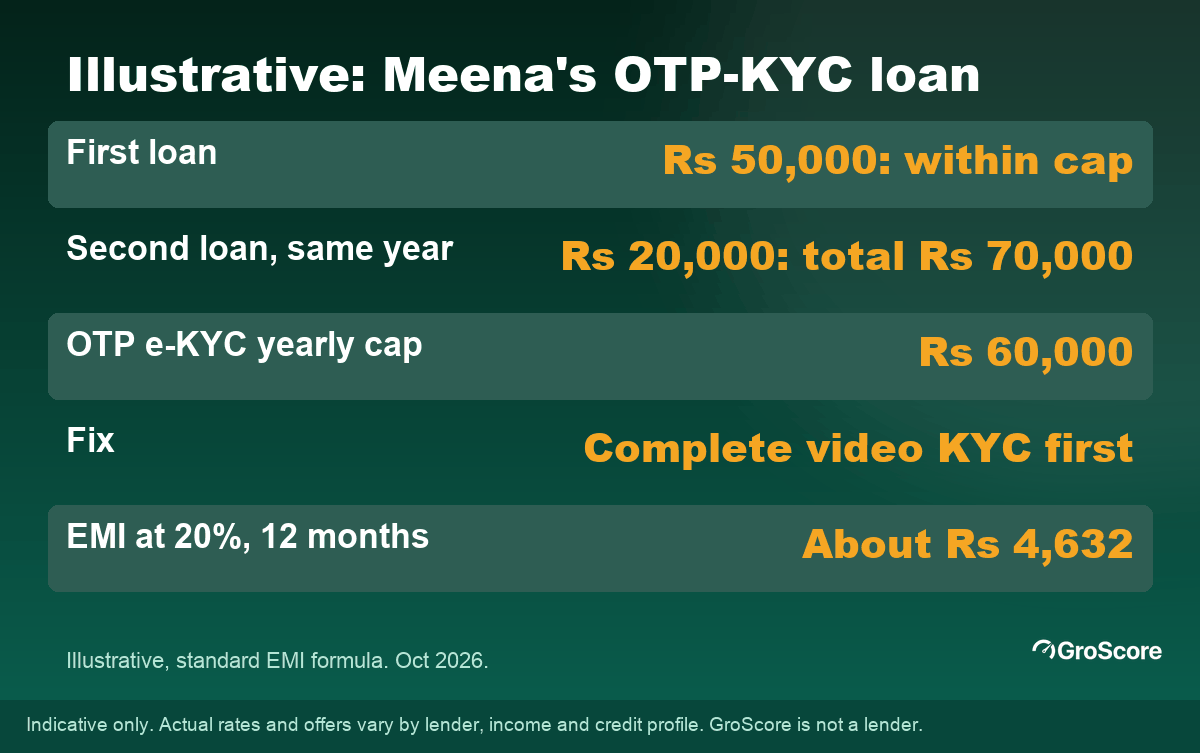
Illustrative example: the KYC route can limit a second loan.
Now the cost. At 20% a year over 12 months, a Rs 50,000 loan works out to an EMI of about Rs 4,632 and total interest of about Rs 5,581, before any processing fee. That EMI is about 21% of her Rs 22,000 income. These are illustrative figures from the standard EMI formula, as of October 2026, not offers. Actual offers vary by lender, income and credit profile.
Arjun can't promise Meena a loan. The lender decides. GroScore can show which lenders' criteria a profile clears, across 100+ loans and credit cards from 60+ banks and NBFCs (groscore.in).
Is There a Government Loan on Aadhaar Card?
No, not on Aadhaar alone.
Messages promising a "Pradhan Mantri" loan on your Aadhaar card keep circulating on WhatsApp and social media. In August 2026, PIB Fact Check said a viral claim of a Rs 3 lakh loan on Aadhaar under a "Prime Minister Loan Scheme" was false, adding that no such scheme is run by the central government (PIB Fact Check, retrieved 2026-10-06). In July 2026, it also called fake a letter that promised a Mudra loan in return for a Rs 350 "processing fee". MUDRA doesn't lend to individuals directly; it refinances banks and other lenders (PIB).
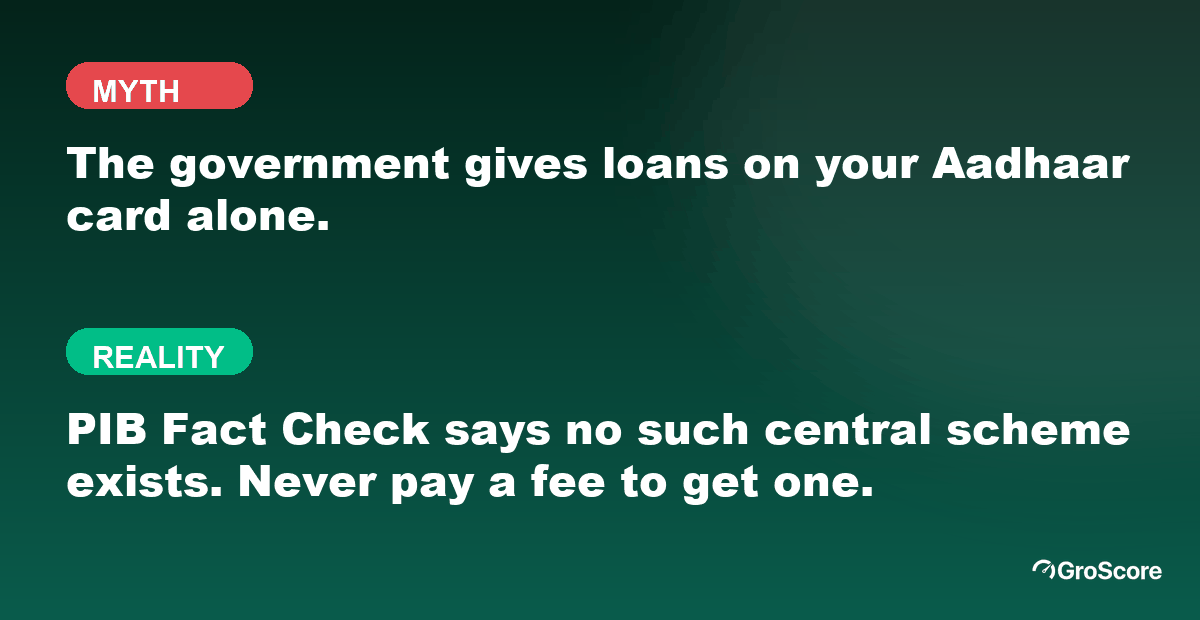
Real government-backed loans go through banks and full eligibility checks.
Genuine schemes do exist, but they run through banks and regulated lenders, with their own eligibility rules. As of October 2026, PIB advises checking any scheme on the government's myScheme portal before sharing details. If a message asks for a fee to "release" a government loan, it's a scam, every time.
Is It Safe to Share Your Aadhaar With Loan Apps?
Sharing Aadhaar can be safe with a genuine lender. The risk sits with apps that collect your Aadhaar and never lend, or lend on terms you'd never accept.
Before you share anything, find the bank or NBFC behind the app and search for it on the RBI's list of registered NBFCs. Then use what UIDAI already gives you:
- Masked Aadhaar. This copy hides the first eight digits and shows only the last four (UIDAI). RBI's KYC rules also ask lenders to have you black out the number where Aadhaar authentication isn't needed.
- Authentication history. On the UIDAI website or the mAadhaar app you can see every Aadhaar authentication from the last six months, up to 50 records at a time, with the agency's name (UIDAI).
- Biometric lock. Locking your fingerprints, iris and face stops anyone running a biometric authentication until you unlock it (UIDAI).
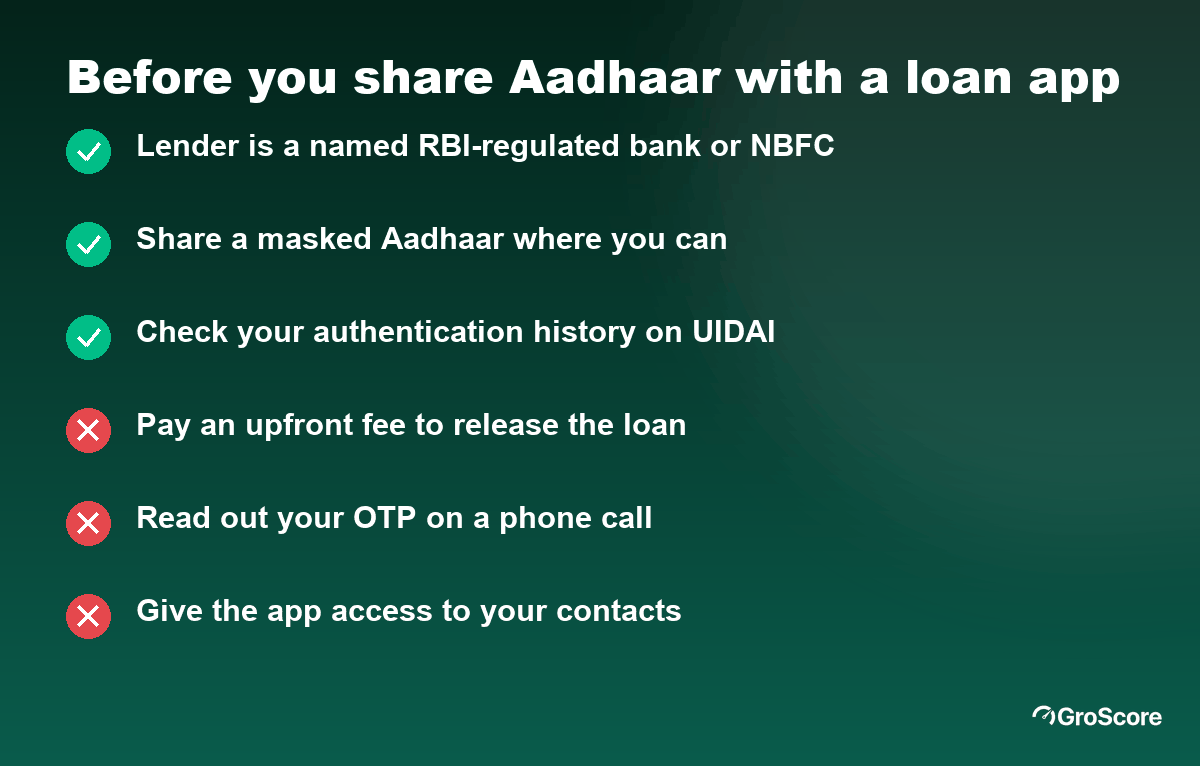
Your OTP is your consent. Treat it like a signature.
Spotted an authentication you don't recognise? Check your credit report too. A loan you never took is a sign of misuse, and errors like that can be disputed with the bureau. Already paid an upfront fee? Stop paying, keep the screenshots, call the cybercrime helpline on 1930 and report the app on the RBI's Sachet portal. Our step-by-step guide to fake loan apps covers each complaint route.
Frequently Asked Questions
Can I get a loan with only my Aadhaar card?
No regulated lender lends on Aadhaar alone. Aadhaar completes the KYC step, but lenders also need your PAN or Form 60, a bank account, a credit check and some proof that you can repay. An offer that asks for nothing but Aadhaar plus a fee is a scam warning.
How much loan can I get on Aadhaar?
Your credit report, income and existing EMIs decide the amount, not Aadhaar. One rule does apply: if a lender verifies you only by Aadhaar OTP, RBI's KYC rules cap its term loans at Rs 60,000 a year until you complete full or video KYC.
Is there a government loan on Aadhaar card?
No central scheme gives loans on Aadhaar alone. PIB Fact Check called a viral Rs 3 lakh Aadhaar loan claim false in August 2026, and a Rs 350 "Mudra processing fee" letter fake in July 2026. Real schemes run through banks with full checks.
Is it safe to share my Aadhaar with loan apps?
Sharing Aadhaar is reasonably safe with an RBI-regulated lender's app, after you verify the lender. Share a masked Aadhaar where the full number isn't needed, never read out an OTP on a phone call, and check your Aadhaar authentication history on the UIDAI website if something feels off.
Does an Aadhaar card loan affect my credit score?
Yes, like any loan. The lender pulls your report (a hard enquiry) and reports the loan to the bureaus, so on-time EMIs help and late ones hurt. Checking your own score is a soft enquiry and doesn't lower it.
The Bottom Line
An aadhar card loan isn't a special product. It's a normal loan with a faster KYC step. Aadhaar proves who you are; your credit report and income decide the rest. Verify the lender, expect a cap on OTP-only loans, and treat any "government loan on Aadhaar" message as fake until an official source says otherwise. Comparing lenders before you apply? See how an instant bank loan, NBFC or loan app differ on safety and cost.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
