Instant Loan 50000 to 5 Lakh: Eligibility and CIBIL Needed
A bigger loan isn't just a bigger number. Here's what lenders check at ₹50,000, ₹1 lakh, ₹2 lakh and ₹5 lakh, and how to work out what you can afford.

You can get an instant loan 50000 to 5 lakh from an RBI-regulated bank or NBFC if your credit report, income and KYC hold up. A credit score of 750 or more gives you the widest choice. The bigger the amount, the more a lender checks: past ₹60,000, Aadhaar OTP alone won't do for KYC, and your income has to carry the EMI.
Key TakeawaysA loan opened with only Aadhaar OTP-based e-KYC is capped at ₹60,000 of term loans a year. Larger amounts need video KYC or another full KYC route (RBI).Lenders size the loan to your income. Most look at FOIR, the share of your take-home pay already going to EMIs.Every digital loan comes with a Key Fact Statement showing the APR, and a cooling-off period of at least one day (RBI, May 2025)."₹50,000 without income proof and CIBIL" isn't something a regulated lender offers. Treat it as a scam signal.
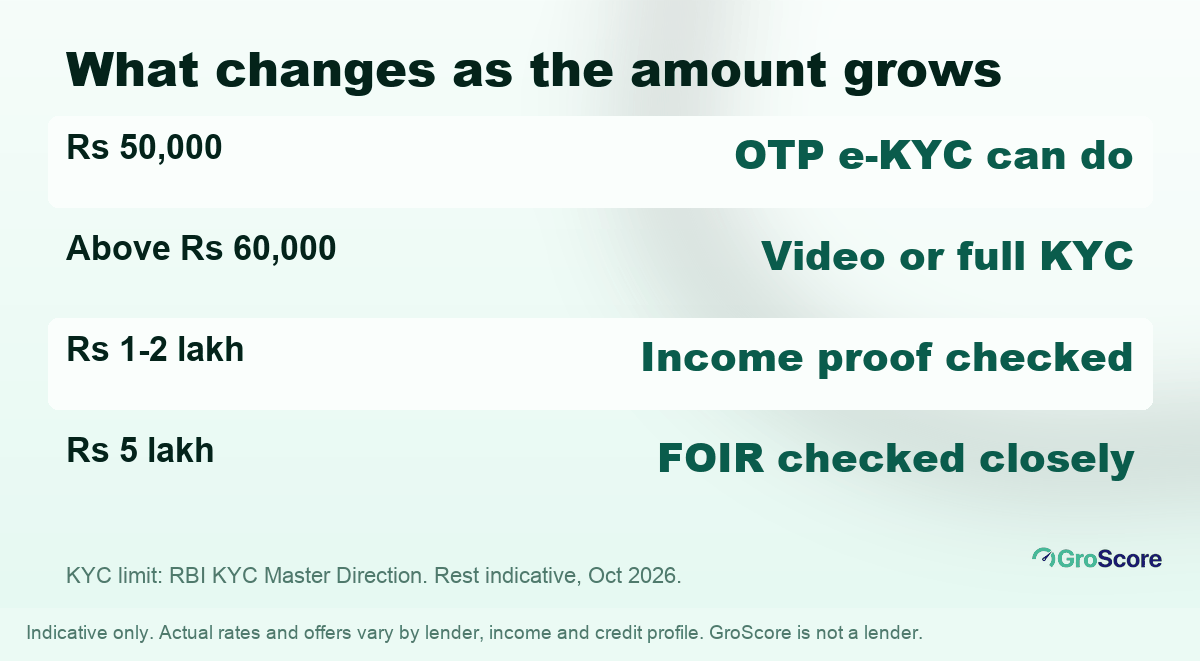
The checks grow with the amount, even when the app looks the same.
What Changes Between ₹50,000 and ₹5 Lakh?
On a loan app, a ₹50,000 request and a ₹5 lakh request look identical. Same form, same slider. Behind the screen, the checks differ.
| Amount | KYC usually needed | Income check | Typical tenure |
|---|---|---|---|
| ₹50,000 | Aadhaar OTP e-KYC can be enough | Bank statement or salary credits | 6 to 24 months |
| ₹1 lakh | Video KYC or other full KYC | Payslips or bank statements | 12 to 36 months |
| ₹2 lakh | Video KYC or other full KYC | Payslips, bank statements, sometimes ITR | 24 to 48 months |
| ₹5 lakh | Full KYC | Detailed income proof; FOIR checked closely | 36 to 60 months |
Indicative, as of October 2026. Actual offers vary by lender, income and credit profile.
The KYC line comes straight from the rulebook. Under the RBI's KYC Master Direction, an account opened only through Aadhaar OTP-based e-KYC, without meeting anyone, can carry term loans of no more than ₹60,000 in total in a year. Above that, the lender has to complete video KYC (V-CIP) or another full KYC route (RBI, as updated August 2025).
Above this line, expect a video KYC call.
That's why a ₹1 lakh instant loan often asks you to switch on your camera. It isn't the app being difficult. It's the rule.
Unsecured lending has also tightened. In November 2023, the RBI raised the risk weight on consumer credit, personal loans included, to 125% for banks and NBFCs (RBI). Lenders hold more capital against each unsecured rupee, so they're choosier with larger amounts.
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. It doesn't give, approve or disburse loans, and the number it shows is your Equifax score, not a CIBIL score.
New to how these loans work? Read our guide to the instant personal loan first. This page is about one question: what changes as the amount climbs.
"I Need 50,000 Rupees Loan Urgently": What Are My Options?
Start where you've already passed some checks.
- A pre-approved offer from your own bank. Your bank already sees your salary and balances. If an offer shows in its app, it's usually the quickest path to an instant personal loan 50000.
- A loan against gold or a fixed deposit. You pledge an asset, so your score matters less and the rate is often lower. Lose track of repayments, though, and you lose the asset.
- A fresh application with one verified lender. Pick a bank or NBFC, check its name on the RBI's lists, and apply once. Each application adds a hard enquiry to your report.
What should you skip? Applying to five apps at once. That pattern of enquiries makes the next lender more cautious. Our hard vs soft enquiry guide shows how each one lands on your report.
If an app sits between you and several lenders, the RBI's Digital Lending Directions (8 May 2025) require it to show every matching offer with the lender's name, the APR and the monthly repayment (RBI). One "best" offer with no lender named is a warning sign.
What CIBIL Score Do Lenders Expect for an Instant Loan 50000 to 5 Lakh?
No lender publishes a score for each loan amount. The pattern is simple: the higher the amount, the less room for a thin or patchy report.
GroScore's guidance treats 750+ as good and below 600 as the zone where approvals get hard (groscore.in). Read that against the amount:
- Around ₹50,000: NBFCs and app-based lenders may consider fair scores, often at a higher rate.
- An instant 1 lakh loan, up to ₹2 lakh: a clean last 12 months matters as much as the number. One recent 30-day late payment can cost you the offer.
- Up to ₹5 lakh: banks usually look for strong scores, steady income and low existing EMIs together.
Which score does the lender see? Any of the four RBI-registered bureaus: TransUnion CIBIL, Equifax, Experian or CRIF High Mark. "CIBIL score" is just the most common name. GroScore shows your Equifax score, which is usually close to the others but rarely identical. For indicative ranges by band, see our guide to the personal loan credit score.
Instant Loan EMI on ₹50,000, ₹1 Lakh, ₹2 Lakh and ₹5 Lakh
Here's what each amount costs at the same illustrative rate of 16% a year, over a tenure that's common for that size.
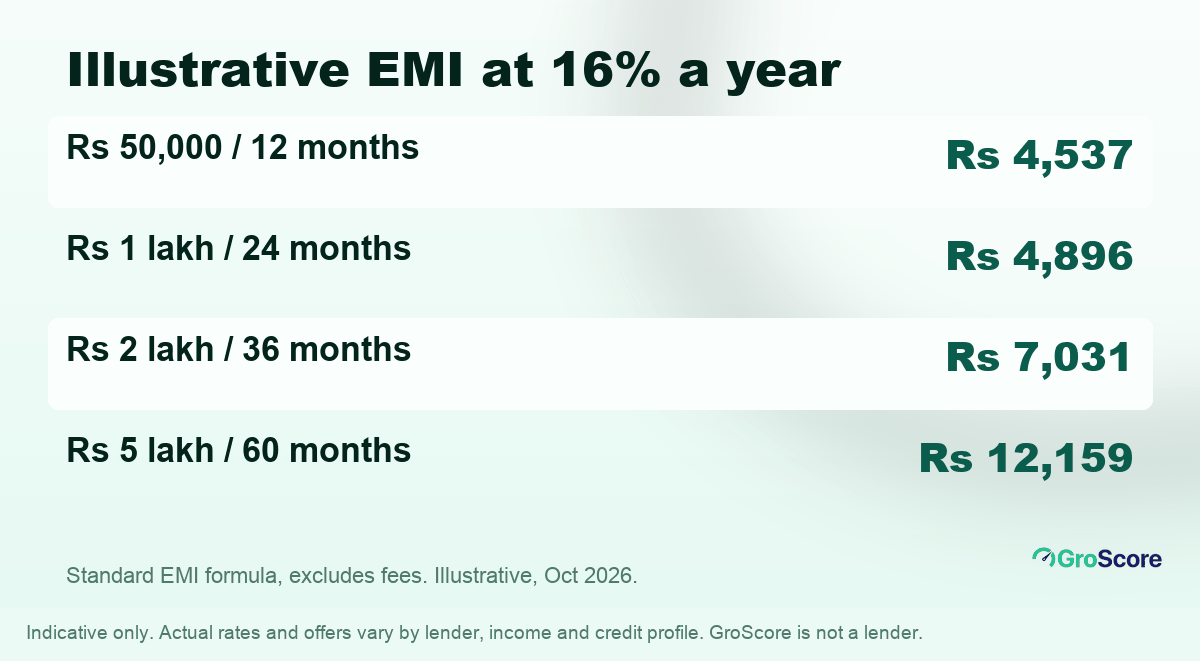
Illustrative example: the tenure stretches as the amount grows.
| Loan | Tenure | EMI at 16% | Total interest |
|---|---|---|---|
| ₹50,000 | 12 months | ₹4,537 | ₹4,439 |
| ₹1 lakh | 24 months | ₹4,896 | ₹17,511 |
| ₹2 lakh | 36 months | ₹7,031 | ₹53,131 |
| ₹5 lakh | 60 months | ₹12,159 | ₹2,29,542 |
Look at the first two rows. A ₹1 lakh loan has almost the same EMI as a ₹50,000 one because it runs twice as long, and you pay nearly four times the interest.
At 20%, the ₹50,000 EMI works out to about ₹4,632. We used the standard EMI formula, as of October 2026. These figures are illustrative, not offers, and leave out the processing fee. Actual offers vary by lender, income and credit profile.
To compare real offers, use the APR in the Key Fact Statement, not the headline rate. Since 1 October 2024, the RBI has required a KFS for every retail term loan, and a lender can't add a charge that isn't in it without your consent (RBI). See the real cost of an instant loan for how fees move the APR.
How Much Income Do You Need? A Worked Coaching Example
Lenders ask what share of your income already goes to EMIs. That share is FOIR (fixed obligations to income ratio). Many lenders get uneasy somewhere around half of take-home pay, though each sets its own line.
Suppose, as an illustrative example, that Neha, 28, takes home ₹35,000 a month and already pays an ₹8,000 bike-loan EMI. She wants ₹3 lakh for a family medical bill. Arjun, GroScore's credit coach, runs the numbers with her at an illustrative 16%:
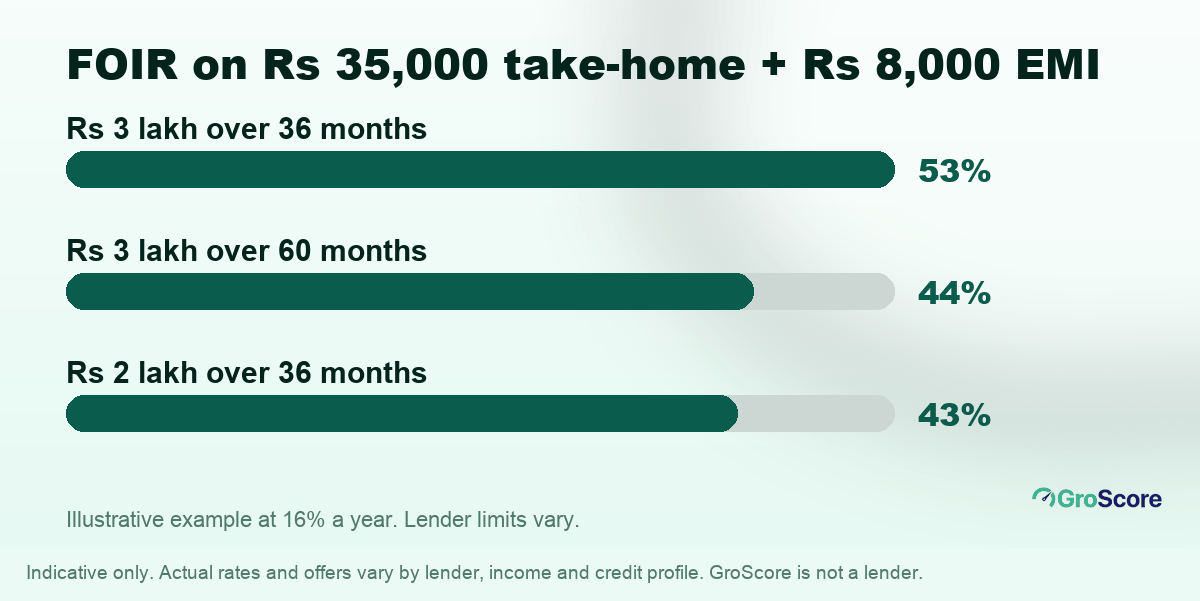
Illustrative example: the same income supports different loans.
- ₹3 lakh over 36 months: the EMI works out to ₹10,547, and her FOIR jumps to 53%. Many lenders would cut the amount or decline.
- ₹3 lakh over 60 months: EMI ₹7,295 and FOIR 44%. It fits, but interest rises from ₹79,696 to ₹1,37,725.
- ₹2 lakh over 36 months: EMI ₹7,031 and FOIR 43%. Interest is ₹53,131.
Arjun then reads her Equifax report and flags two things, in this order:
- A credit card at 71% of its limit (an indicative figure for this example). Paying it below 30% before her statement date is the fastest fix she controls.
- Three loan-app enquiries in six weeks. No new applications until she picks one lender.
His suggestion: borrow ₹2 lakh, ask the hospital about a payment plan for the rest, and skip a five-year debt for a short-term bill. He doesn't promise an approval. The lender decides.
Want the same check by job type? Our guide to loan eligibility by employment type covers salaried, self-employed and pensioner applicants.
Can You Get ₹50,000 Without Income Proof and CIBIL?
No regulated lender offers that. Every RBI-regulated bank and NBFC checks a credit report, and every one has to judge whether you can repay. An ad offering an instant 50000 loan without income proof and CIBIL is either a gold or FD loan in disguise, or a scam.
Fast is possible. No checks at all isn't.
Lenders can accept other proof in place of a payslip, as long as it shows money coming in regularly. Bank statements, ITR or GST returns often work. Our guide to a loan without income proof walks through them.
Spot any of these and walk away:
- A "processing fee" or "insurance" demanded before any money arrives.
- No bank or NBFC named anywhere in the app or agreement.
- Requests for access to your contacts or photo gallery.
- Money that comes from someone else's account. RBI rules say a digital loan must go straight from the lender into your own bank account.
Before you share anything, check the lender on the RBI's NBFC list and the app in the RBI's directory of digital lending apps.
Documents and Approval Time for Larger Instant Loans
For most amounts in this range, expect to give:
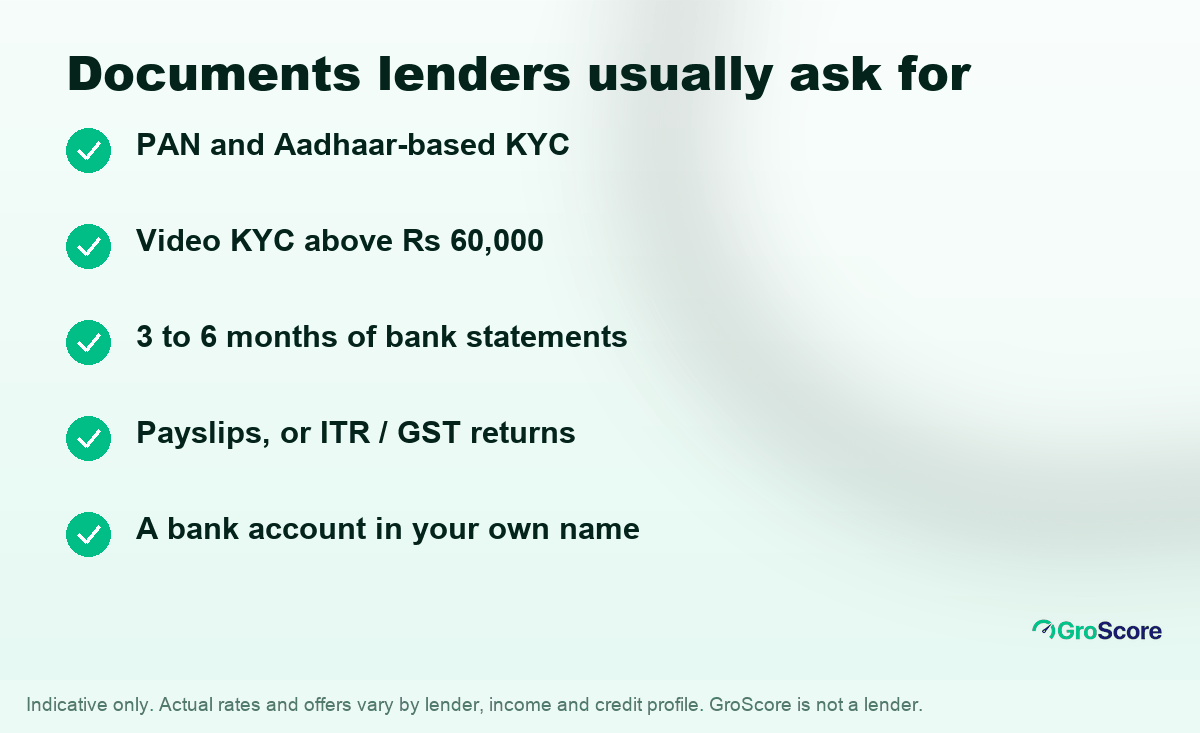
The list is short. The checks behind it aren't.
- PAN and Aadhaar-based KYC, or video KYC above ₹60,000.
- Three to six months of bank statements.
- Payslips, or ITR and GST returns if you're self-employed.
- A bank account in your own name for the money and the auto-debit.
A pre-approved offer at your own bank can be quick. A fresh ₹5 lakh application usually takes a working day or more, because income gets verified properly. Nobody honest can promise a time before checking you.
Two rules help after you sign. The cooling-off period lets you exit a digital loan in its first days (at least one day, set by the lender) by repaying the principal and the proportionate APR, with no penalty (RBI). And for loans sanctioned from 1 January 2026, lenders can't charge prepayment fees on floating-rate loans to individuals for non-business use (RBI). That rule doesn't cover fixed-rate loans, so check the foreclosure charge in your KFS. If you can't show full documents at all, read about an instant loan without documents and what KYC you still need.
Frequently Asked Questions
What CIBIL score do I need for a ₹1 lakh instant loan?
There's no fixed number. Each lender sets its own cut-off and may use any of the four bureaus. GroScore's guidance treats 750+ as good, and a clean last 12 months matters as much as the score at this amount. Below 600, approvals get hard.
What is the EMI on a ₹50,000 loan for 12 months?
About ₹4,537 a month at an illustrative 16% a year, with ₹4,439 of total interest. At 20% it works out to about ₹4,632. Add the processing fee and compare the APR in the Key Fact Statement before you decide.
Can I get ₹50,000 without income proof?
Sometimes, if a lender accepts bank statements, ITR or GST returns instead of payslips, or if you borrow against gold or an FD. A loan with no income check and no credit check isn't offered by regulated lenders.
How quickly is a ₹5 lakh personal loan disbursed?
It depends on the lender and on whether the offer is pre-approved. Pre-approved offers from your own bank tend to be fastest. A fresh application usually takes a working day or more because full KYC and income checks come first.
The Bottom Line
Going from ₹50,000 to ₹5 lakh isn't only about your credit score. Above ₹60,000 the KYC gets stricter, and your income has to carry a bigger EMI. Work out your FOIR first. Then borrow the smallest amount that solves the problem, over the shortest tenure you can manage, from one lender you've verified. Check your report before you apply, so a high card balance doesn't cost you the offer.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
