Instant Loan of 5000 to 20,000: Small Loan Options and Costs
Small loans look cheap in rupees and expensive as an APR. Here's how to pick one for Rs 5,000 to Rs 20,000 without getting caught by the fees.

You can get an instant loan of 5000 to 20,000 rupees from an RBI-regulated bank or NBFC, usually through its app or a lending app that names it as the lender. For very small amounts, a salary advance or a loan on your card limit may be cheaper. The catch is cost: fees on short tenures can push the APR far above the quoted rate, so check the Key Fact Statement first.
Key TakeawaysFor a Rs 5,000 loan over 15 days, a Rs 250 fee plus GST can turn a 24% rate into an APR of about 178% (illustrative, October 2026).Lenders can't charge any fee that isn't in your Key Fact Statement without your explicit consent (RBI).Small loans are reported to credit bureaus like any other loan. Paid on time, they can build your history; missed, they hurt it.Under RBI rules, a digital lender can't raise your credit limit automatically. You have to ask for it.
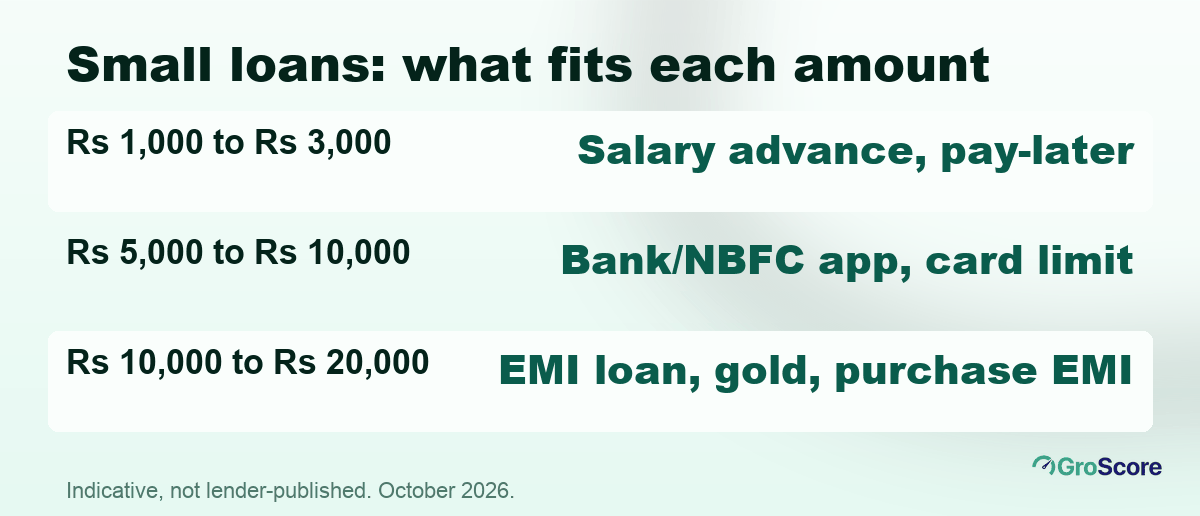
The right route depends on how much you need and how fast you can repay.
Where Can You Get an Instant Loan of 5000?
Small instant loans come from the same regulated lenders as big ones. The difference is the route. Here's what usually fits each amount:
| Amount | Options that usually fit | Watch for |
|---|---|---|
| Rs 1,000 to Rs 3,000 | Salary advance from your employer, pay-later limits, family | High fees relative to the amount |
| Rs 5,000 to Rs 10,000 | Small personal loan via a bank or NBFC app, loan on your card limit, pre-approved offer | Short tenures, flat fees |
| Rs 10,000 to Rs 20,000 | Personal loan with a few EMIs, consumer durable loan for a purchase, small gold loan | Stacking several loans at once |
Indicative, not lender-published, as of October 2026. Actual offers vary by lender, income and credit profile.
A quick word on who's writing. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score. GroScore is not a lender. It doesn't give, approve or disburse loans, and the score it shows is your Equifax score, not a CIBIL score. We don't name or rank lenders here.
Whatever the amount, the lender must be a bank or an NBFC registered with the RBI. A lending app is often just the front door. For how approval, KYC and disbursal work end to end, see how instant loans work.
What Does a 10000 Instant Loan Really Cost?
Less than you fear in rupees. More than you think as a yearly rate. A fixed fee weighs far more on a small, short loan than on a bigger, longer one.
Here are three illustrative small loans. Each processing fee is deducted upfront with 18% GST, and the maths works out as of October 2026.
| Loan A | Loan B | Loan C | |
|---|---|---|---|
| Amount and tenure | Rs 5,000, 15 days, one repayment | Rs 10,000, 3 monthly EMIs | Rs 20,000, 6 monthly EMIs |
| Rate and fee | 24% a year, Rs 250 fee | 30% a year, 2% fee | 24% a year, 2% fee |
| Cash you receive | Rs 4,705 | Rs 9,764 | Rs 19,528 |
| EMI or repayment | Rs 5,049 once | about Rs 3,501 | about Rs 3,571 |
| Interest | about Rs 49 | about Rs 504 | about Rs 1,423 |
| Total cost (interest + fee + GST) | about Rs 344 | about Rs 740 | about Rs 1,895 |
| Approximate APR | about 178% | about 45% | about 32.5% |
Illustrative figures as of October 2026, not offers. EMIs use the standard reducing-balance formula. APR is the yearly rate that matches the cash you receive to what you repay; Loan A uses a simple annual rate. Actual offers vary by lender, income and credit profile.
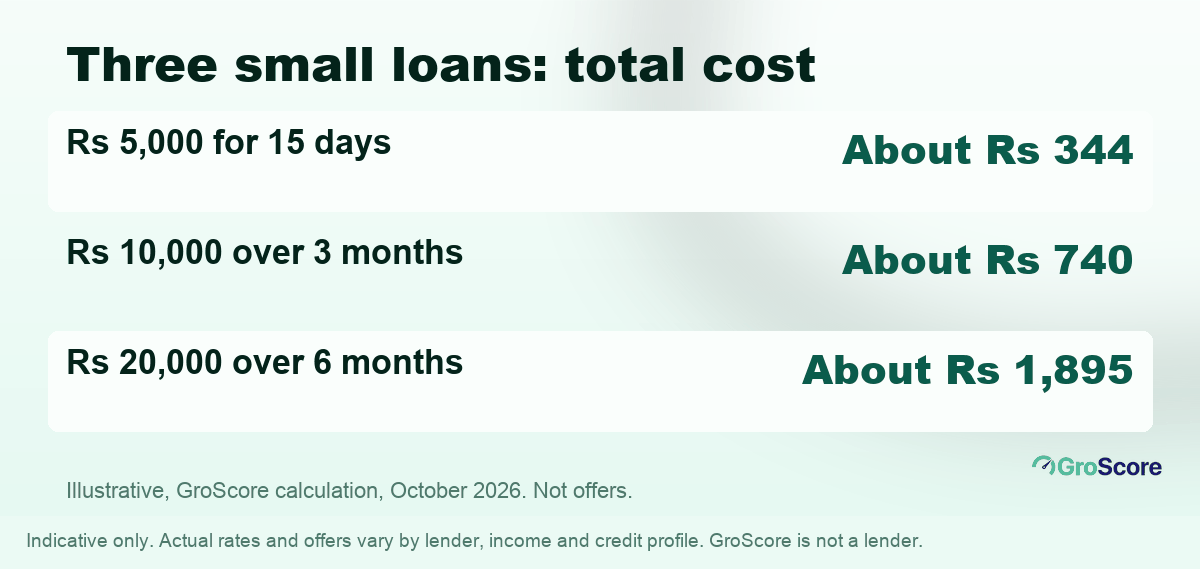
Illustrative example: the smallest loan costs the fewest rupees and the highest APR.
Read the table from the bottom up. Loan A costs only about Rs 344, which feels like nothing. But you paid that for 15 days' use of Rs 4,705. Stretch the same pattern across a year and it works out to about 178%.
So, for example, if you'll need the money for a few months anyway, one Rs 10,000 loan over three EMIs usually beats rolling a Rs 5,000 loan twice. Each rollover means a fresh fee. Our guide to the real cost of an instant loan explains flat versus reducing rates in detail.
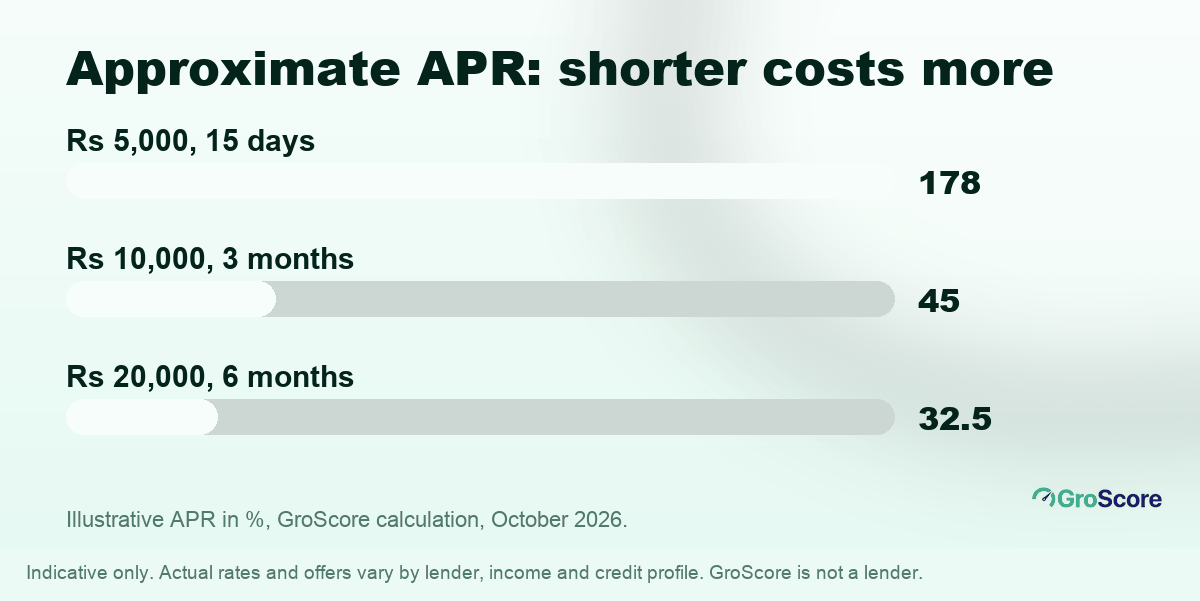
Same kind of fee, very different yearly cost (illustrative, October 2026).
Which RBI Rules Protect Small-Loan Borrowers?
Small loans get the same consumer protections as large ones. Five rules matter most here.
- A Key Fact Statement before you sign. It shows the APR and every charge. For loans shorter than seven days it must stay valid for at least one working day, and for longer loans at least three working days (RBI KFS rules, April 2024).
- No hidden charges. A fee that isn't in the KFS can't be charged at any stage without your explicit consent (RBI).
- Penal charges, not penal interest. If you pay late, the lender can levy a disclosed penal charge, but it can't add penal interest to your rate or charge interest on the penalty (RBI, Fair Lending Practice circular, August 2023).
- No automatic limit increases. Under the Digital Lending Directions, 2025, a lender can't raise your credit limit unless you ask for it and it assesses that request (RBI).
- Money only into your account. Disbursal goes straight to your bank account, never through the app's account.
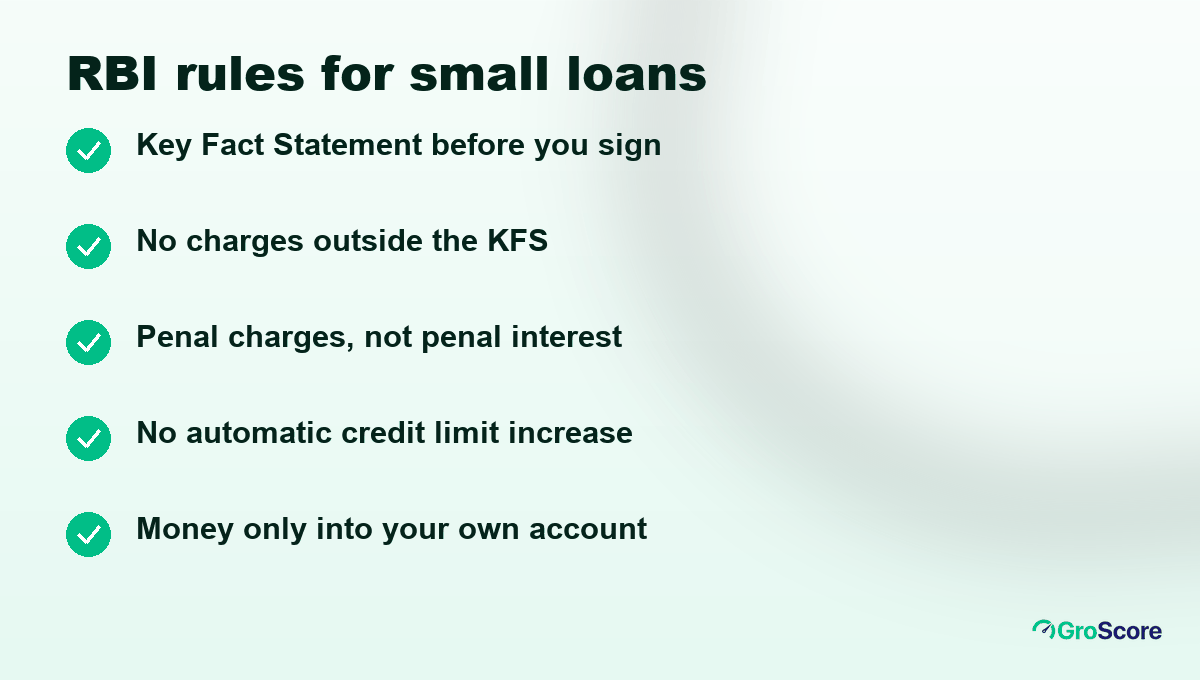
Five rules worth checking against any small loan offer.
One more applies to lower-income households. If your household earns up to Rs 3 lakh a year, a collateral-free loan counts as a microfinance loan. All your loan repayments together are then capped at 50% of monthly household income, and there's no prepayment penalty (RBI microfinance directions, 2022).
Loans that run for days rather than weeks carry extra traps, such as rollovers, covered in our page on payday-style short-term loans. You can confirm any lender on the RBI's list of registered NBFCs.
Do Small Loans Affect Your CIBIL Score?
Yes, both ways. A Rs 3,000 loan goes on your credit report just like a Rs 3 lakh loan. Lenders have reported to all four RBI-registered bureaus (TransUnion CIBIL, Equifax, Experian and CRIF High Mark) every week since 1 July 2026, so it shows up quickly (RBI).
Here's what helps and what hurts:
- Each application is a hard enquiry. Six small-loan applications in a month look like credit hunger.
- A missed EMI on a small loan is still a missed EMI. GroScore says a single missed EMI can cost 50 to 100 points (groscore.in).
- Small loans repaid on time build a repayment history, which CRIF High Mark notes can help first-time borrowers (CRIF High Mark).
- Several open small loans at once can make a new lender wary, even if you've paid each one.
Small amount, full-sized consequences.
Can You Get a 2000 Loan Instantly With No CIBIL Score?
Sometimes. Having no score isn't the same as a bad score. It means bureaus show "NH" or "-1" because you've never borrowed. Some lenders do lend small amounts to new-to-credit borrowers, leaning on bank statements and KYC instead.
Equifax notes that consumer durable lenders are often more comfortable with customers who have no credit history. A small EMI purchase you'd make anyway can be a gentler start than a cash loan (Equifax). A secured card against an FD is another route.
Our guide to having no credit score explains what "NH" means and how to start a history safely. Whatever you choose, borrow only an amount you can repay from your next salary or income.
What Would a Credit Coach Flag Before Your Next Small Loan?
Here's an illustrative example. Say Karan, 26, wants a 10000 instant loan to cover rent while his salary is delayed. His Equifax score is 664. Arjun, GroScore's credit coach, reads his report with him and flags three things, in this order:
- Three open app loans of Rs 3,000 to Rs 6,000. Each was a fresh fee. A fourth adds another fee and another open account. Arjun suggests repaying the costliest one first.
- A 12-day late payment on one of them last month. It's accurate, so it stays on the report. Setting up auto-debit stops a second one.
- Five enquiries in six weeks. Another round of applications would make the next lender more cautious. Pick one regulated lender.
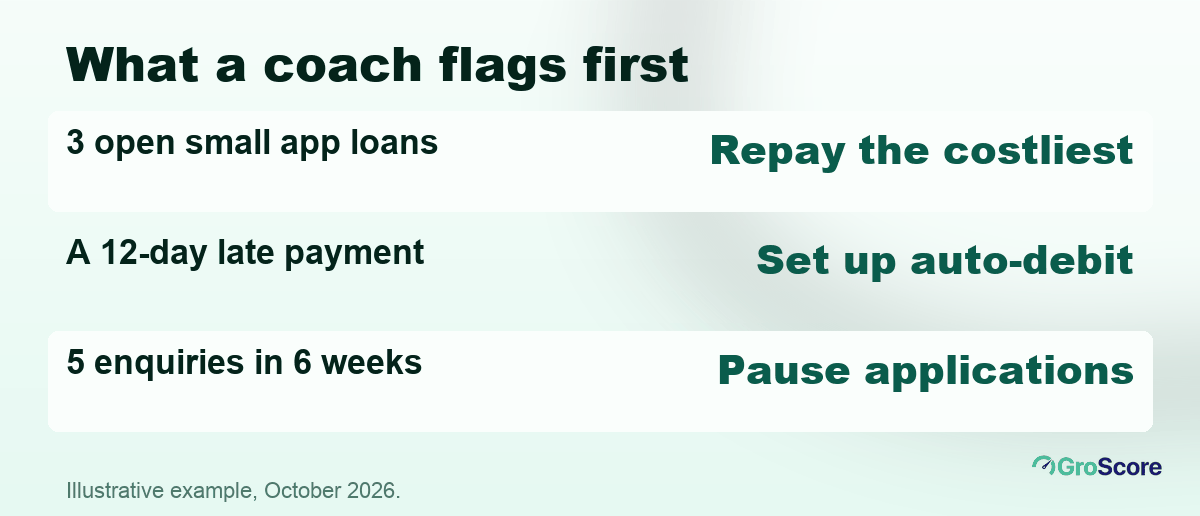
Illustrative example: clear the clutter before adding another loan.
Arjun doesn't promise Karan a loan, since lenders decide. He also points out that a salary advance from his employer, if offered, may cost nothing at all. Checking your own score is a soft enquiry and never lowers it.
GroScore can show which lenders' criteria your profile clears, across 100+ loans and credit cards from 60+ banks and NBFCs (groscore.in). Lenders still run their own checks.
How to Spot a Predatory Small-Loan App
Small-ticket loans are where illegal apps cluster, because borrowers in a hurry skip checks. Walk away if you see any of these signs:
- The app asks for a fee before any money arrives.
- It doesn't name an RBI-registered bank or NBFC as the lender.
- It wants access to your contacts, photos or call logs.
- It won't show a Key Fact Statement before you accept.
If your score is low and you're comparing apps, our guide to loan apps for a low CIBIL score shows how to check each one.
Frequently Asked Questions
Where can I get an instant loan of 5000?
From an RBI-regulated bank or NBFC, often through its app or a lending app that names it as the lender. A salary advance or a loan on your card limit can be cheaper for small amounts. Confirm the lender on the RBI's NBFC list before sharing documents.
What is the real cost of a 10000 rupee loan for 30 days?
It depends mostly on the fee. For example, at 24% a year, 30 days of interest on Rs 10,000 is about Rs 197. Add a Rs 300 fee plus Rs 54 GST, and the total is about Rs 551, an APR of about 70% on the cash you receive. Always check the KFS.
Do small loans affect my CIBIL score?
Yes. Every loan is reported to the credit bureaus, whatever its size. On-time repayment can help build your history, while a missed EMI or many applications in a short time can lower your score.
Can I get a 2000 loan with no CIBIL score?
Possibly. Some lenders lend small amounts to new-to-credit borrowers using bank statements and KYC. No score isn't a bad score; it just means there's no history yet. Avoid any app that asks for a fee upfront.
The Bottom Line
A small instant loan is easy to get and easy to overpay for. Compare the APR in the Key Fact Statement, not just the rupee fee, and avoid rolling short loans over. Borrow from one regulated lender at a time, and repay on schedule so the loan builds your history rather than denting it. If you're borrowing small amounts often, that's a sign to look at your report and budget first. Need more than Rs 20,000? Read about an instant loan of Rs 50,000 to Rs 5 lakh instead.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
