Instant Personal Loan Without Income Proof: What's Possible
No salary slip doesn't always mean no loan. It does mean you need another way to show you can repay, and a sharp eye for scams.

An instant personal loan without income proof of any kind is rarely possible from an RBI-regulated lender, because lenders must check that you can repay. Without a salary slip, though, you can often qualify on bank statements, ITR, GST returns or an existing relationship with your bank. A secured loan against gold or an FD needs the least proof of all.
Key Takeaways"No income proof" usually means "no salary slip". Lenders still look at your income through bank statements, ITR or GST returns.RBI's digital lending rules require lenders to record your economic profile, including income, before lending (RBI).A loan against an FD or gold leans on the asset, not your payslip, and is often cheaper.An app that lends to anyone with no checks, for an upfront fee, is a scam warning.
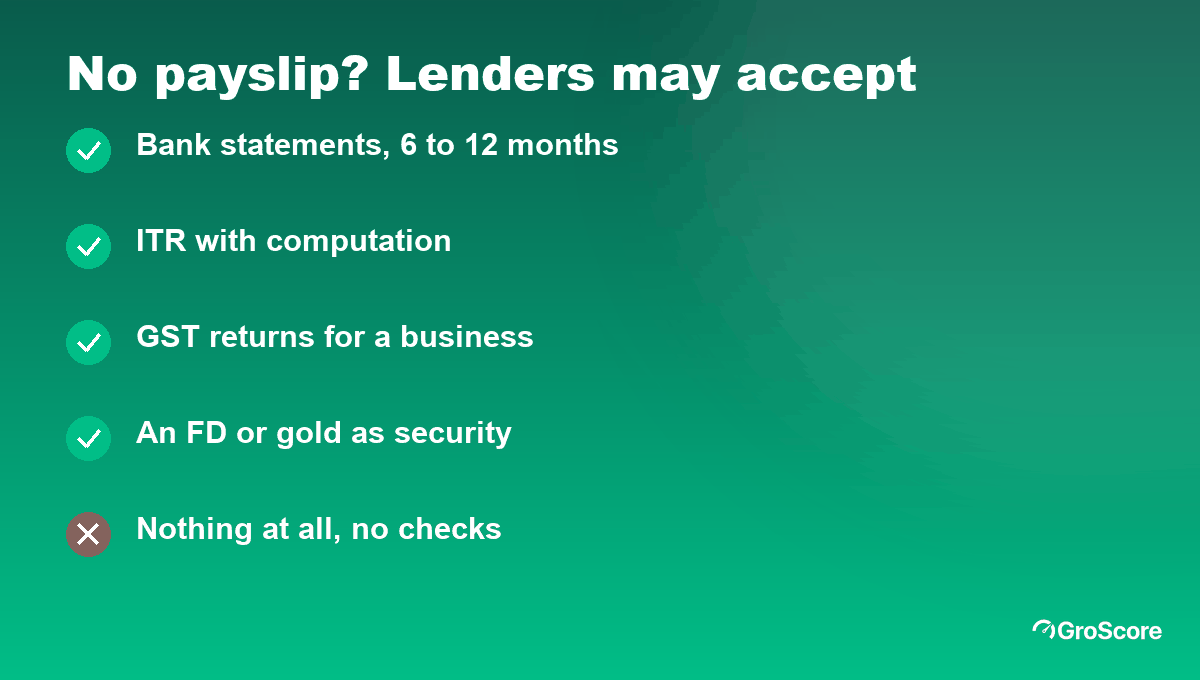
Most lenders want some proof of income, just not always a payslip.
Can You Get an Instant Personal Loan Without Income Proof?
Partly, and it depends on what "without income proof" means for you.
You have income but no salary slip. This is the common case: freelancers, shop owners, gig workers, people paid in cash or by UPI. Here the answer is often yes, because your bank account tells the story a payslip would. Lenders read your credits, balances and bounced payments.
You have no income at all. Students, homemakers and people between jobs fall here. An unsecured instant loan is then unlikely from a regulated lender, and an app that offers one anyway deserves suspicion. Secured loans, or a co-applicant with income, are the realistic routes.
GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, explains in Hindi or English what is holding the score back, and gives a step-by-step plan to fix it. GroScore is not a lender. It doesn't give, approve or disburse loans, and its number is your Equifax score, not a CIBIL score.
Keep two problems apart, too. KYC documents (PAN, Aadhaar) prove who you are. Income proof shows you can repay. Lenders need both, and an app that skips either one isn't doing you a favour.
For the full picture of how fast loans work, start with our guide on how instant loans work.
What Can You Show Instead of a Salary Slip?
Lenders accept different documents, and policies change. These are the common substitutes:
| What you show | Who it suits | What the lender reads |
|---|---|---|
| Bank statements (often 6 to 12 months) | Freelancers, gig workers, UPI earners | Regular credits, average balance, bounced EMIs |
| ITR with computation | Self-employed, professionals | Declared income over one or more years |
| GST returns | Registered businesses | Turnover and its consistency |
| Platform payout statements | Delivery and ride-hailing partners | Weekly or monthly earnings pattern |
| Existing bank relationship | Anyone with a long account history | What your bank already sees |
Many lenders now pull bank statements digitally, with your consent, through the RBI's Account Aggregator framework instead of asking for PDFs. You approve the share in your banking app, and you can choose the period.
Can you get an instant loan without salary slip documents if you're salaried? Sometimes. A bank where your salary is credited may treat those credits as proof. A lender you've never banked with will usually ask for more. Our guide to an instant bank loan compares banks with NBFCs and loan apps.
Do Freelancers and Gig Workers Qualify?
Often, yes, if the money flows through a bank account and your credit report is clean. The catch is how lenders count irregular income.
Lenders look at FOIR (fixed obligations to income ratio), the share of your income already going to EMIs. With a salary, income is easy to pin down. With freelance credits, some lenders count only part of what lands in your account, because it varies. Each lender sets its own rules, and few publish them.
Here's an illustrative example. Suppose Kavya, a freelance designer, has average monthly bank credits of ₹40,000 over six months and already pays an ₹8,000 EMI. Assume a lender allows total EMIs up to 50% of counted income, and charges 18% a year over 24 months.
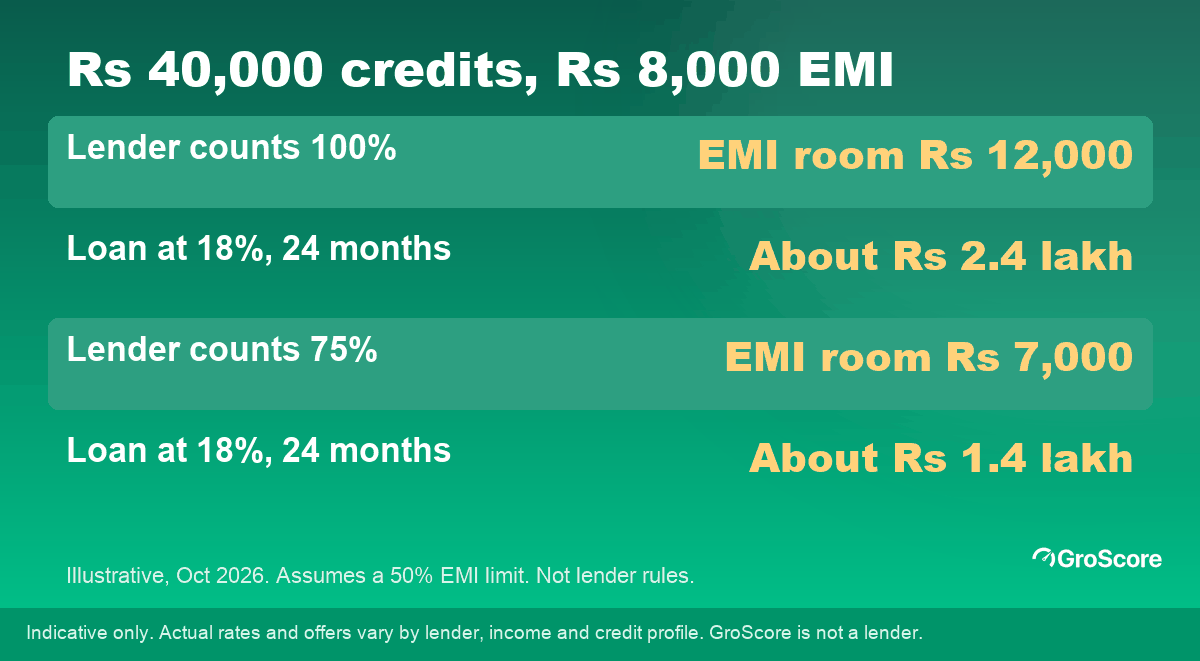
Illustrative example: how much of your income a lender counts changes the loan size.
If the lender counts all ₹40,000, half of it is ₹20,000. Minus her ₹8,000 EMI, that leaves room for a ₹12,000 EMI, which works out to a loan of about ₹2,40,365 (roughly ₹2.4 lakh). If it counts only 75% of her credits, that is ₹30,000. Half is ₹15,000, which leaves ₹7,000 of room and a loan of about ₹1,40,213 (roughly ₹1.4 lakh). That's the same person and the same bank account, with a ₹1 lakh difference. These figures are indicative, worked out with the standard EMI formula as of October 2026; the 50% and 75% are assumptions, not lender rules. Actual offers vary by lender, income and credit profile.
Freelancers can help themselves most in four ways: keep work income in one account, avoid bounced payments, file ITR even if your income is modest, and don't let personal and business money blur together. Lenders read the same signals when they decide on instant loan approval, so clean records help there too.
Why Do No-Income-Proof Loans Cost More?
Less certainty means more risk for the lender, and risk gets priced in. When income is harder to verify, lenders that do approve tend to offer smaller amounts, shorter tenures or higher rates.
For example, take an illustrative ₹1,00,000 loan over 12 months. At 15% a year, the EMI works out to ₹9,026 and total interest to ₹8,310. At 24%, the EMI is ₹9,456 and interest is ₹13,472. That's ₹5,162 more for the same money, before any processing fee. These are indicative figures, not offers.
Fees can matter as much as the rate. The Key Fact Statement must show the APR, the all-in yearly cost including fees, before you sign (RBI). Our guide to the real cost of an instant loan shows how to compare APRs.
Secured Alternatives That Need Less Income Proof
If you can't show regular income, a loan backed by something you own is usually the safer, cheaper route.
- Loan against an FD. You borrow against your own fixed deposit, which keeps earning while pledged. It's often priced a little above the FD's rate.
- Gold loan. The gold is the security, so the lender leans less on your income and score. Miss payments, though, and the lender can auction it.
- Loan against mutual funds or shares. Some banks and NBFCs lend against pledged investments.
- A co-applicant. A family member with income and a strong score applies with you. A missed EMI hurts their score too.
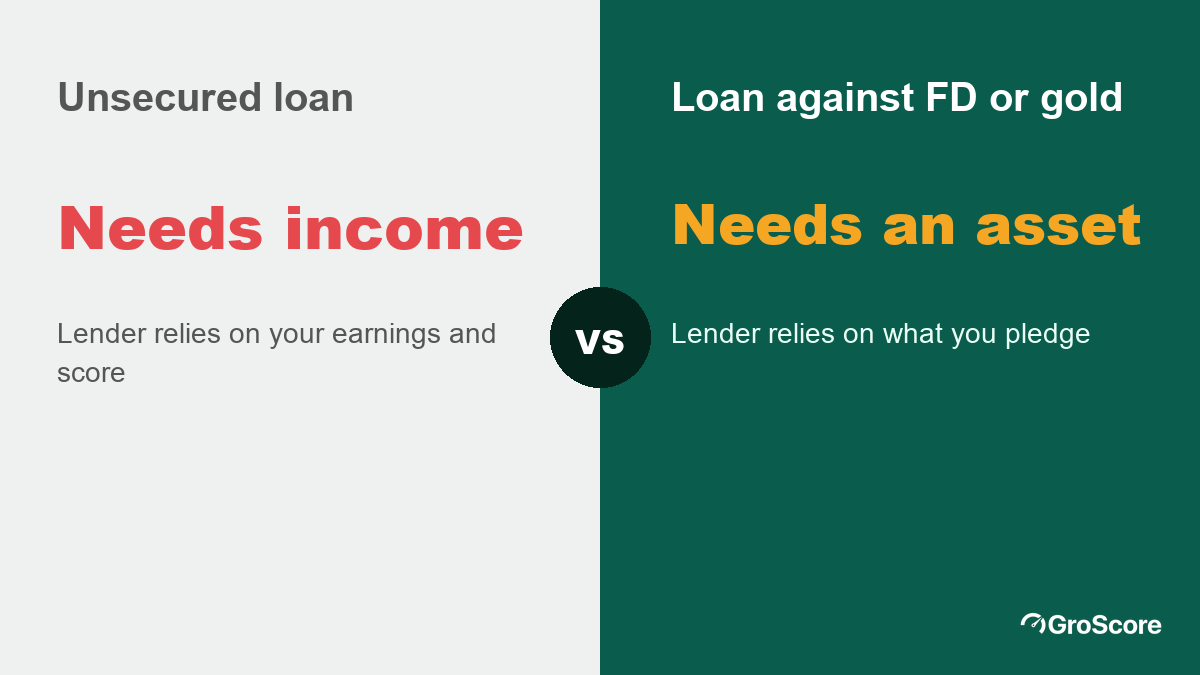
An asset can stand in for a payslip.
Our page on a personal loan with a low CIBIL score compares these options side by side.
Red Flags: When "No Income Proof" Means Scam
Searches for a loan app without income proof turn up plenty of apps that should worry you. Before you share any document, check that the bank or NBFC behind the app appears on the RBI's list of registered NBFCs, and look for the app in the RBI's directory of digital lending apps. Then walk away if you see any of these:
- The app promises approval for everyone, with no documents and no credit check.
- It asks for a "processing" or "verification" fee before any money arrives.
- It won't name the RBI-regulated bank or NBFC that actually lends.
- It wants access to your contacts, photos or call logs.
- It pushes you to decide within minutes.
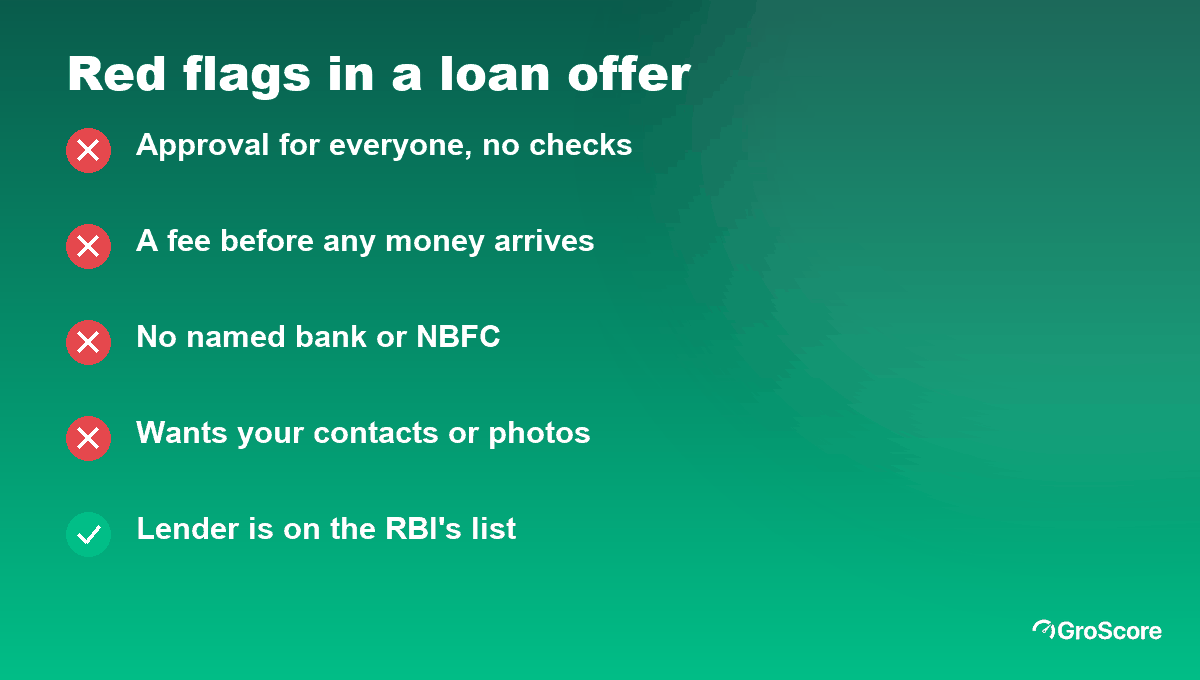
Any one of these is enough to stop.
If you've already paid a fee and got nothing, stop paying and keep the screenshots. Report the app on the RBI's Sachet portal, and call the national cybercrime helpline on 1930 or file at cybercrime.gov.in. Our guide on how to check if a loan app is RBI-registered walks through every step.
What Would a Credit Coach Check First?
Here's an illustrative example: suppose Farhan, 29, drives for a ride-hailing platform and wants ₹50,000 for a phone and repairs. Arjun, GroScore's credit coach, looks at his Equifax report and flags three things, in this order:
- Three bounced auto-debits in the past year. Lenders reading his bank statement will see them too, so the next six months need to be clean.
- No credit card or loan history beyond one phone EMI. A thin file means lenders have little to go on, and a secured card can help build it.
- An address mismatch between his PAN and his bank records. Small KYC gaps like this slow down a fast application.
Why check the report at all if income is the problem? Because errors are common: GroScore says about 1 in 5 reports carries one, roughly 20% (groscore.in, retrieved 2026-10-05). A wrong entry hurts a thin-file borrower more than most.
Arjun can't promise Farhan a loan; the lender decides. GroScore can show which lenders' criteria a profile clears, across 100+ loans and credit cards from 60+ banks and NBFCs (groscore.in).
Frequently Asked Questions
Can I get a personal loan without salary slips?
Often, yes, if you can show income another way. Bank statements, ITR or GST returns can stand in for payslips, and the bank where your salary is credited may not need slips at all. With no income to show, a secured loan or a co-applicant is more realistic.
What can I show instead of income proof?
You can show 6 to 12 months of bank statements, ITR with computation, GST returns or platform payout statements. Many lenders fetch bank statements with your consent through the Account Aggregator framework. An existing relationship with your bank can also count.
Do gig workers and freelancers qualify?
Many do, if their earnings land in a bank account regularly and their credit report is clean. Lenders may count only part of irregular income, so the loan offered can be smaller than you expect. Filing ITR and avoiding bounced payments helps.
Why do no-income-proof loans cost more?
When a lender can't verify income easily, it carries more risk and usually prices it in through a higher rate, a lower amount or a shorter tenure. Compare the APR in the Key Fact Statement, which includes the processing fee, before you accept.
The Bottom Line
An instant personal loan without income proof is mostly a question of what proof you can offer. Bank statements, ITR and GST returns open more doors than people expect, and secured loans open more still. No regulated lender will skip the checks entirely. Check your report, gather your statements, and apply once to a lender you've verified. New to credit altogether? A secured card against an FD is a common first step to build a credit score from scratch.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
