Urgent Personal Loan: How to Get Money Fast, Safely
When you need money urgently, the fastest safe option is usually one you already have access to. Here's how to pick it, and what it really costs.

The fastest safe way to get an urgent personal loan is usually through credit you already have: a pre-approved offer from your own bank, a loan against gold or a fixed deposit, or your credit card. These skip most of the checks a fresh application needs. A new loan from an RBI-regulated lender comes next. Anyone promising cash with no checks at all is the one to avoid.
Key TakeawaysSpeed comes from what the lender already knows about you. Pre-approved offers and secured loans usually move fastest.Credit card cash withdrawals are quick but costly: one large issuer charges 2.5% (minimum Rs 500) plus finance charges from day one, with no interest-free period (issuer terms, October 2026).Under the RBI's Digital Lending Directions, 2025, an app loan must be paid straight into your bank account, and fees owed to the app can't be charged to you (RBI).Before you sign, read the Key Fact Statement. It shows the all-in cost as an APR.
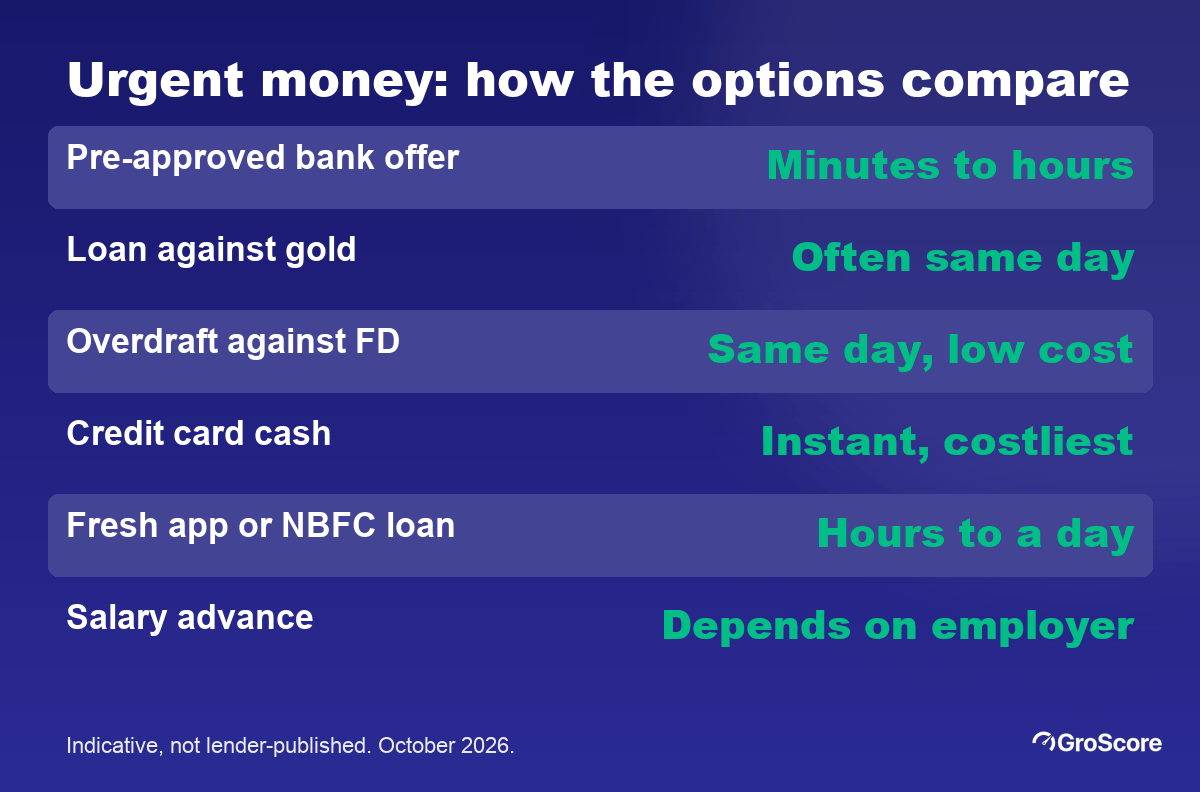
Fast and cheap rarely sit in the same row. Pick the trade-off you can live with.
How Can You Get Money Urgently in India?
Start with what's already in your name. If you need urgent cash, the best instant emergency loan is usually one where the lender did its homework on you before today.
Before the options, a word on who's writing. GroScore is a free credit score app and personal credit coach from Vitrak Technologies (GroMo). It shows your Equifax credit score and full report with a soft check that never affects your score, and explains what's holding the score back. GroScore is not a lender. It doesn't give, approve or disburse loans, and the number it shows is your Equifax score, not a CIBIL score. We don't name or rank lenders here.
Here's how the common routes compare:
| Option | How fast, usually | Cost, indicative | Watch for |
|---|---|---|---|
| Pre-approved offer from your bank | Minutes to hours | Close to normal personal loan rates | Can be withdrawn after a fresh check |
| Loan against gold | Often same day | Usually lower than unsecured loans | Auction if you can't repay |
| Overdraft against an FD | Same day, often online | A small margin over the FD rate | Ties up your deposit |
| Credit card cash withdrawal | Immediate at an ATM | Among the costliest | Interest from day one |
| Fresh loan from a bank, NBFC or app | Hours to a working day | Wide range, check the APR | Hard enquiry, fake apps |
| Salary advance from your employer | Depends on payroll | Often low or nil | Not every employer offers it |
Indicative, not lender-published, as of October 2026. Actual offers vary by lender, income and credit profile.
If you've never taken a loan online, our guide to the instant personal loan explains how approval and disbursal work.
Urgent Personal Loan Options: Which Is Fastest and Cheapest?
Speed and cost pull in opposite directions. A worked example shows how far apart they can be.
Say you need Rs 30,000 for 60 days to cover a medical bill. Here's what four routes would cost, worked out as of October 2026 with indicative figures:
| Route (indicative terms) | Interest | Fees incl. 18% GST | Total cost |
|---|---|---|---|
| Overdraft against an FD, 8% a year | about Rs 395 | none assumed | about Rs 395 |
| Gold loan, 10% a year, Rs 500 fee | about Rs 493 | Rs 590 | about Rs 1,083 |
| App loan from an NBFC, 30% a year, two EMIs of about Rs 15,565, 3% fee | about Rs 1,130 | Rs 1,062 | about Rs 2,192 |
| Card cash withdrawal, 2.5% fee, 3.75% a month | about Rs 2,250 | Rs 750 fee, plus Rs 540 GST on fee and interest | about Rs 3,540 |
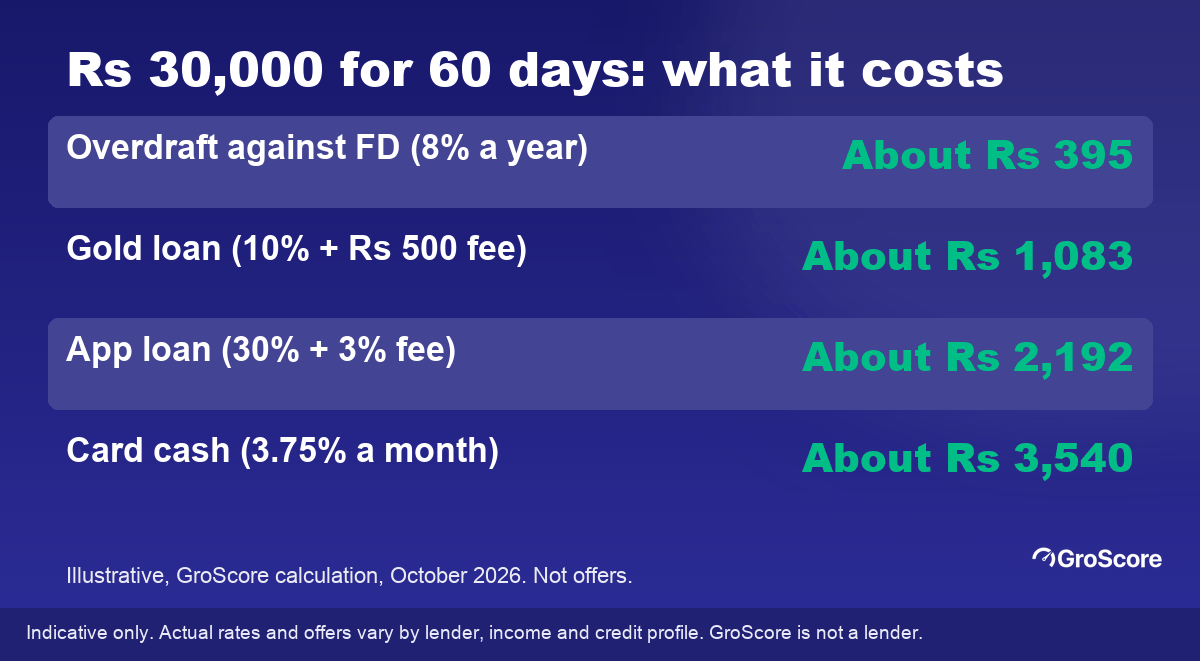
Illustrative example: the same Rs 30,000 can cost nine times more depending on the route.
For example, the cheapest route here costs about a ninth of the dearest. We used simple interest for the overdraft and gold loan, the standard EMI formula for the app loan, and one card issuer's published monthly rate. An FD overdraft also leaves your deposit earning while you draw on it. None of these are offers. Actual offers vary by lender, income and credit profile.
So which is fastest? A card cash withdrawal is instant. A pre-approved offer can be close behind. Gold and FD-backed loans often pay out the same day, because the asset does most of the convincing.
If you're pledging gold, two RBI rules from the Lending Against Gold and Silver Collateral Directions, 2025 (in force from 1 April 2026) are worth knowing. A lender must return your gold within seven working days of full repayment, or pay you Rs 5,000 for each day of delay it causes. Bullet-repayment gold loans for consumption are capped at 12 months (RBI). Our page on the gold loan with a low CIBIL score covers loan-to-value limits and auction risk.
Is a Loan on Your Credit Card a Good Emergency Option?
Sometimes. People use "loan on credit card" for two different products, and only one of them suits an emergency.
A cash withdrawal (cash advance) is the ATM route. You get quick cash in minutes, at one of the highest prices. One large issuer's published terms (retrieved 2026-10-06) charge 2.5% of the amount (minimum Rs 500), finance charges of up to 3.75% a month, and no interest-free period on cash. Interest runs from the day you withdraw.
A loan on your card limit works differently. Many issuers offer a pre-approved loan carved out of your unused limit, repaid in fixed EMIs. It's usually cheaper than a cash withdrawal and often needs no fresh documents. It still blocks part of your limit, which pushes your card utilisation up until you repay.
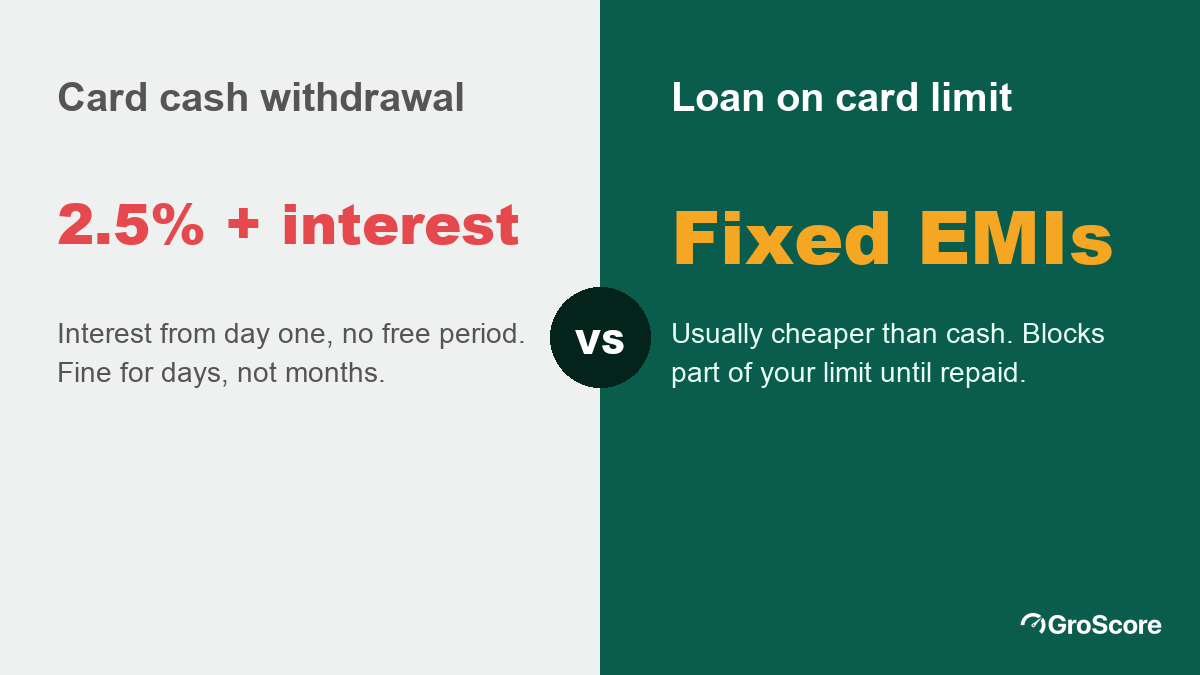
Same card, two very different costs.
Use a cash withdrawal only for a gap of days, not months. If you'll need longer, ask your issuer about a loan on the limit, or look at a secured option first. Only need a few thousand rupees? Our page on small instant loans shows what short tenures really cost.
Urgent Loan Online: What the RBI Requires of Lending Apps
Applying for an urgent loan online is fine if the lender is regulated. The RBI's Digital Lending Directions, 2025, dated 8 May 2025, set out what a genuine lender and its app must do (RBI):
- Pay the loan into your own bank account. Disbursal to a third party's account, including the app's, isn't allowed.
- Give you a Key Fact Statement with the APR before you sign. Signed copies must reach your registered email or phone.
- Pay the app's fees itself. Anything the lender owes the loan service provider is paid by the lender.
- Show every matching offer. Since 1 November 2025, an app that works with several lenders must display all offers that match your request, without pushing one through dark patterns. Compare them on APR, as our guide to the real cost of an instant loan shows.
- Stay out of your phone. Apps must not access your contacts, call logs, files or media.
- Let you exit early. A cooling-off period of at least one day lets you repay the principal and the proportionate APR without a penalty.
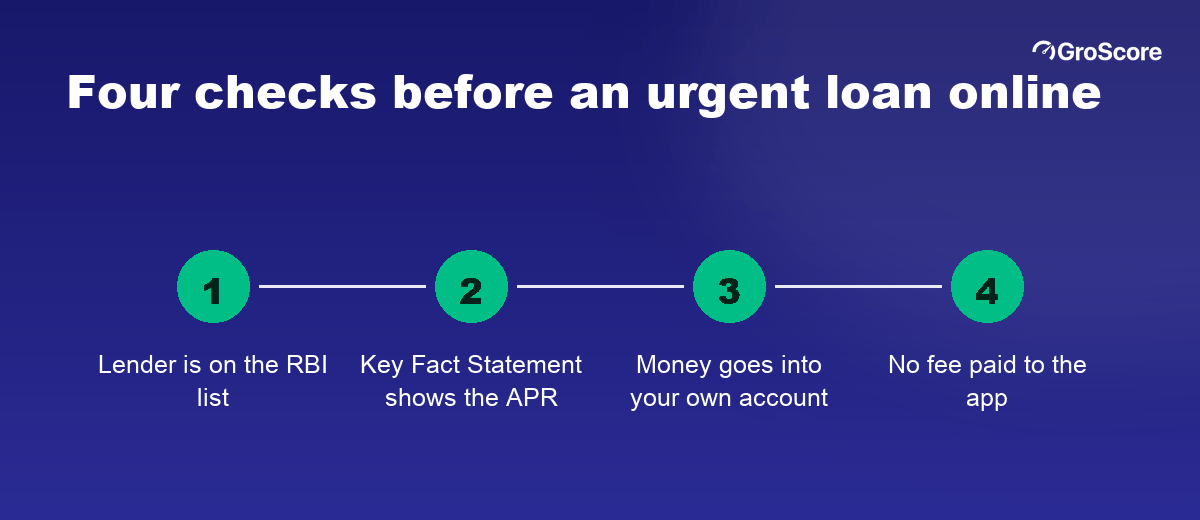
Four checks that take ten minutes and can save you from a fake app.
You can confirm the lender behind an app on the RBI's list of registered NBFCs, and check the app in the RBI's directory of digital lending apps.
Can You Get an Urgent Loan With a Low CIBIL Score?
Sometimes, but it's harder and usually costlier. Every RBI-regulated lender checks a credit report from one of the four RBI-registered bureaus: TransUnion CIBIL, Equifax, Experian or CRIF High Mark. GroScore's guidance treats below 600 as the zone where approvals get hard (groscore.in).
With a low score, secured routes are your friend. A gold loan or an overdraft against an FD leans on the asset, so your report matters less. A co-applicant with a stronger profile can also help. Our guide to a loan for a low CIBIL score walks through each one and its risks.
Applying to five apps in an afternoon doesn't work. Each one adds a hard enquiry, and a cluster makes the next lender more cautious.
An urgent cash loan without a salary slip is possible with some lenders, who read bank statements or ITRs instead. Approval still isn't guaranteed. No regulated lender promises a loan without checking your credit.
What Would a Credit Coach Check Before You Borrow in a Hurry?
Here's an illustrative example. Say Meera, 34, needs Rs 40,000 within two days for a car repair her job depends on. Her Equifax score is 718. Arjun, GroScore's credit coach, looks at her report with her and flags three things, in this order:
- A pre-approved offer is possible. Her salary account bank has seen three years of credits. Check that app first, before any fresh application.
- A card at 64% of its limit (an indicative figure for this example). Taking a cash withdrawal on top would push it higher and cost the most. Skip it.
- Two enquiries from last week, from apps she tried and abandoned. A third and fourth would read as credit hunger. Pick one lender and stop.
Notice what Arjun doesn't do. He doesn't promise a loan, because the lender decides. He helps Meera choose the route that costs least and leaves her report in better shape. Checking your own score is a soft enquiry and never lowers it.
GroScore can show which lenders' criteria your profile clears, across 100+ loans and credit cards from 60+ banks and NBFCs (groscore.in). Lenders still run their own checks.
How to Avoid Urgent-Loan Scams
Scammers love urgency. When you need money urgently, you're more likely to skip a check, and that's exactly what they count on.
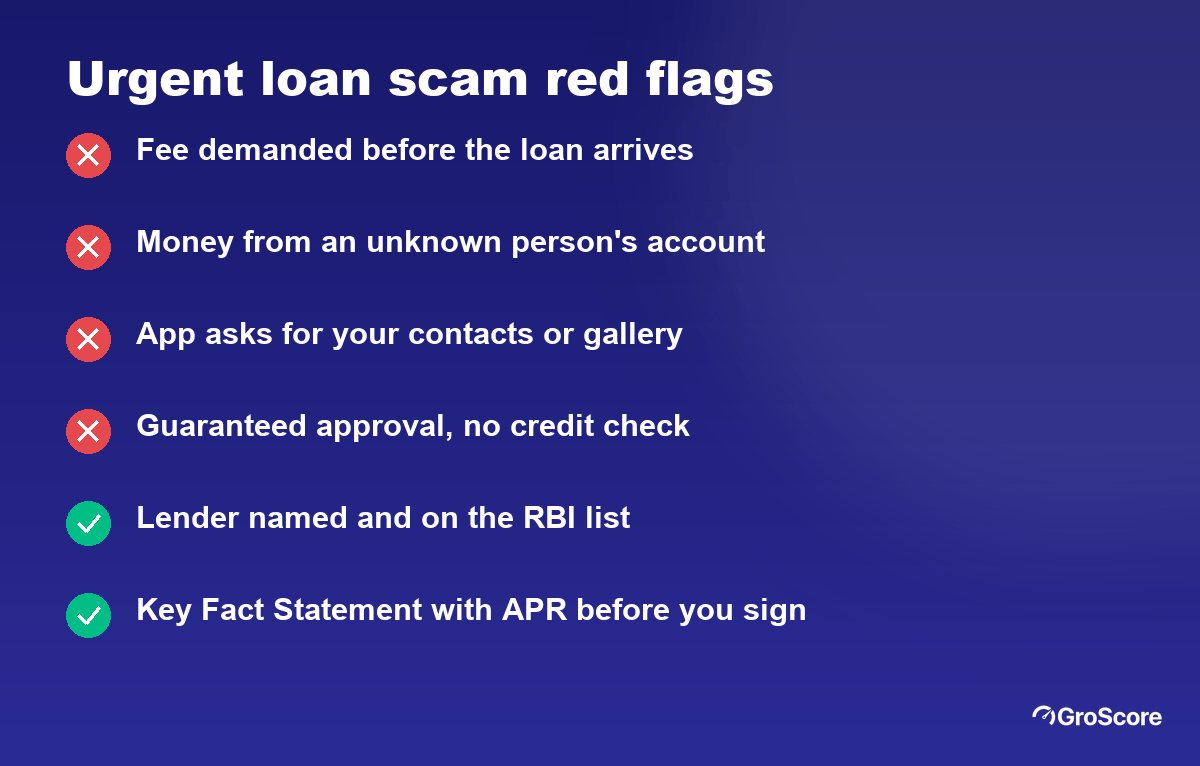
One of these is enough to walk away.
Stop if any of these happen:
- The app demands a "file charge", "insurance" or "GST" before the loan arrives, often to a personal UPI ID.
- The money lands from someone else's account instead of the lender's.
- The app asks for access to your contacts or gallery.
- The ad talks of guaranteed approval or "no CIBIL check", which isn't possible from a regulated lender.
Paid already and got nothing? Stop paying and keep every screenshot. Report the app on the RBI's Sachet portal (sachet.rbi.org.in), call the national cybercrime helpline on 1930, and file at cybercrime.gov.in. Our guide to fake loan apps explains each step, including what to do if you're harassed.
Frequently Asked Questions
How can I get money urgently in India?
Start with credit you already have: a pre-approved offer from your bank, a loan on your card limit, or a loan against gold or an FD. These usually move fastest because the lender already knows you or holds an asset. A fresh application to an RBI-regulated bank or NBFC comes next.
Which loan is fastest to get in an emergency?
A credit card cash withdrawal is instant, but costly. Pre-approved offers and gold or FD-backed loans often pay out the same day. For example, in our illustrative Rs 30,000, 60-day case, an FD overdraft cost about Rs 395 and a card cash withdrawal about Rs 3,540.
Is a loan on my credit card a good emergency option?
A loan carved out of your card limit, repaid in EMIs, can be reasonable for a short gap. A cash withdrawal usually isn't: one large issuer charges 2.5% upfront plus up to 3.75% a month from day one, with no interest-free period.
Can I get an urgent loan with a low CIBIL score?
Possibly, through a gold loan, an overdraft against an FD or with a co-applicant. Unsecured approvals get hard below 600, per GroScore's guidance, and rates are usually higher. Avoid anyone promising approval without a credit check.
How do I avoid urgent-loan scams?
Never pay a fee before the loan arrives, and confirm the lender on the RBI's NBFC list and the app in the RBI's directory of digital lending apps. Under RBI rules the money must come into your account straight from the lender, and apps can't access your contacts.
The Bottom Line
An urgent personal loan doesn't have to be an expensive one. Check what you already have access to before you apply anywhere new, and compare the total rupee cost, not just the speed. Borrow once, from a lender you've verified. If you can wait even two or three weeks, fixing a maxed-out card or an error on your report may get you a cheaper offer. Our guide to how to improve your credit score shows where to start.
Disclaimer
This GroScore article is for general education and is not financial advice. GroScore provides credit scores and reports sourced from Equifax, an RBI-licensed credit bureau; scores differ between bureaus and change as lenders report new data. Credit score improvement depends on your individual credit behaviour and bureau reporting timelines, and results are not guaranteed. Loan and card decisions are made by lenders on their own criteria. GroScore is not a lender. Figures and rates shown are indicative.
